New, usedor commercial
Finance for new or used boats, and finance for commercial boats too. The tinnie and the trawler go through the same office and the same panel of lenders.
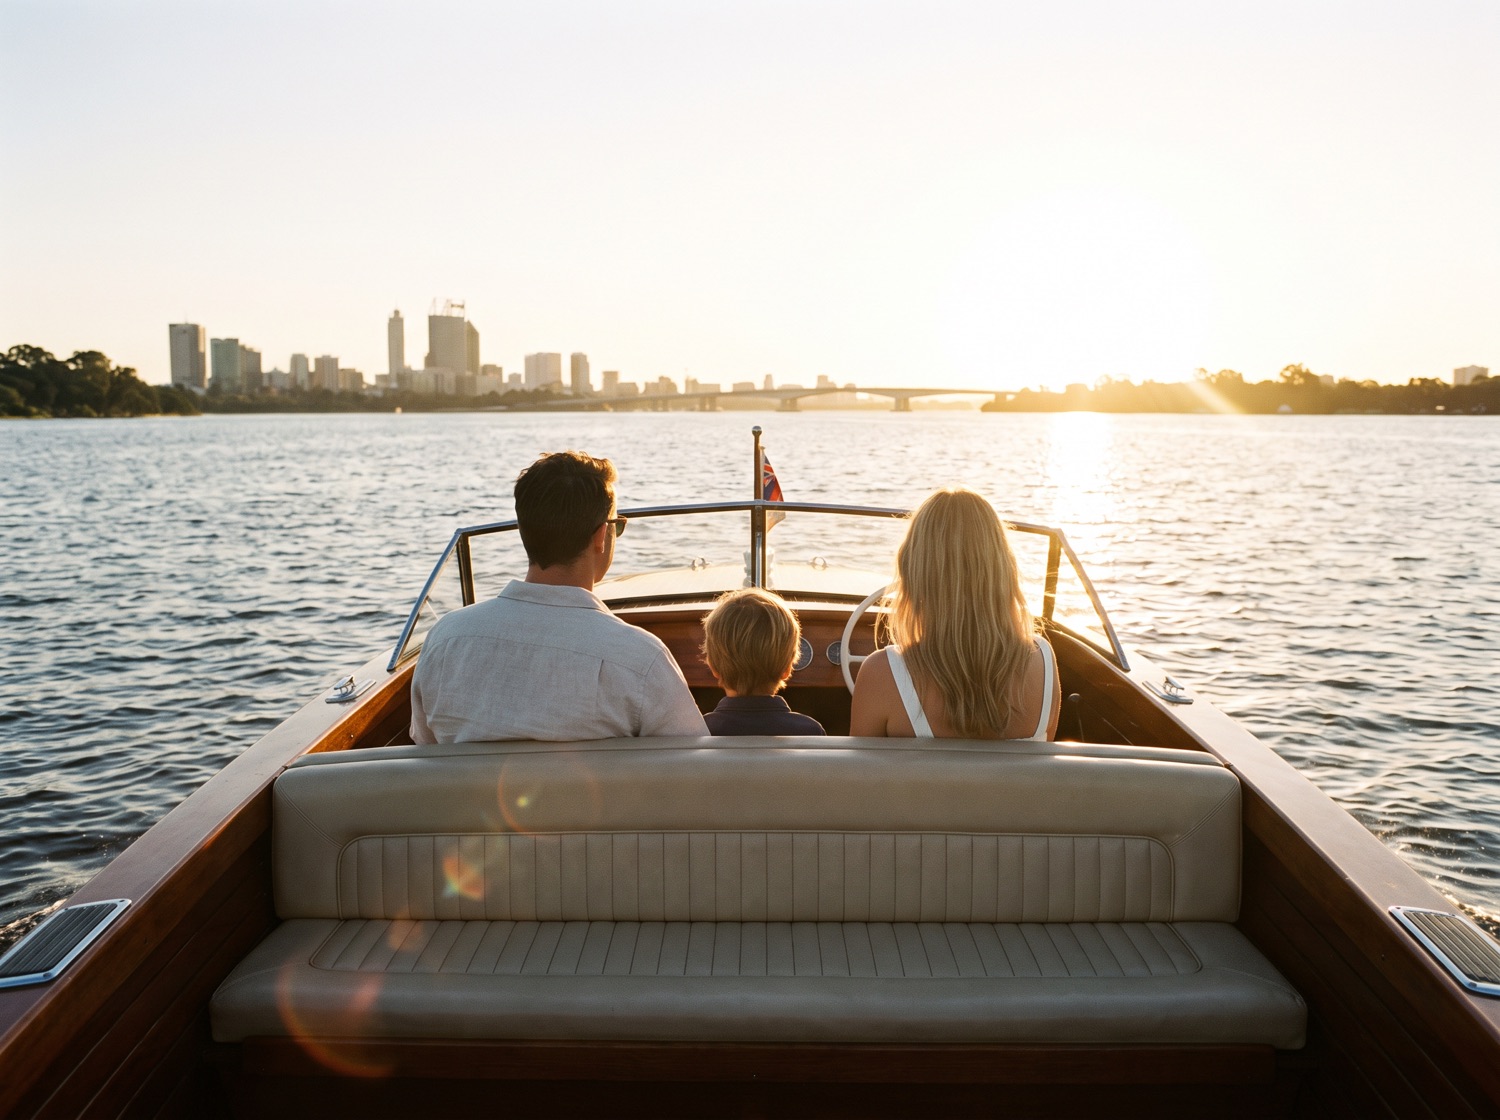
Imagine you're cruising down the River with the warm sunshine on your back and the cool breeze of freedom in your hair. Yes Loans can help make your water-bound dreams come true, by offering you access to boat financing in Perth, all over Western Australia and Australia wide.
A boat loan is an installment loan that comes with fixed monthly payments. There are two types you can get right now, and which one you are offered has less to do with your credit than most people expect.
Finance for new or used boats, and finance for commercial boats too. The tinnie and the trawler go through the same office and the same panel of lenders.
One person reads your file, talks to the panel on your behalf and comes back to you with the answer. You are not starting again with whoever picks up the phone.
Boat loans from $5,000 and up, with flexible repayment terms to match your lifestyle and budget rather than the lender's default.
At Yes Loans, our experienced brokers will guide you through the process of applying for a boat loan quickly and efficiently. That's why you need to meet our team.
One question settles a boat application before your income is even looked at: can the vessel be registered, and therefore can a lender take security over it. Pick the closest match and we will tell you how a lender reads it.
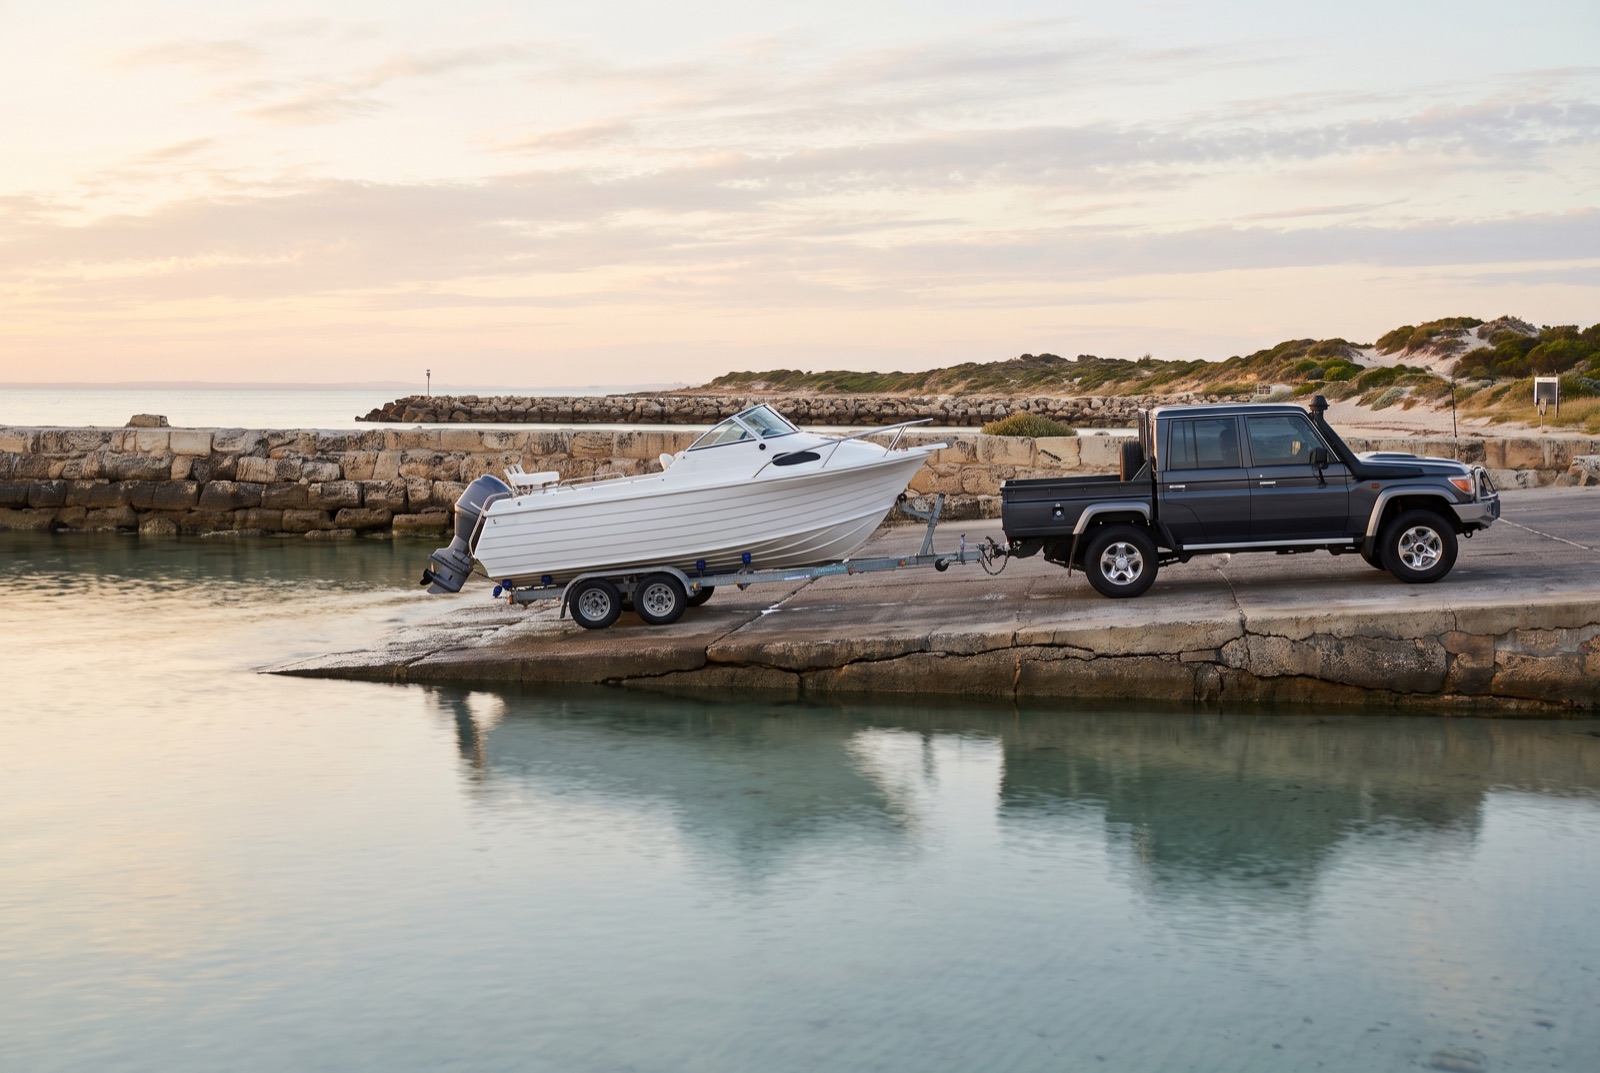
The Perth boat. Pens and marina berths in this city are scarce enough that the overwhelming majority of boats live on a trailer in a side yard and go in the water when somebody wants them to. Which means what you are actually buying is three things: a boat, a trailer, and a car big enough to pull both.
Not sure which side of the line your boat falls on? A registered vessel can be held as security and an unregistrable one cannot, and that single fact decides which loan you are offered. Send us the make, the length and the engine and we will tell you before you go anywhere near a deposit.
Move the numbers around until the weekly figure looks like something you would happily pay through a whole summer, then send it to a broker to be turned into a real quote.
We are a broker, so we do not set this. Lenders do, per file, and a boat with no hull identification number will sit higher on this slider than a registered one. Move it to whatever you want to test and your broker will come back with the rate a lender will actually write.
You will be shown the sharpest end of whatever the panel is offering that week. Try the lower end of the rate slider.
Indicative costs, and easiest to finance when they are on the invoice at the time of purchase. Adding them after settlement is a separate conversation.
A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees and the term in writing, from the lender, before you commit to anything.
The loan is the same secured boat loan in all three cases. What changes is what the lender asks you for, and how much of the term you can actually have.
The sharpest end of the panel, because the security is new, the HIN is already on the hull and what the boat is worth is not in question.
Dealer finance quoted to you as a weekly figure. Ask for the rate, the comparison rate, the fee and any balloon in writing before you compare it to anything.
Usually a small step up from new, and the gap narrows on a late model hull with a service history for the engine behind it.
A repower nobody wrote down. A new engine on an old hull transforms what a lender will do with the file, but only if there is an invoice for it.
Where most second hand boats in Perth actually change hands, and usually where the value is. The same secured rates apply, and the same checks matter more.
Paying a deposit before the PPSR search comes back clear. Photograph the HIN plate and the engine serial number too, and check the number on the hull is the number on the registration papers before anything changes hands.
A well built fibreglass hull is good for thirty years and a lender knows it. The outboard hanging off the back is not, and that is where the age policy actually bites. A 1998 hull with a five year old four-stroke on it and an invoice to prove the repower is a completely different application from the same hull with its original motor, even though the listing describes them the same way. Ask the seller for the engine's year and hours before you ask for the boat's, and get the repower invoice if there is one.
A Hull Identification Number is compulsory for every registered vessel in Western Australia, and a boat cannot be registered or transferred without one. That number is not paperwork. It is the thing that makes a secured boat loan possible, and the thing that tells you whether the boat you are about to buy already belongs to somebody else's lender.
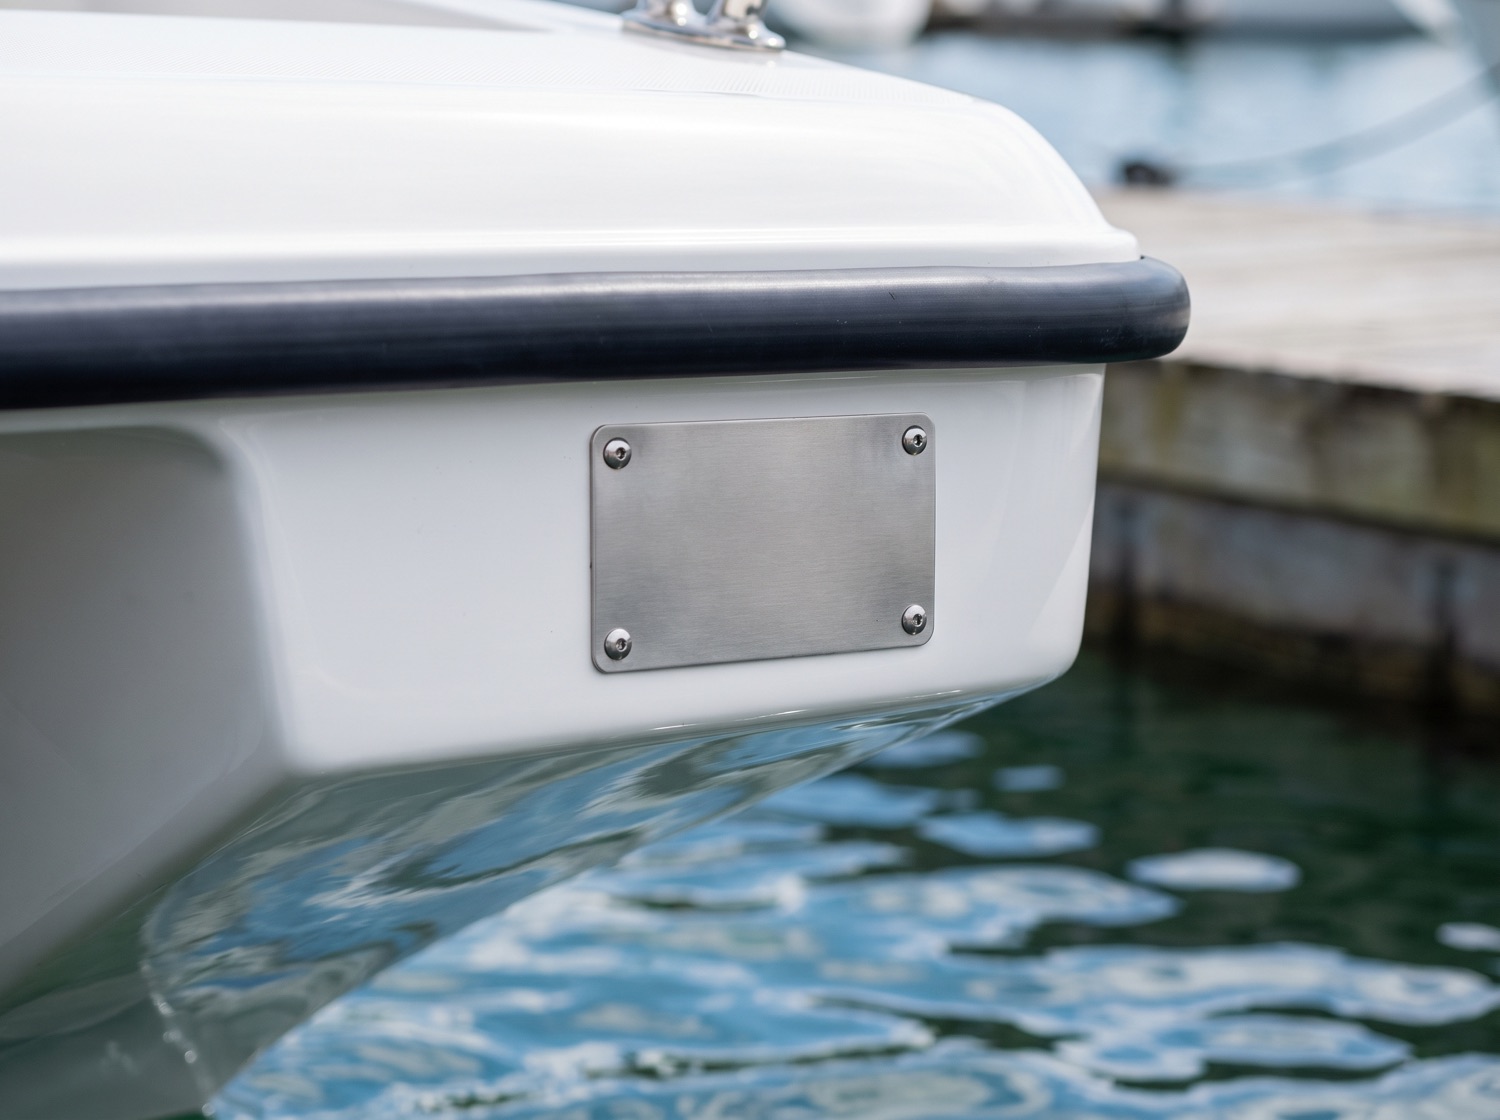
A unique string of characters and numbers, moulded into the hull or engraved on a metal plate fastened to it. The manufacturer fits it to a new boat. On an older one an accredited BoatCode provider inspects the hull and fits it, and some of them will come to the boat rather than making you trailer it in.
It gives the vessel an identity, which is how a stolen boat is stopped from being re-registered. It also lists the boat on the Personal Property Securities Register: the register a lender writes its security interest into, and the register a second hand buyer searches to find out whether there is money still owing.
A lender securing against a boat has to be able to register that interest against something. The HIN is that something. No HIN means nothing to register, which means no secured boat loan, which means the money has to come from somewhere more expensive.
A boat with no hull identification number is not a dead end. Get one fitted by an accredited BoatCode provider before settlement and the same purchase becomes a secured loan, on the cheaper product, at a longer term. It is a small job holding up a big one, and it is worth knowing about it in the week you are negotiating rather than the week you are settling.
A bank runs one credit policy and yours either fits it or it does not. A broker runs a panel, which is a different job: finding the lender whose policy already has room for your situation. Every answer below has a condition attached, because the honest ones do.
The most common leisure file we see. No history is not bad history, but it is unproven, so a lender reads income stability and savings conduct instead. A deposit does a great deal of work here.
Paid or unpaid, a listed default does not end the conversation. It moves the rate and often the deposit. Put a higher rate into the estimator above and you will see what that actually costs a week.
There are lenders who will assess an ABN as young as twelve months on BAS and bank statements rather than two full years of tax returns. The paperwork is different, not heavier.
Ordinary in Western Australia and handled badly by a lot of online lenders. A lender who understands rosters and shutdowns will assess the whole income rather than the base, which matters on a boat because the boat is what the roster is for.
Charter operators, cray fishermen, dive schools and marine trades finance boats through the business all the time. If the vessel genuinely earns, a chattel mortgage, a hire purchase or a lease may be the better structure than a leisure loan. Speak to your accountant first, then bring us the answer.
If the rate was set at a dealer counter three summers ago it is worth a second look, particularly if your credit position has improved since. Refinancing a boat loan works the same way as refinancing a car loan.
The purchase price is the part everybody budgets for. These five are the part that turns a comfortable repayment into an uncomfortable summer, and most of them can be financed with the boat if they go on the invoice at the time of purchase.
In Western Australia you must register any recreational vessel that is or can be driven by mechanical power, including a sailing boat able to carry a motor. Registration runs twelve months and has to be renewed, and it applies to a boat sitting on a mooring or in a pen just as much as one that goes out every weekend.
You need an RST to operate a recreational vessel with a motor over 6 horsepower, or 4.5 kilowatts, in Western Australia. You can sit it from fourteen, there is nothing to renew and no ongoing fee, and only the skipper needs one. Get it before settlement rather than after, because the boat is not much use in the driveway.
If the boat has not got a HIN it needs one before it can be registered or transferred into your name, and the certificate is part of the paperwork on the day. An accredited BoatCode provider fits it. It is a small job that holds up a big one.
Not optional on a secured loan. The lender holds the vessel as security, so cover has to be in place from settlement, and it wants the trailer on the policy too. We arrange insurance as well, so it does not have to be a separate errand.
Perth is a trailer boat city, so for most buyers the rig is three purchases wearing one price tag. Check the car's braked towing capacity and towball download against the laden weight of boat and trailer together before you commit to the boat, and if the car has to change, finance both at once.
The trailer, the sounder, the safety gear and the first year of cover are all financeable at the time of purchase. Added after settlement they become a separate and more expensive conversation, so decide on them before the paperwork goes in.
 Yes Loans
263 Albany Hwy, Victoria Park
 A big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
 Thanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
 I cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week
powered by Google
At Yes Loans, our experienced brokers will guide you through the process of applying for a boat loan quickly and efficiently, and will expand on any part of the form you have questions about. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.
Perth's second hand boat market wakes up in spring and the well priced rigs are gone within days of listing. Turning up with a pre-approval already in hand changes what you are negotiating: the price of the boat, rather than whether you can move fast enough to buy it at all.
A lender's conditional yes on an amount and a rate, given before you have chosen a boat. It commits you to nothing and you can still walk away from the whole idea.
Most pre-approvals stay live somewhere between 30 and 90 days depending on the lender, which covers the several weekends of looking that come before a purchase.
Nothing. Getting your rate through us does not affect your credit score either, because one application reaches the whole panel instead of you applying to lenders one at a time.
Your broker is in Victoria Park, twenty minutes from the Canning Bridge pens and half an hour from the Fremantle ramps, so the person reading your file knows the market you are buying in. Call (08) 9472 3000 or get your rate online.
Imagine you're cruising down the River with the warm sunshine on your back and the cool breeze of freedom in your hair. Owning a boat is one of life's true pleasures and taking your own boat for a long family holiday, bachelor weekend away, or even a fun day out, will be sure to make you the envy of your family and friends.
Yes Loans can help make your water-bound dreams come true, by offering you access to boat financing in Perth, all over Western Australia and Australia wide. At Yes Loans, our experienced brokers will guide you through the process of applying for a boat loan quickly and efficiently.
A boat loan is an installment loan that comes with fixed monthly payments. There are two types of boat loans you can get right now.
A secured boat loan makes use of the purchased boat as its collateral. This type of loan can have higher loan limits, lower rates and longer repayment terms compared to an unsecured loan.
On the other hand, an unsecured boat loan doesn't require anything as collateral. But with no backing, the rates that you're going to get will most likely be higher, with shorter terms than a secured boat loan.
Gone are the days of wishing you could take your family and friends out on the open water. Gone are the days of asking your mates to take you out on their boat when you want to go fishing. Gone are the days of stressing about how to increase your commercial fleet without straining your cashflow. Gone are the days of wishing you could teach your kids to ski behind your very own boat. Apply online now or call us on +61 894 723 000 to discuss your loan and finance options.
Purchasing a boat is just like any other financial investment right now; it takes time and effort so you can get the one that's best for your needs. Before you jump right in, here are some questions to ask yourself first.
What do you plan to do with it? The needs that you have in mind will help in determining the type of boat design you're going to get. There are many styles available right now from the deep-hulled models which are great for offshore boats to the flat-hulled designs ideal for fly-fishing. Determine what your performance criteria are first before starting your search.
Where will you store it? The size of your planned boat is going to depend on the storage area you have. That's why it's important that you first measure things up to avoid being disappointed at a later date.
Who will operate the boat? Make sure you research the power and weight ratio of the boat you want as not all cars are capable of pulling some types of boats. People who are inexperienced may also find some boats difficult to handle so make sure you also bring a friend or two who can help you out.
Extended Warranty. This type of insurance is an ideal safeguard in case breakdowns or faults with your vehicle occur, providing additional security and less worry.
As a reputable finance company, Yes Loans can provide you with the boat loan package you need right now. Here are some of the common choices you can choose from below:
Commercial Boat Loans. Various options are available when you take out a commercial marine loan which can range from hire purchases or leases.
Jet Ski Finance. These vessels are quite the fun things to have out in the sun, and this type of loan is made just to cater to those looking to get one nowadays.
New & Used Boat Loans. Two kinds of boat loans exist for personal use which is secured and unsecured.
Boat Engine Finance. You're not only limited to getting new seafaring vessels right now but can also take advantage of a package that upgrades your boat motor.
Yes Loans has been providing various businesses with the boats that they need to get going. We have an experienced team who can help you choose the best packages that you need in order to achieve your goals today. What makes us stand out from the rest is that our loans can be customised according to your preferences.
If you're interested in what we have to offer or have any questions regarding any of them, feel free to give us a call now.
Say YES to easy, affordable boat finance. Say YES to Yes Loans today!
Gone are the days of asking your mates to take you out on their boat when you want to go fishing. Gone are the days of wishing you could teach your kids to ski behind your very own boat. Apply online now or call us on +61 894 723 000 to discuss your loan and finance options.
You've probably seen the ads. An app promises to unlock a slice of your wages before payday, no interest, just
Thinking about a personal loan for a renovation, a holiday, a medical procedure, or to bring a few debts together?
If you've been searching for short term loans in Australia, you've probably noticed the results are a mixed bag.
Not to get the loan, but you need one to use the boat. In Western Australia you need an RST to operate a recreational vessel with a motor over 6 horsepower, or 4.5 kilowatts. You can sit it from fourteen, only the skipper needs one, and there is nothing to renew and no ongoing fee. Riders under sixteen are limited to daylight hours and to under 8 knots. Plenty of buyers arrange the finance while they are still working through the ticket.
In Western Australia you must register any recreational vessel that is or can be driven by mechanical power, including a sailing vessel able to carry a motor, and that applies to a boat on a mooring or in a pen as much as one that goes out every weekend. Registration runs twelve months and is renewed annually. Craft with no motor are exempt, as are stand-up paddle boards and similar with a motor under 4.5kW, and a tender no more than 3.1 metres with a motor no bigger than 5hp used only as a tender.
A Hull Identification Number is a unique series of characters moulded into the hull or engraved on a plate fastened to it. It is compulsory for every registered vessel in Western Australia, and a boat cannot be registered or transferred without one. For your lender it is the thing that makes the loan secured: the HIN is what lists the vessel on the Personal Property Securities Register, which is where a lender records its security interest. No HIN means nothing to register against.
Yes, and it works differently. With nothing for a lender to register a security interest against, the purchase is funded as an unsecured personal loan rather than a secured boat loan. That costs more and the term is usually shorter. The better move, if you have time before settlement, is to have an accredited BoatCode provider inspect the hull and fit a HIN, which turns the same purchase back into a secured loan.
A secured boat loan makes use of the purchased boat as its collateral. This type of loan can have higher loan limits and longer repayment terms compared to an unsecured loan. An unsecured boat loan doesn't require anything as collateral, but with no backing the terms are usually shorter. Which one you are offered comes down to whether the vessel can carry a registered security interest at all.
Yes. Private sales are where most second hand boats in Perth change hands and often where the better prices are. We verify the seller owns the boat outright and that there is no finance owing against it, then the lender pays the seller directly on settlement.
A PPSR search against the hull identification number will tell you, and it takes minutes. That is precisely what the HIN is on the register for. Do it before you pay a deposit rather than after, and check that the number on the hull matches the number on the registration papers while you are there. Your broker runs one as part of a private sale purchase anyway, so ask before you hand anything over.
Yes, on the same terms as any other registered vessel, and the trailer usually goes on the same invoice. A jet ski is a vessel in Western Australia: it has to be registered, and the rider needs a Recreational Skipper's Ticket. If you are buying two skis for two different people, put each one on its own loan, because the registration, the security and the debt all have to sit with the same name.
Yes, though whether it is secured depends on registration. A tender no more than 3.1 metres with a motor no bigger than 5hp is exempt from registration in Western Australia, which means no HIN and nothing to secure against, so it is funded as an unsecured personal loan. Register the same hull with a bigger motor and it becomes an ordinary secured boat loan.
Usually, if they appear on the invoice at the time of purchase. Trailers, electronics, safety gear and the first year of marine cover are all routinely financed with the boat. Bought separately after settlement they are harder to add, so it is worth deciding on them before the paperwork goes in.
Older than you would think, and the answer is really about the engine rather than the hull. A well built fibreglass hull is good for decades and lenders know it, so the age policy bites on the motor. A repowered boat with an invoice for the new engine is a much stronger application than the same hull with its original motor. Ask the seller for the engine's year and hours, and get the repower invoice if there is one.
Yes. Boat engine finance is one of the packages Yes Loans arranges: you are not limited to buying a whole new vessel to take advantage of it. Whether it is secured depends on the same question as everything else here, which is what the lender can register its interest against, so tell your broker whether the hull is already registered in your name.
Yes. Various options are available when you take out a commercial marine loan, which can range from hire purchases or leases through to a chattel mortgage. The lender is reading the business rather than the household, so a charter book, a catch history or a contract does more for the file than a payslip. Speak to your accountant about the structure before the paperwork goes in.
Boat loans start from $5,000 and go up. There is no fixed ceiling we can publish, because on a larger vessel the number is set by the survey and the lender rather than by us. Our loan calculator is the quickest way to sanity check a figure, and what you can borrow comes down to your income, your existing commitments and the boat itself, since on a secured loan the lender is also lending against the security.
Not necessarily. Plenty of boat loans settle with nothing down. A deposit lowers what you borrow and widens the number of lenders willing to look at the file, which matters most on a thin credit file, a rebuild, or an unsecured purchase where the lender has nothing but you to lend against. It is worth modelling both on the estimator above.
Getting your rate here will not affect your credit score. One application through us reaches the whole panel, so you avoid the multiple enquiries that come from applying to lenders one by one.
Often, yes. Paid or unpaid defaults, a discharged bankruptcy or a thin file change the rate and sometimes the deposit rather than closing the door. The honest position is that it costs more, and your broker will tell you what it costs before you apply.
Yes, and on a private purchase in spring it is the better order to do it in. A pre-approval is a lender's conditional yes on an amount and a rate before you have chosen anything. It costs nothing, commits you to nothing, and most hold for 30 to 90 days depending on the lender.
On a secured loan, yes, and from the day of settlement. The lender holds the vessel as security so it needs the boat covered, and it will normally want the trailer on the policy too. We arrange insurance alongside the finance so it is not a separate errand at the worst possible moment.
The insurer pays out the vessel's value, which is not always the same as what is still owing on the loan. That gap is what shortfall cover exists for. Your broker will raise it with you rather than leaving you to find out afterwards.
Yes. If the rate was set at a dealer counter a few summers ago it is worth a look, particularly if your credit position has improved since. Refinancing a boat loan works the same way as refinancing a car loan.
You will need to be over 18, an Australian citizen or permanent resident, employed or self-employed, and receiving a regular income you can evidence. Beyond that the lender is assessing your income against your commitments, and on a secured loan the vessel against its own age and condition policy.