Freedomand flexibility
Freedom and flexibility to travel almost anywhere.
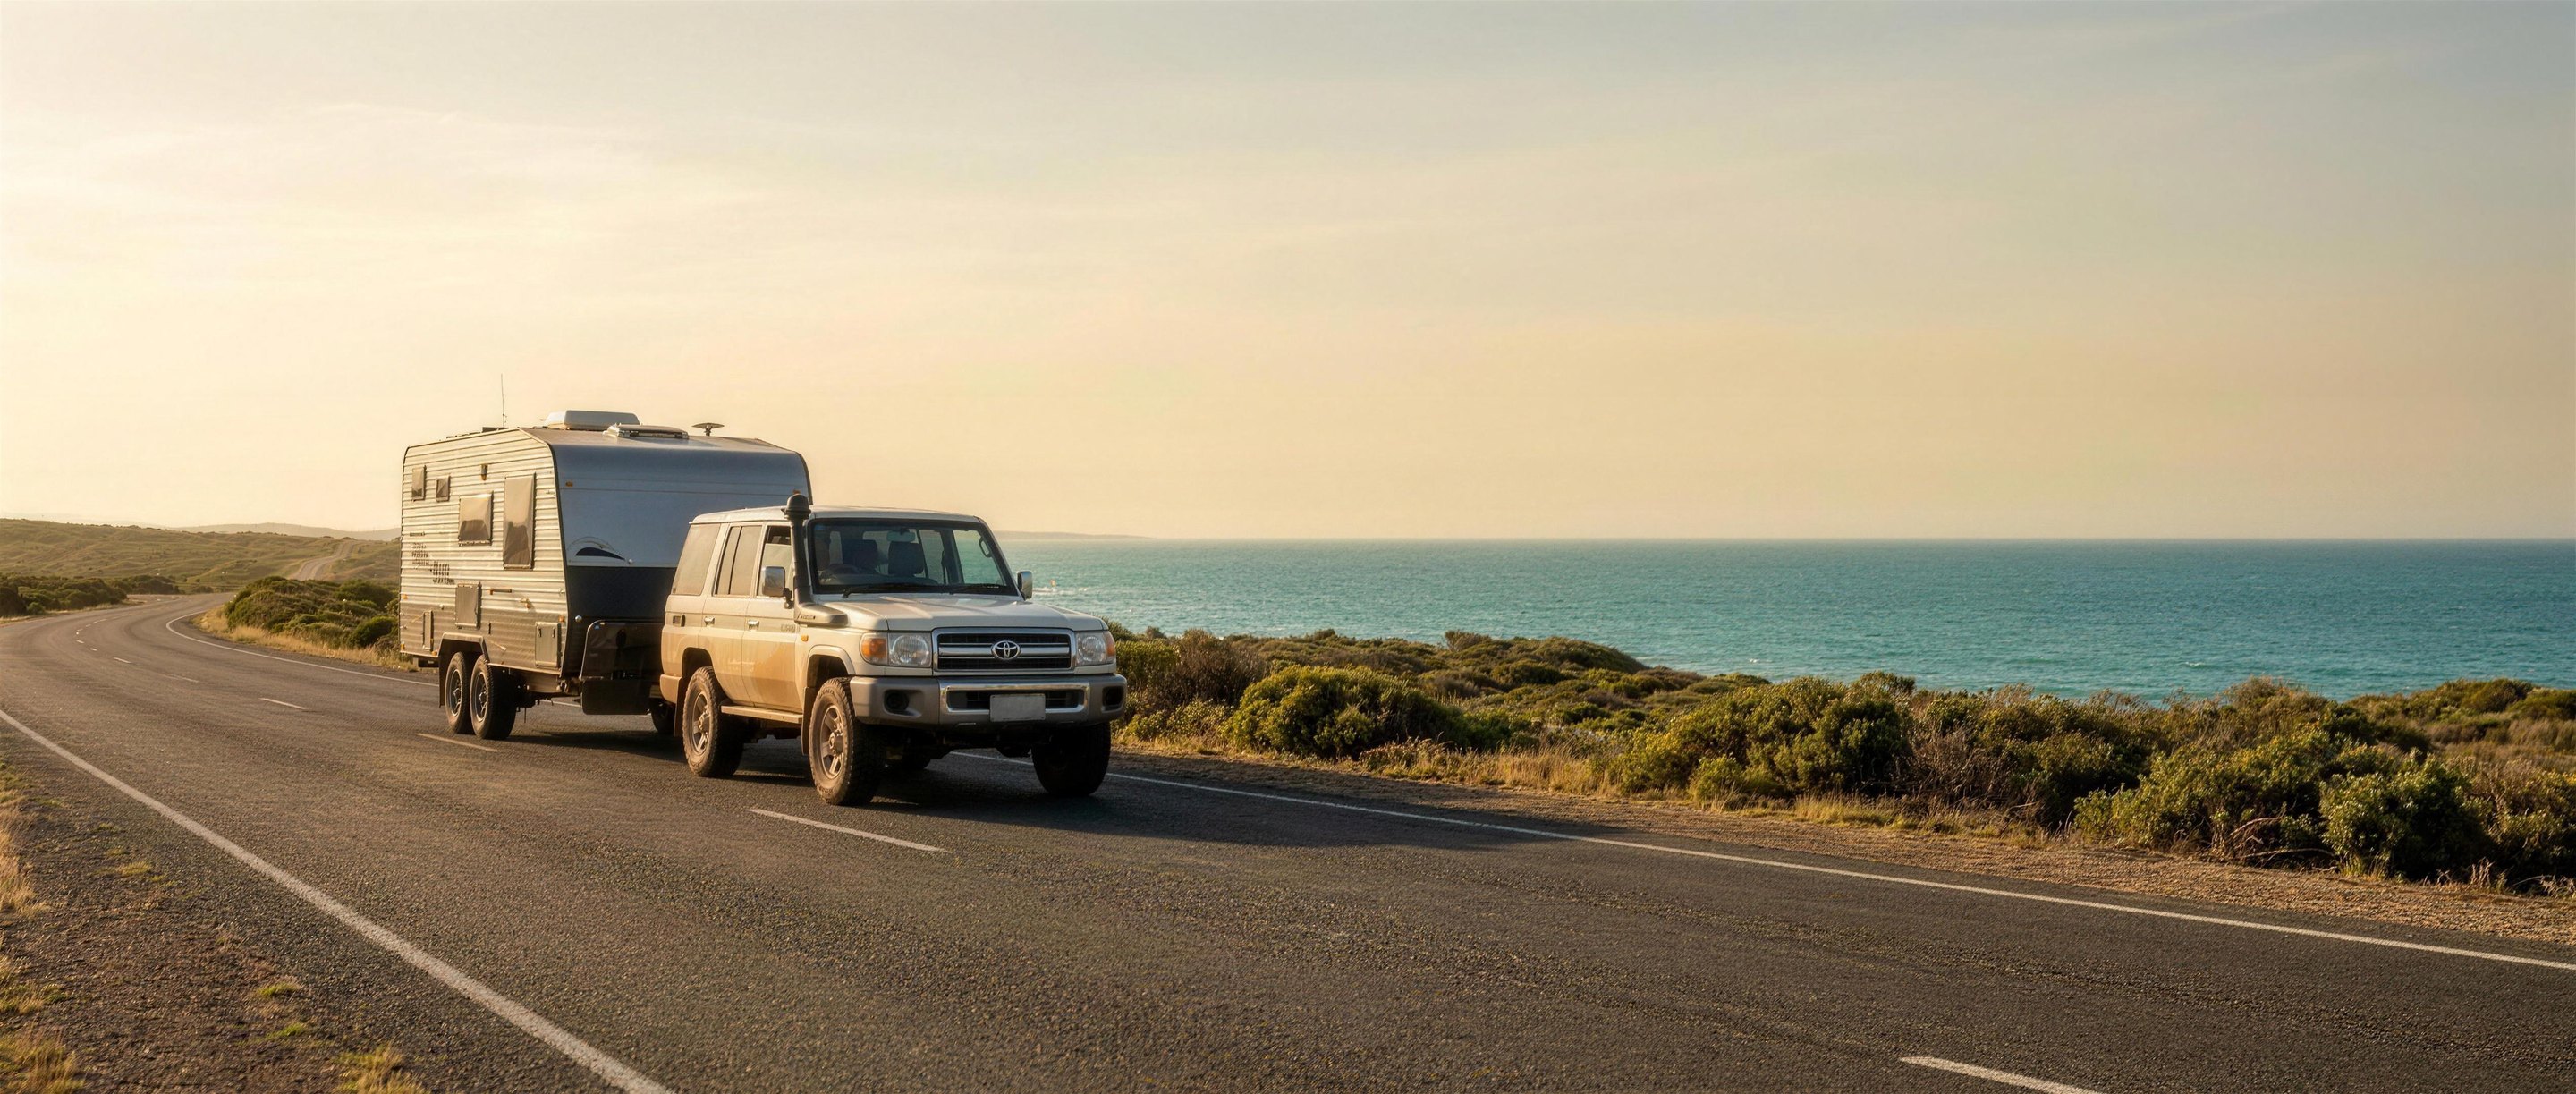
Nothing beats an adventurous getaway, and we've helped many customers make it happen with caravan loans! We have access to a range of caravan finance options, we provide an easy application process and can access competitive caravan finance rates.
Leisure loans - which include motorcycles, boats and caravans - can add significantly to your lifestyle, and where the purchase of a caravan is concerned, the benefits are plenty:
Freedom and flexibility to travel almost anywhere.
Modern caravans and motorhomes generally have excellent resale value, should your needs change further down the line.
A safe, comfortable way to enjoy the great outdoors.
Many families miss out on the chance to enjoy these benefits, believing that a caravan on finance is a luxury they can't afford. That's why you need to meet our team.
What you tow changes the budget, the term and which lenders will look at it. Choose the closest match and we will tell you how a lender sees it before you go anywhere near a dealer.
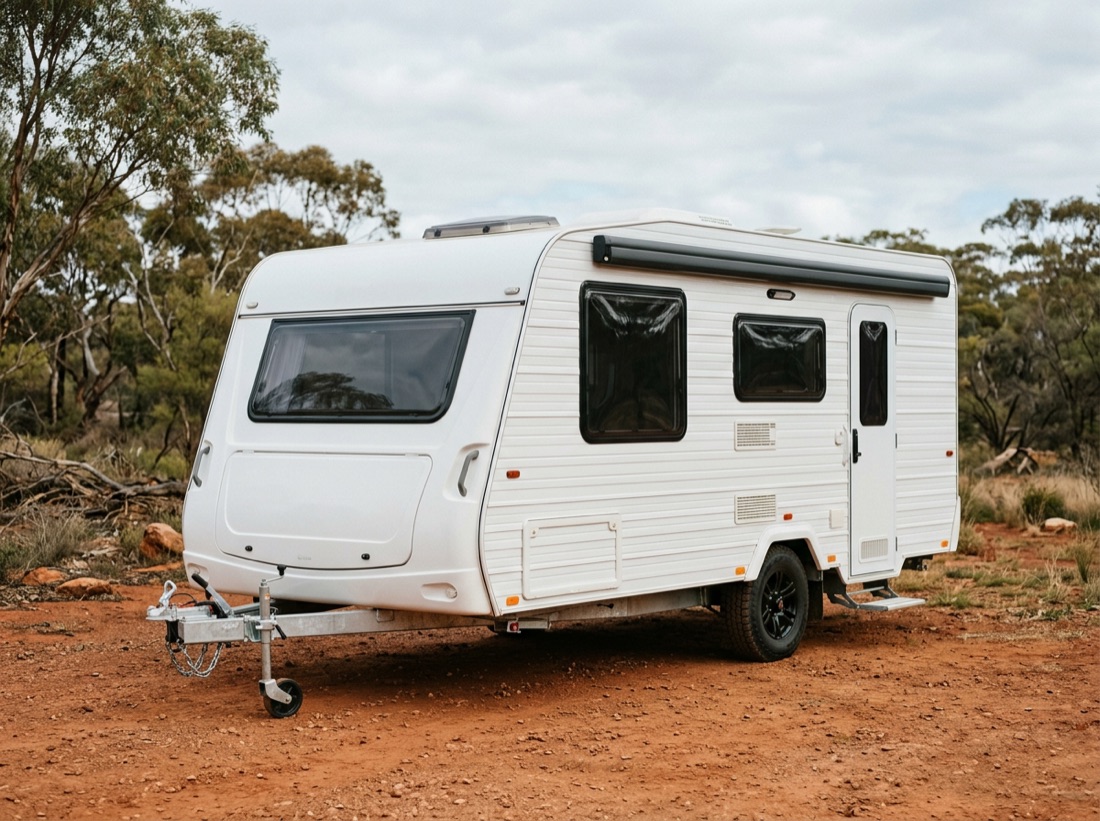
The most common leisure loan we see. Full ensuite, full kitchen, built to live in for weeks at a time. It is also the type where the tow vehicle question decides the budget.
The regular caravan option features four walls and can have between one and three axles. With decent storage capacity, this is a popular and fuss-free option for many families. If you own a smaller vehicle, a tent trailer could be a better solution, as the overall weight is a lot lower than a full caravan, yet still offers you the fun and practicality of setting up accommodation wherever you wish. Our team can also distinguish between budget-friendly caravans and more exclusive models, from Jayco to Coromal, Windsor, and Supreme.
Start with what you are looking to borrow, then move the term and the rate until the weekly figure is one you would be comfortable carrying for the length of the loan. Send that to a broker and it becomes a real quote.
We are a broker, so we do not set this. Lenders do, per file. Move it to whatever you want to test and your broker will come back with the rate a lender will actually write.
The sharp end of the panel is open to you, and a late model van is the security lenders compete hardest for. Try the lower end of the rate slider.
Anything written on the dealer invoice can be financed with the van. Anything fitted afterwards is a purchase you fund yourself.
A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees and the term in writing, from the lender, before you commit to anything.
It is the same secured leisure loan whichever way you buy. What moves is the paperwork a lender asks for, and how much of the 7 years the van's age will let you keep.
The simplest file of the three, because nobody has to form a view on what the van is worth.
Finance offered at the dealer as a weekly figure. Ask what rate produces it, what fees sit inside it and whether there is a balloon at the end, because a weekly number compares to nothing on its own.
A small step up from new, and barely that on a late model van that has clearly been looked after.
A van that will be past the lender's age limit at the end of the term you wanted.
The same secured rates apply. Buying privately is not a penalty with the right lender, and it is often where the value is.
Paying a deposit before the PPSR search has come back clear.
Most lenders work to how old the van will be when the loan finishes rather than how old it is now, commonly somewhere between 15 and 20 years. A 2012 van on a 7 year term finishes at 21, which rules out some lenders and leaves others untroubled. It is the most common reason a used caravan is declined, and it is knowable before you apply rather than after.
A caravan is a leisure asset, and a bank's single credit policy tends to treat leisure as the first thing to say no to. A panel does not work that way: somewhere on it is a lender who writes vans all week and already has room for a file like yours. Every answer below carries a condition, because the honest ones do.
Two full years of tax returns is a bank's rule, not the panel's. Several lenders will read a twelve month old ABN off your BAS and your trading account instead, which is a different set of documents rather than a longer list of them.
Paid or unpaid, a default does not end a caravan application. It narrows the panel and it moves the deposit, which on a van sized loan is the number worth planning around. Put a higher rate into the estimator above and you will see what it costs a week.
No history is not bad history. A first-time borrower is read on income stability and savings conduct instead, and a deposit does a great deal of work here.
Half the vans in this state are bought by people who work a swing, and an online lender reading base pay alone will undercount that income badly. A lender used to Western Australian rosters assesses the whole of it, allowances included.
If the van earns its keep in the business, a chattel mortgage may be the better structure. Speak to your accountant first, then bring us the answer.
If the rate was set at a dealer counter three years ago it is worth a second look. Refinancing a leisure loan works the same way as refinancing a car loan.
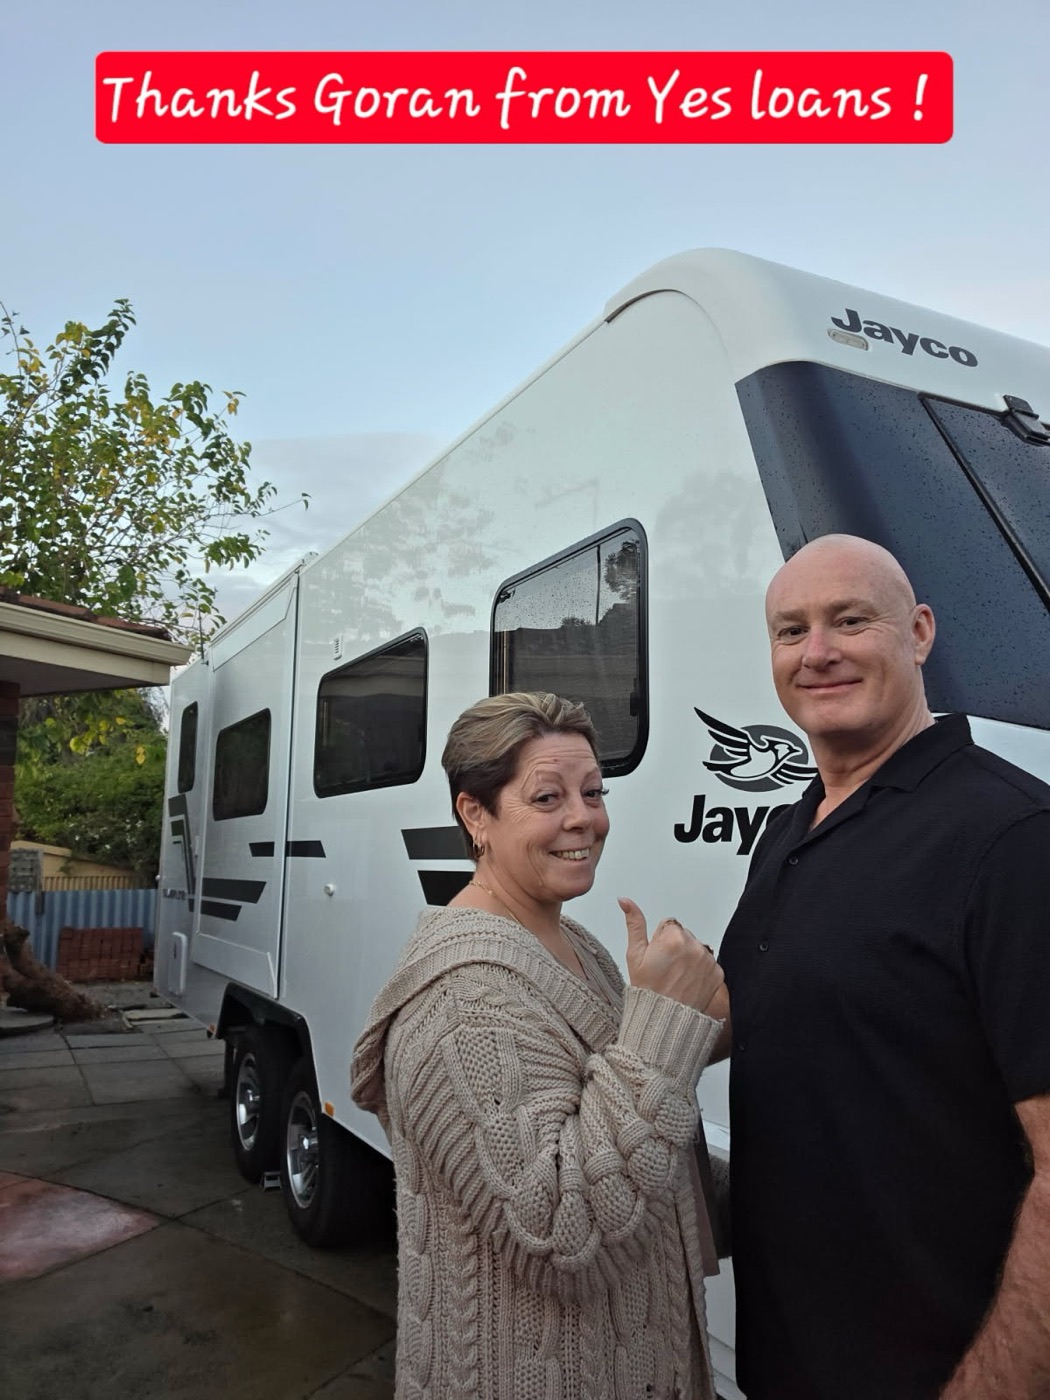
Eight-time returning customers, photographed the day they picked up their van. There are lots of happy Australians that have already taken advantage of a caravan loan thanks to our expertise in dealing with loans of this kind, our user-friendly application process, and our outstanding customer service.
Start your application Yes Loans
263 Albany Hwy, Victoria Park
 A big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
 Thanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
 I cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week
powered by Google
One of our finance brokers will be in touch to help you through the form and by expanding on any sections that you may have questions about. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.
The Perth Caravan and Camping Show fills Claremont Showground every March, and the dealer run stays open the rest of the year. Arriving at either with a pre-approval already in hand changes what you are negotiating: the price of the van, rather than the finance the dealer would rather sell you alongside it.
A lender's conditional yes on an amount, decided before you have chosen a van. It binds you to nothing, and walking away costs you neither money nor an explanation.
Between 30 and 90 days with most lenders, which covers a show weekend and the several weeks of thinking that always follow one.
Nothing, and your credit file is left unmarked. One application covers the whole panel, which is the point: applying to lenders one at a time is what leaves a trail of enquiries behind you.
Your broker is in Victoria Park, so the person reading your file knows the difference between a van that will sit at Coral Bay for a month and one doing Margaret River long weekends. Call (08) 9472 3000 or get your rate online.
A good starting point is determining what you are looking to borrow by using our caravan loan calculator. While this will give you an indication of the repayments you could expect, it is merely a guide as interest rates may vary depending on your current financial status and other credit approval factors.
We provide a free online application form where you can start the application. One of our finance brokers will be in touch to help you through the form and by expanding on any sections that you may have questions about. Our finance brokers are based in Perth.
The regular caravan option features four walls and can have between one and three axles. With decent storage capacity, this is a popular and fuss-free option for many families. If you own a smaller vehicle, a tent trailer could be a better solution, as the overall weight is a lot lower than a full caravan, yet still offers you the fun and practicality of setting up accommodation wherever you wish. Our team can also distinguish between budget-friendly caravans and more exclusive models, from Jayco to Coromal, Windsor, and Supreme.
This loan type means that the caravan or motorhome you purchase will be held as collateral by the lender as security. This provides protection for the lender should you be unable to make your payments, but the positives could include a lower interest rate compared to an unsecured loan.
Our in-depth understanding of motorhome and caravan financing means we can help to get you competitive finance rates. We have access to loans for caravans for up to 7 years.
For your convenience, we offer a simple online application process. Some of the information you will need to supply us with includes the amount you want to borrow, your personal details, employment information, income and expenses.
There are lots of happy Australians that have already taken advantage of a caravan loan thanks to our expertise in dealing with loans of this kind, our user-friendly application process, and our outstanding customer service.
Whether you have already chosen a caravan, or whether you have done little research on the topic and require advice from the start, we can help you to make caravan ownership a reality based on satisfying approval criteria with competitive interest rates and flexible payment terms.
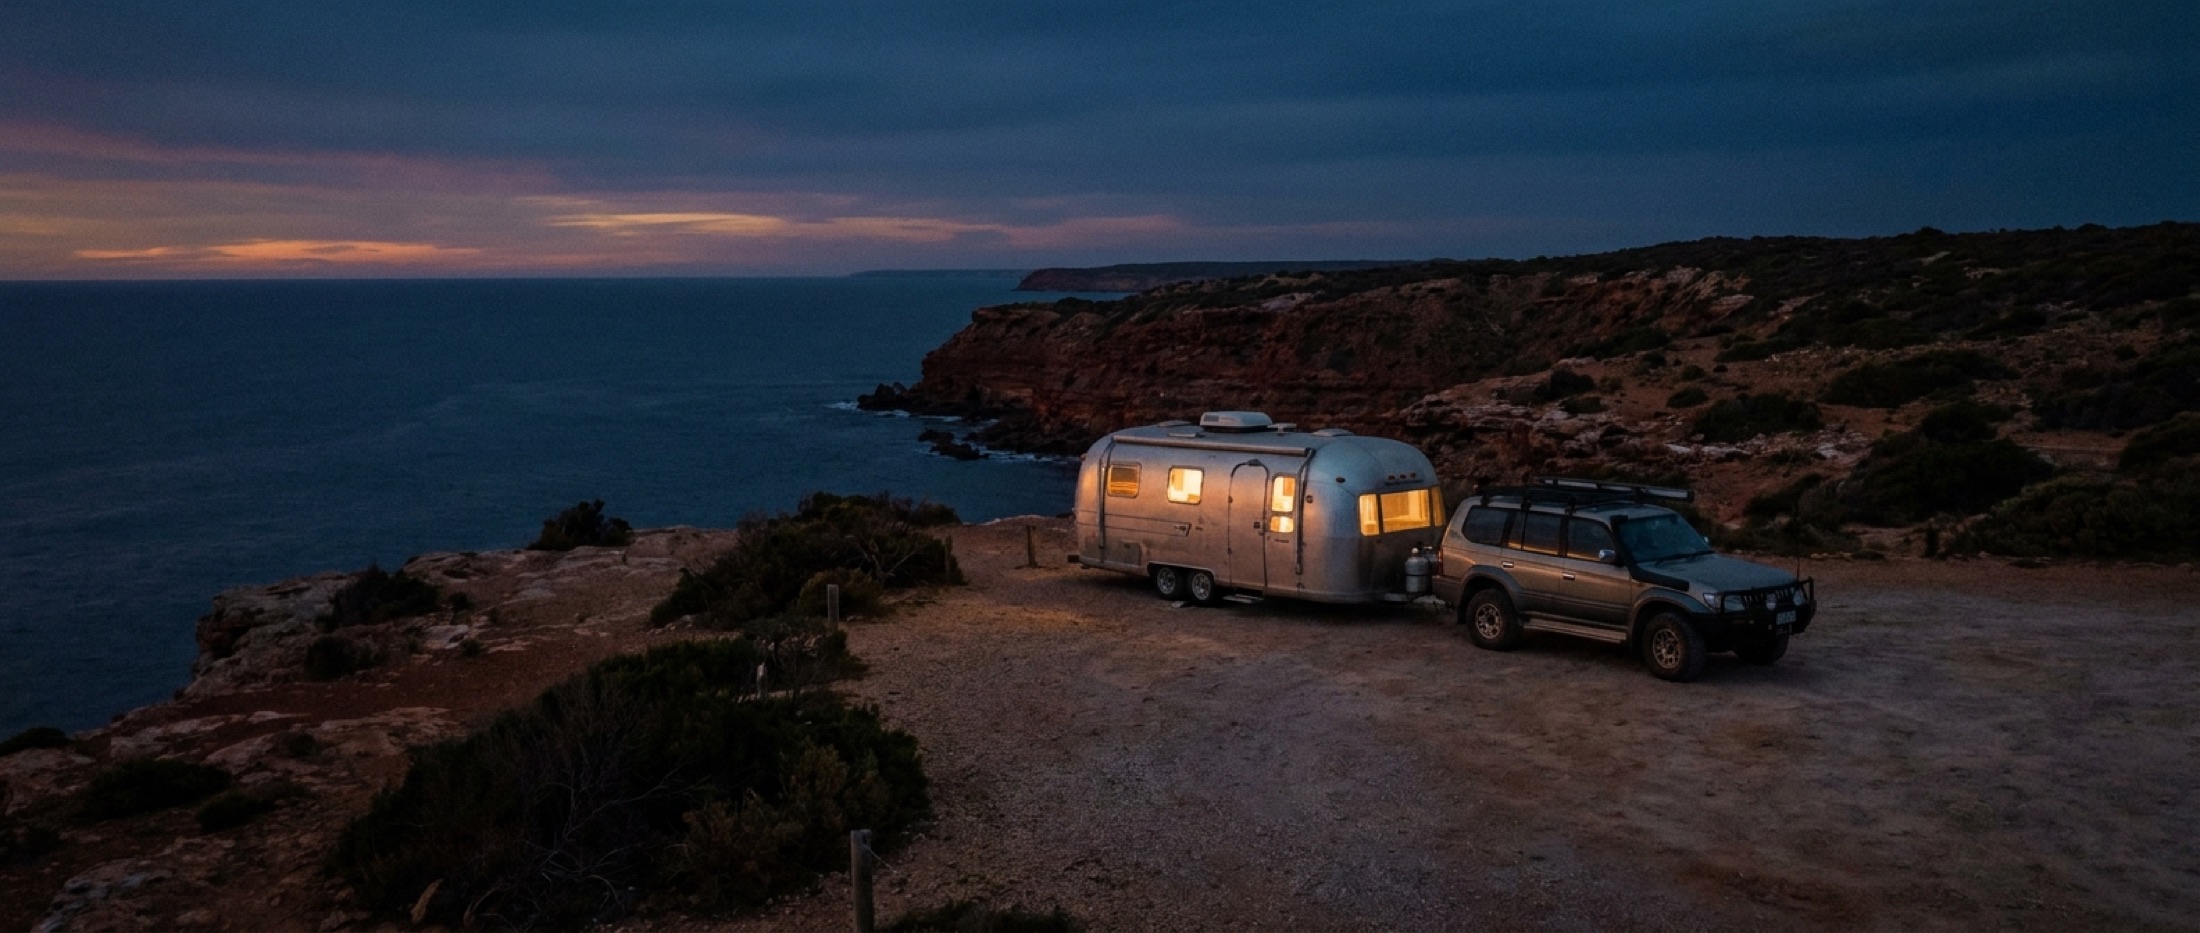
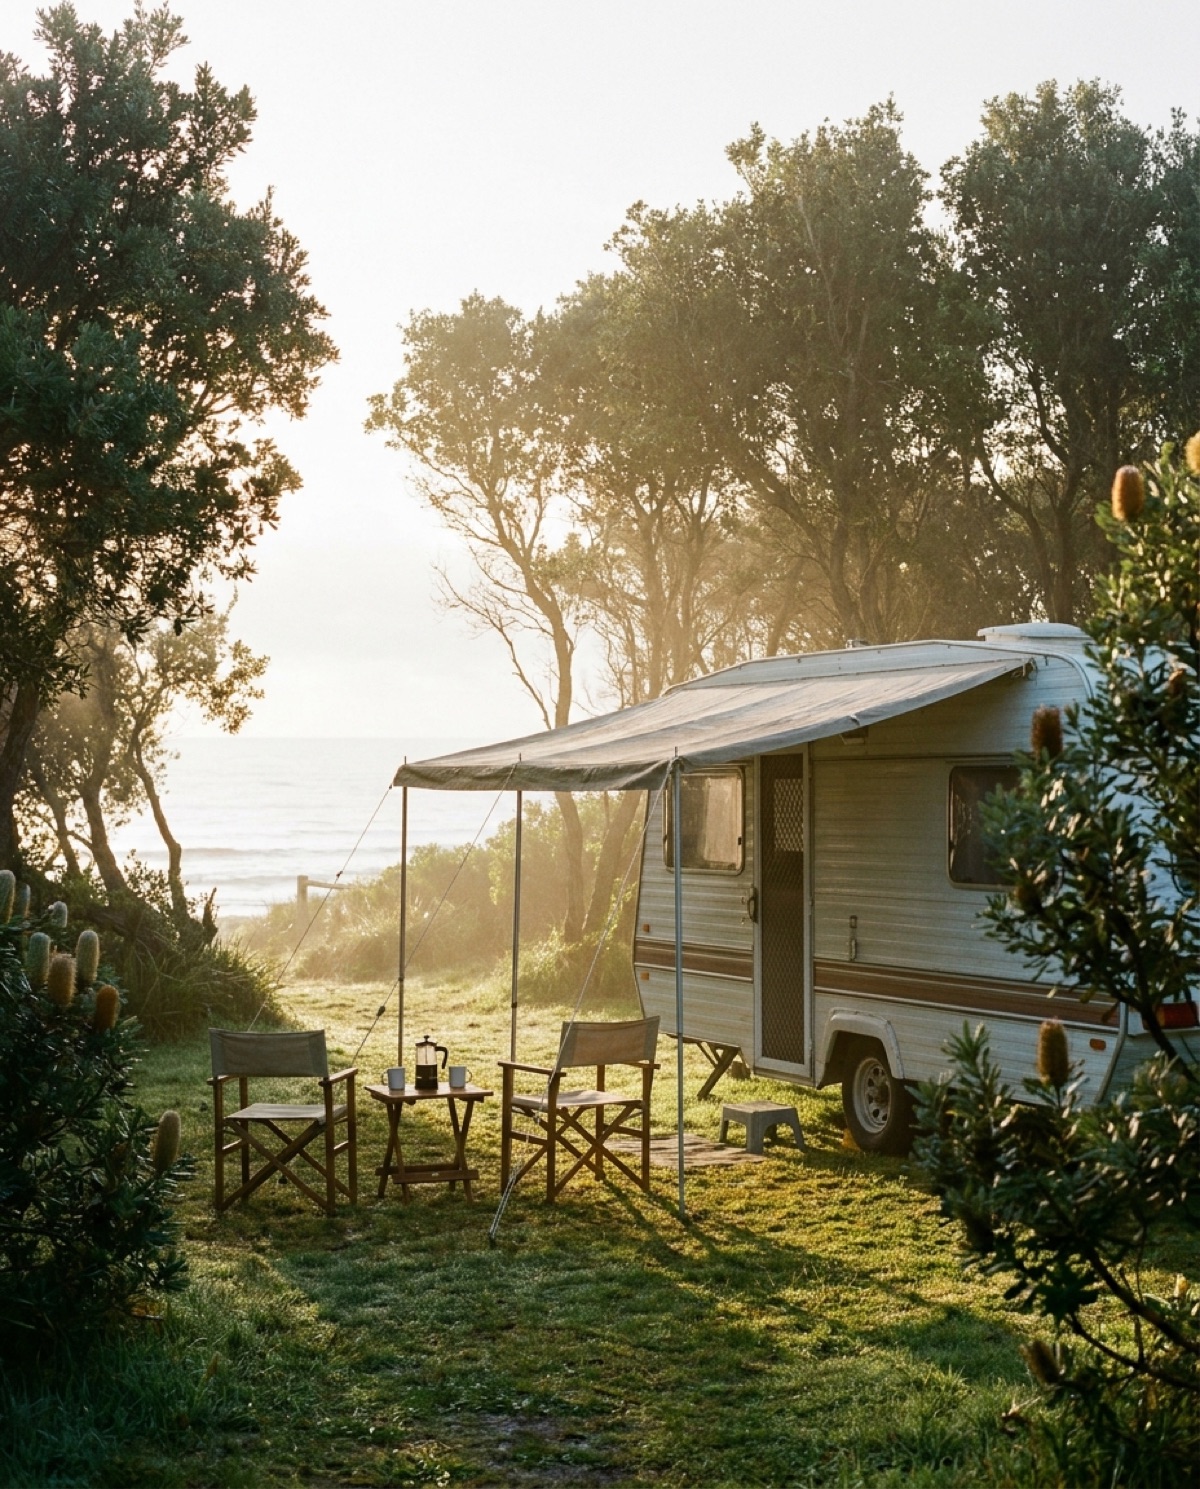
Say YES to freedom and flexibility. Say YES to Yes Loans today.
Get started by using our caravan finance calculator, apply online now or call us on +61 894 723 000 to discuss your loan and finance options.
You've probably seen the ads. An app promises to unlock a slice of your wages before payday, no interest, just
Thinking about a personal loan for a renovation, a holiday, a medical procedure, or to bring a few debts together?
If you've been searching for short term loans in Australia, you've probably noticed the results are a mixed bag.
We have access to loans for caravans for up to 7 years. A longer term lowers the repayment but increases what the loan costs you overall, so your broker will show you both before you choose.
A secured loan means the caravan or motorhome you purchase will be held as collateral by the lender as security. This provides protection for the lender should you be unable to make your payments, but the positives could include a lower interest rate compared to an unsecured loan.
Yes. Private sales are common in the caravan market and often where the better prices are. We verify the seller owns the van outright and that there is no finance owing against it, then the lender pays the seller directly on settlement.
Usually, if they appear on the invoice at the time of purchase. Accessories fitted after settlement are harder to add later, so it is worth deciding on them before the paperwork goes in.
Getting your rate here will not affect your credit score. One application through us reaches the whole panel, so you avoid the multiple enquiries that come from applying to lenders one by one.
No. Whether you have already chosen a caravan, or whether you have done little research on the topic and require advice from the start, we can help you to make caravan ownership a reality based on satisfying approval criteria with competitive interest rates and flexible payment terms.
Pop-tops, camper trailers, campervans, motorhomes, fifth wheelers and off-road hybrids are all financed as leisure assets, and so are motorcycles and boats. We also arrange car, personal, home and commercial finance.
Indicatively between $15,000 and $150,000 on a secured leisure loan. Our loan calculator is the quickest way to sanity check a figure. What you can borrow inside that range comes down to your income, your existing commitments and the van itself, since the lender is also lending against the security.
Yes, and it is the better order to do it in. A pre-approval is a lender's conditional yes on an amount and a rate before you have chosen anything. It costs nothing, commits you to nothing, and most hold for 30 to 90 days depending on the lender.
Often, yes. Paid or unpaid defaults, a discharged bankruptcy or a thin file change the rate and sometimes the deposit rather than closing the door. The honest position is that it costs more, and your broker will tell you what it costs before you apply.
Most lenders set the limit by how old the van will be when the loan ends, not how old it is today, commonly between 15 and 20 years. A 2012 van on a 7 year term finishes at 21 years old, which suits some lenders and not others.
On a secured loan, usually yes. A balloon lowers the repayment by leaving a lump sum owing at the end of the term, which you then pay out, refinance or cover by selling the van. It costs more in interest overall, so it is worth seeing both versions before you choose.
Yes. If the rate was set at a dealer counter a few years ago it is worth a look, particularly if your credit position has improved since. Refinancing a leisure loan works the same way as refinancing a car loan.
If the van is genuinely used in the business, a chattel mortgage may suit better than a consumer loan and the tax treatment differs. That is a question for your accountant first, and we will structure the finance around their answer.
For a secured loan, yes. The lender holds the van as security, so comprehensive cover has to be in place from settlement. We arrange insurance as well, so it does not have to be a separate errand.
You will need to be over 18, an Australian citizen or permanent resident, holding a current licence and receiving a regular income you can evidence. Beyond that the lender is assessing your income against your commitments, and the van against its own age and condition policy.
Budget past the repayment. Registration, comprehensive insurance, an annual service, tyres, storage if it will not fit at home, and site fees on the road all continue after the loan settles. A repayment that is comfortable on its own can stop being comfortable once those land.