Yoursfrom the day you sign
Unlike hire purchase agreements, under a chattel mortgage the borrower becomes the owner of the motor vehicle at the time that the agreement is entered into.
A chattel mortgage is a financing facility that may allow the purchaser to claim (Upfront) the GST content of the vehicle purchase if the purchaser is registered for GST. How much of it comes back, and what you hand to RevenueWA, are decided by two numbers stamped on the vehicle rather than by the price on the windscreen.
A chattel mortgage occurs where a bank or finance company provides a loan or loan facility to a business large or small, a contractor, a self-employed person, the business uses that facility to purchase an asset such as a motor vehicle or plant and equipment, predominantly for business use.
Unlike hire purchase agreements, under a chattel mortgage the borrower becomes the owner of the motor vehicle at the time that the agreement is entered into.
Chattel mortgage repayments are fixed for the term, and the interest rate is fixed for the term of the chattel mortgage agreement, so a rate rise between now and the last payment is somebody else's problem.
No GST is charged on the monthly chattel mortgage payment. Customers registered for GST may be able to claim the GST that is included in the vehicle purchase price instead, on the next Business Activity Statement rather than over the term.
A tax deduction may be available if used for business use, usually depreciation, running costs, GST and the interest content of the loan. Check out your Chattel Mortgage repayments with our loan repayment calculator.
The finance barely changes between these five. What changes is the tax treatment, the Western Australian licence duty and how long a lender will write the term for. Pick the closest match and we will tell you where your asset sits on both thresholds before you go looking at stock.
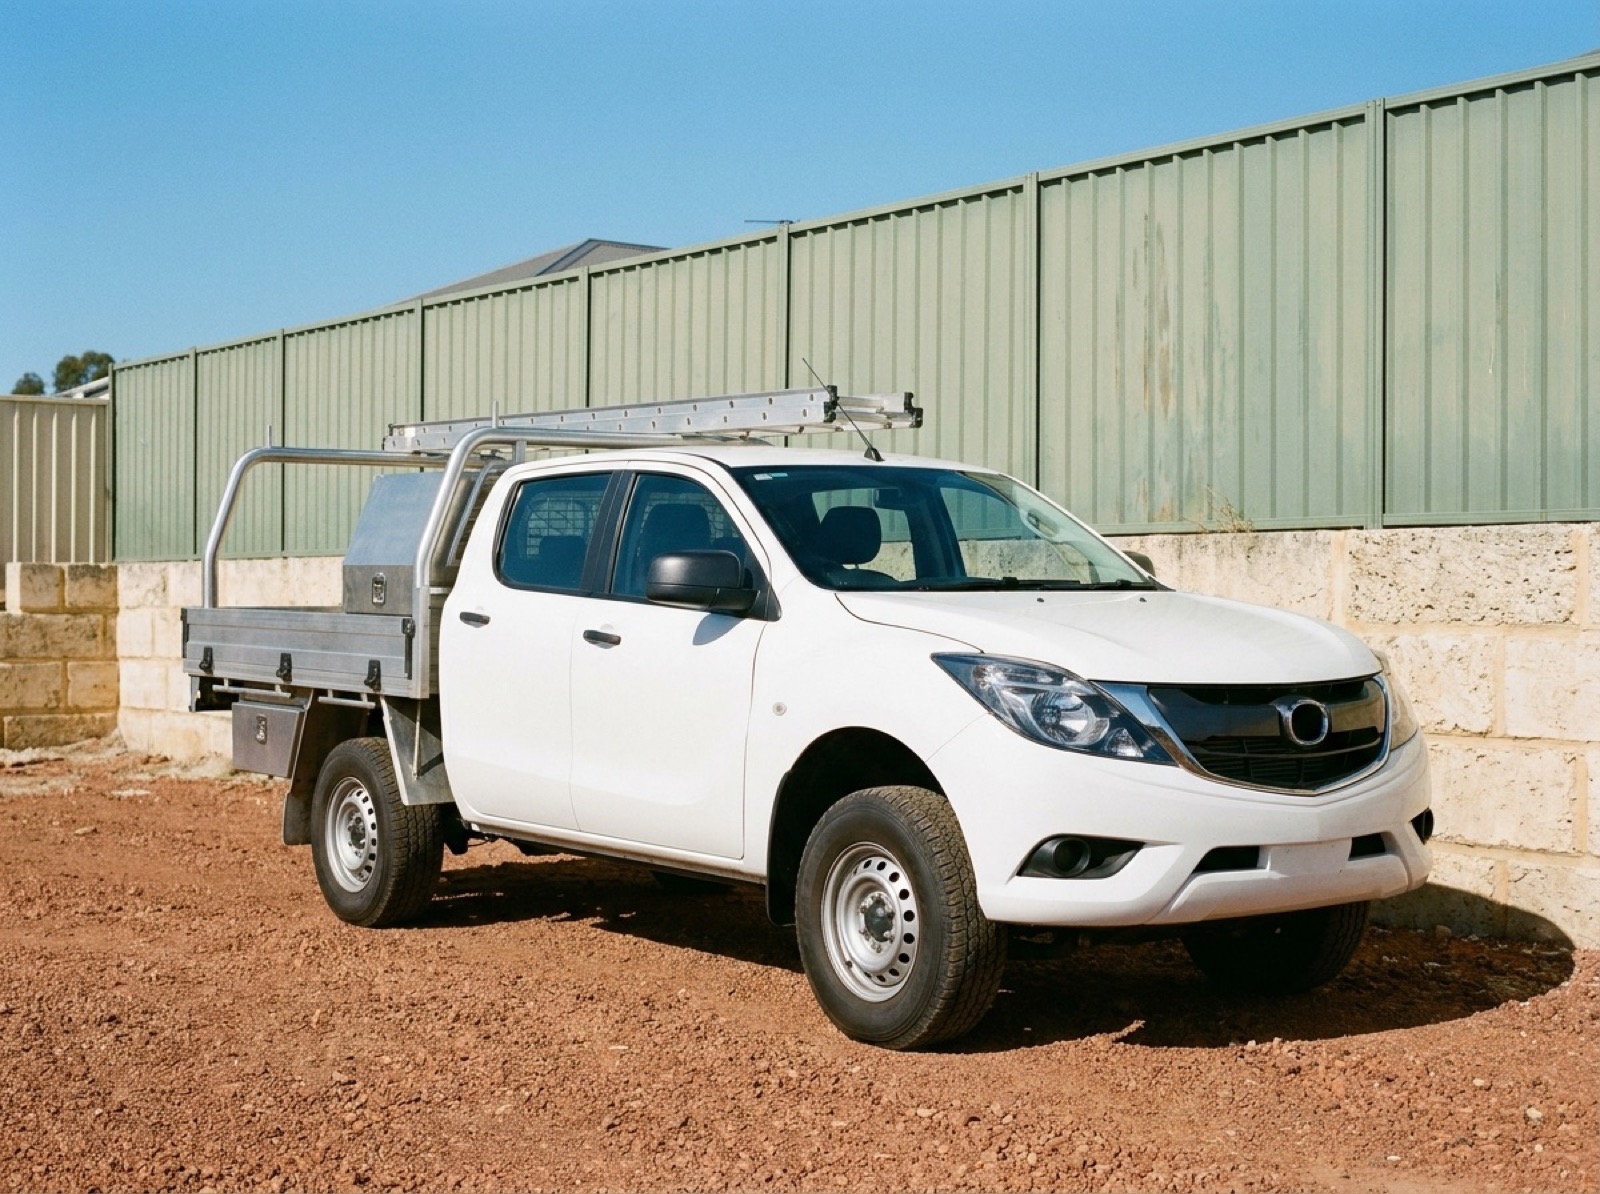
The most financed asset in Western Australia and the one where the plate matters most, because a dual-cab sits right on the line. Two utes on the same forecourt at the same money can have completely different tax outcomes, and the only way to know which is which is to read the plate before you sign the contract.
Buying more than one thing at once, or a vehicle and the gear that goes on it? Those can often sit on the same contract if they are on the same invoice at settlement, and they are far harder to add afterwards. Send us the quote and we will tell you what can go on it, or read what a truck loan and an equipment loan cover on their own pages.
Two things a business needs from a finance page and almost nobody puts on one: the weekly cost of the contract, and the GST credit at the end of it. Move the balloon and the payload switch and watch both change at once.
Business loans start from $5,000. The top of this slider is the top of the slider, not a limit: what a lender will write above it depends on the asset and on the business, not on us.
You claim the business portion only, and you have to be able to show the percentage. Keep a logbook from the first week rather than reconstructing one in July. Under half and this is the wrong product entirely.
Every repayment before it gets smaller and the last day gets bigger, and you pay interest on the balloon the whole way through. Size it against what you honestly expect the asset to be worth on that date, because if it is worth less you still owe the difference.
We are a broker, so we do not set this. Lenders do, per file, and business credit carries no comparison rate obligation, which is exactly why an advertised business rate tells you so little. Move it to whatever you want to test and your broker will come back with the rate a lender will actually write, fixed for the term.
A passenger vehicle designed to carry fewer than nine people and a load under one tonne. The car limit applies, so both the depreciation and the GST credit stop at $69,883.
A guide only, worked out from the rate you chose above and the 2026-27 ATO thresholds. Yes Loans is a finance broker and does not set interest rates, and it is not a tax agent. Your broker confirms the rate, the fees and the term in writing from the lender; your accountant confirms what you can claim.
Every road vehicle carries a manufacturer's plate, usually on the driver's door pillar. Two of the figures on it decide how much of the purchase you get back and what you hand to RevenueWA, and neither of them has anything to do with what you paid. A dealer will not raise this with you. It is the first thing we ask about.
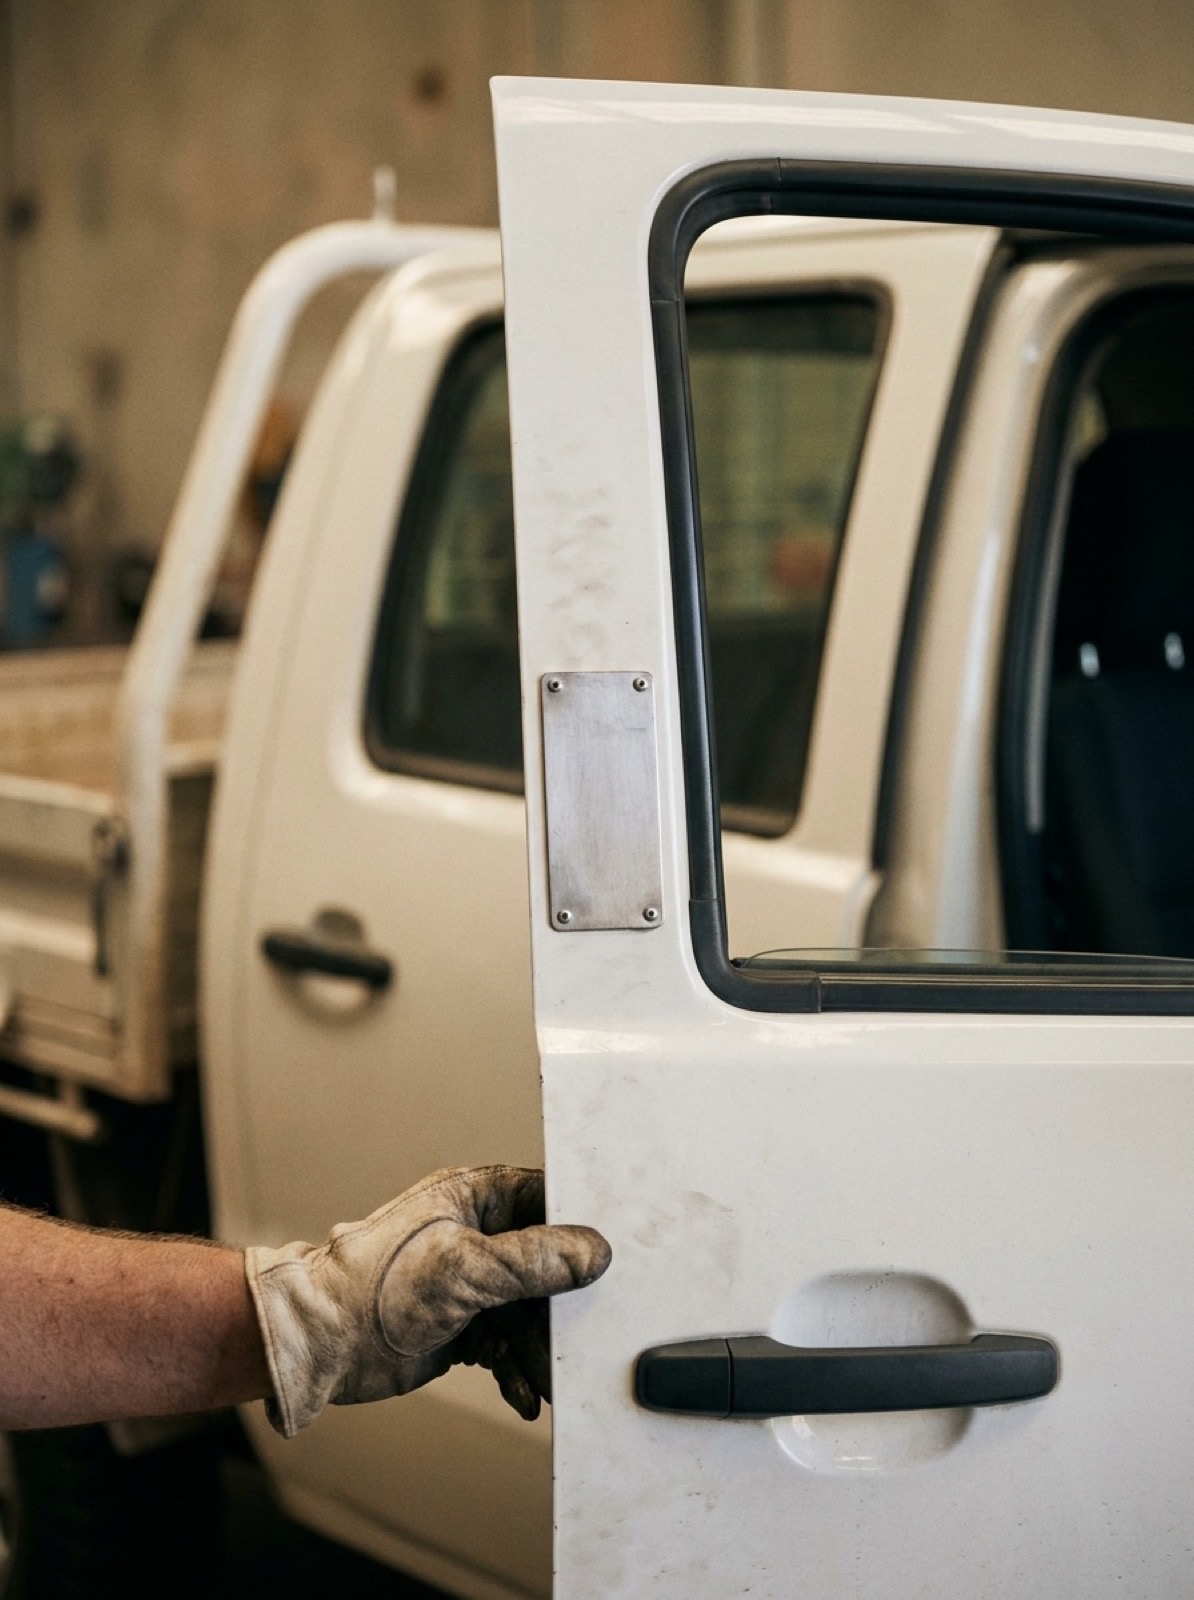
The car limit caps both the depreciation and the GST credit on a passenger vehicle. For 2026-27 it is $69,883, and the credit stops at one eleventh of it. It does not apply to a vehicle designed to carry a load of one tonne or more, or nine or more passengers, so a work ute that clears the line is not a car for this rule at all.
Western Australian vehicle licence duty runs at 6.5% of dutiable value above $50,000 for anything of 4.5 tonnes gross mass or less. Over 4.5 tonnes it drops to 3% and is capped at $12,000, which is why duty on a prime mover is a smaller number than duty on a luxury car.
Specifications change between model years, between variants and between build dates, and a dealer's website is not the authority on any of them. The plate on the vehicle you are actually buying is. Photograph it before you sign the order, send it to us with the quote, and we will tell you which side of both lines it sits on while you can still change your mind.
Three ways a business can finance the same asset. Only one of them is ours, and the card next to it concedes an advantage we cannot match. What separates them is not the rate at all.
You agree to buy it, you pay for it in instalments, and you do not own it until the last one clears.
Ask what hire purchase does for your business that a chattel mortgage does not. There are real answers for some structures and some assets, but they are specific ones, and being what a particular lender happens to offer is not one of them.
You rent it. The financier owns it throughout, and at the end you hand it back, pay a residual or start again.
The honest exception on this page. Because you claim on each payment, lease GST credits are not capped at one eleventh of the car limit the way a purchase is. On a passenger car well above $69,883 that can be worth more than owning it from day one. You own nothing at the end. Ask your accountant to run both before you decide.
You own it from the moment the agreement is signed. The lender registers a security interest over it and removes it when you finish.
A broker who recommends this before asking what the asset is and how much of the use is private. If the answers are a family SUV and most of it, the honest recommendation is an ordinary car loan, and we would rather write you one of those than a business contract you should not be signing.
Which of these three is right depends on how your business accounts for GST, what the asset is, how long you intend to keep it and what your balance sheet needs to look like. A broker can tell you who will lend and on what terms. Your accountant tells you which structure to ask for. Get that answer first, then bring it to us, and if you have not got an accountant yet that is the call to make before this one.
A bank runs one commercial credit policy and your business either fits it or it does not. A broker runs a panel, which is a different job: finding the lender whose policy already has room for your situation. Every answer below has a condition attached, because the honest ones do.
Possible, and it narrows the panel rather than closing it. A new ABN behind an established trade history is a different file from a new ABN behind nothing, so bring whatever shows the work was already happening: contracts, invoices, a previous employer, a licence.
Yes, we have low doc loans available to self-employed and contractors that have an ABN number. Under $150,000 a signed declaration of turnover often does the work two years of prepared financials would otherwise have to. Fewer documents means fewer lenders, which is a trade rather than a problem.
It moves the rate and sometimes the deposit, and it does not end the conversation. Push the rate slider up in the estimator and you will see what a bruised file actually costs a week, before anybody runs a credit check on you.
A bankruptcy in your past doesn't necessarily prevent you from getting a small business loan. What matters is where it sits on the timeline and what you have done since. Tell us at the first call rather than at the credit check.
Ordinary, and the group this product was built for. Companies, trusts, sole traders, partnerships and ABN holders all use it. What the lender is assessing is the business use, not the size of the business.
Yes, and it is the one where the paperwork earns its keep. The vehicle needs a PPSR search against its VIN before settlement, the seller has to be paid in a way the lender will accept, and the transfer has to happen properly. There is a right order to do those in, and the Yes Loans car buyer guide walks through it.
Common in Western Australia and handled badly by a lot of online lenders. A lender who understands shutdowns and rosters reads the whole contract income rather than the base, which on a FIFO file is frequently the difference between a yes and a no.
Before a chattel mortgage settles you sign a declaration that the asset is wholly or predominantly for business use. That signature is not a formality. It is the thing that takes the contract outside the National Credit Code, and everything people like about this product, along with everything they should be careful of, follows from it.
A business purpose declaration: a statement that the credit is wholly or predominantly for business or investment purposes. The lender relies on it. Without one, a financier has to establish the purpose itself, which is why every one of them asks.
The asset is held as security, so the lender's risk falls and the pricing follows it. Assessment is quicker, more lenders will look at it, and structures a consumer contract cannot offer, a balloon among them, are on the table.
Consumer credit protections do not apply to it. There is no comparison rate obligation on business credit, which is exactly why comparing business finance on an advertised rate tells you close to nothing, and why a broker with a panel is worth more here than on a consumer loan.
If a loan is written as business credit when it was really personal, the characterisation can be challenged and the financier can be made to answer for it. Nobody wins that argument comfortably. Sign it because it is true, not because the rate looked better on that side of the line.
This is the point on the page where a broker earns the fee. A chattel mortgage on a vehicle that is mostly doing the school run is the wrong contract, and putting you in it would cost you the protections a consumer car loan gives you. Tell us how the vehicle is actually going to be used and we will tell you which product you are entitled to, even when it is the one with the smaller commission.
 Yes Loans
263 Albany Hwy, Victoria Park
 A big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
 Thanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
 I cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week
powered by Google
A Yes Loans broker will take you through the application process and expand on any part of the form you have questions about. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.
The income year you can claim a depreciating asset in depends on when it was purchased and when it was first used or installed ready for use. Order a truck in June with a twelve week build slot and the deduction belongs to the following year, whatever the invoice is dated. Knowing your number before you go looking is what lets you choose stock that can actually be delivered in time.
A lender's conditional yes on an amount, given before you have committed to a particular vehicle. It commits you to nothing and you can still walk away from the whole idea.
Yes Loans quotes are valid for 30 days, and if you receive pre-approval on your loan it is valid for 30 days as well. That is usually long enough to cover a dealer's delivery window and no longer than you want it to be.
Nothing, and it leaves no mark. One application reaches the whole commercial panel, so you are not collecting a credit enquiry from every lender you ask, which on a business file matters more than most people realise.
Our head office is at 263 Albany Highway, Victoria Park, so the person reading your file is in the same city as the dealer you are buying from. Call (08) 9472 3000 or get your rate online.
A chattel mortgage occurs where a bank or finance company provides a loan or loan facility to a business large or small, a contractor, a self-employed person, the business uses that facility to purchase an asset such as a motor vehicle or plant and equipment, predominantly for business use.
Unlike hire purchase agreements, under a chattel mortgage the borrower becomes the owner of the motor vehicle at the time that the agreement is entered into. Security for this form of loan is a mortgage or security over the goods purchased.
Under a chattel mortgage the lender funds the purchase of the vehicle. The customer takes ownership of the motor vehicle at the time of purchase. The lender or finance company takes a mortgage or security over goods as security for the loan. Once the contract is completed, the mortgage is removed giving the customer clear title to the motor vehicle.
Check out your Chattel Mortgage repayments with our loan repayment calculator.
A chattel mortgage suits someone who is going to use a motor vehicle predominately for business use, therefore this car financing product is used by companies, trusts, sole traders, partnerships and ABN holders. To find out if this option is right for you, call our team on +61 894 723 000.
A cash basis taxpayer for GST purposes may be entitled to claim all of the GST input tax credit up to the luxury car tax threshold or depreciation limit in relation to an acquisition using the chattel mortgage product at the commencement of the arrangement.
The monthly repayment or balloon amount is not subject to GST. Cash basis taxpayers still retain their rights to claim depreciation and interest on the motor vehicle acquired under a chattel mortgage facility. Please confirm that this type of facility is appropriate and seek independent financial advice.
A Chattel Mortgage Calculator provides you with a guide as to what your repayments might be. At Yes Loans, we are committed to providing you with the most competitive rates available. Click here to use our repayment calculator here.
To find out how our Chattel mortgage products can help you, contact us here online or by calling +61 894 723 000.
To find out how our Chattel mortgage products can help you, contact us here online or by calling +61 894 723 000.
Bring us the vehicle you are looking at and we will tell you which side of the one tonne line it sits on before you sign anything. Apply now and one application reaches the whole panel, or call +61 894 723 000 and talk it through with a broker in Victoria Park first.
You've probably seen the ads. An app promises to unlock a slice of your wages before payday, no interest, just
Thinking about a personal loan for a renovation, a holiday, a medical procedure, or to bring a few debts together?
If you've been searching for short term loans in Australia, you've probably noticed the results are a mixed bag.
It is a loan to a business to buy an asset, where the asset itself is the security. You own it from the day you sign, the lender registers a mortgage over it, and when you finish paying, that registration is removed and the title is clear. Chattel is just an old word for a moveable possession.
Yes. This is business credit, so there has to be a business. Companies, trusts, sole traders, partnerships and ABN holders all use it. If you do not have an ABN, the product you want is a consumer car loan and we arrange those too.
The asset has to be predominantly for business use, which in practice means more than half. That is the test for whether the product is available to you at all. Separately, how much you can claim is based on your actual business use percentage, and you have to be able to show it, so keep the records from the first week rather than reconstructing them in July.
The car limit is the highest value the ATO lets you use to work out depreciation on a car. For 2026-27 it is $69,883. It also caps the GST credit on a car above it at one eleventh of the limit, which is $6,353. Pay more than the limit for a car and the difference is not deductible under any other rule.
The car limit applies to passenger vehicles designed to carry fewer than nine people and a load under one tonne. Clear either bar and it does not apply, so the whole cost depreciates and the GST credit is not capped. That is why two dual-cab utes at the same price can produce very different tax outcomes.
Payload is the gross vehicle mass minus the basic kerb weight, and both are the manufacturer's figures on the compliance plate. Basic kerb weight is the vehicle with a full tank, oil, coolant, the spare, the tools and any factory-fitted options. It does not include passengers, goods or accessories.
Not the plate figure, which is the manufacturer's and is what the tax rule reads. Accessories fitted afterwards change what you can legally carry, not what the vehicle was designed to carry, so they will not push a marginal vehicle over the line. Check the plate on the vehicle you are actually buying rather than a specification sheet for the model.
They are two separate tests worded differently. Depreciation uses the passenger and payload test above. The GST exception is for a commercial vehicle not designed for the principal purpose of carrying passengers. In practice a one tonne dual-cab usually clears both, but your accountant applies them to your vehicle, not a web page to a category.
Because you own the asset from day one, a GST-registered business generally claims the credit on the purchase in the Business Activity Statement for the relevant period, rather than a slice at a time over the term. That is the single biggest practical difference between this and a lease.
No GST is charged on the monthly chattel mortgage payment, and the monthly repayment or balloon amount is not subject to GST. The GST sat in the purchase price and you have already dealt with it.
LCT is charged at 33% on the amount above the threshold, and for 2026-27 the thresholds are $91,661 for fuel-efficient vehicles and $80,809 for everything else. You cannot claim a GST credit for luxury car tax you have paid, no matter how much of the use is business. It is a real cost with no offset.
For a vehicle of 4.5 tonnes gross mass or less it is 2.75% of dutiable value up to $25,000, a sliding rate between there and $50,000, and 6.5% above that. Over 4.5 tonnes it is 3% capped at $12,000. RevenueWA publishes a calculator, and it is worth two minutes before you commit to a model.
Usually, if they are on the invoice at settlement. That is the general rule for everything on this page: accessories, fit-out, delivery and the on-roads are far easier to include in the contract than to add to it afterwards. Decide what is in before the dealer writes the order.
A balloon is a lump sum left owing at the end of the term. It lowers every repayment before it and raises what you owe on the last day, and you pay interest on it the whole way through, so it costs more overall. Use the estimator above to see both effects at once, and size it against what you honestly think the asset will be worth on that date.
You still owe the balloon. You can pay it, refinance it into a new term, or sell the asset and cover the shortfall from your own money. This is the risk nobody enjoys talking about and the reason a balloon set to make the weekly number look good is a decision you make once and live with for years.
Chattel mortgage terms range from 1 to 7 years, and Yes Loans publishes 7 years as the outside of that on its own FAQ hub. The right term is the working life of the asset and the length of the work that pays for it, not the longest one available.
Our business loans start from $5,000. There is no published maximum, because what a lender will write depends on the asset and on the business rather than on a number we could print here.
Often no. A hundred per cent of the purchase price can frequently be financed, which is the point for a business that would rather keep its working capital. Putting some in reduces the lender's risk and can be the difference between an approval and a decline on a marginal file, so it is worth asking what it would do for yours.
The interest rate is fixed for the term of the chattel mortgage agreement and the repayments are fixed with it. What the rate itself is depends on the asset, the term, the business and which lender writes it, and Yes Loans is a broker rather than a lender, so we do not set it and will not quote one on a web page.
Yes. It is a loan condition of all the lenders we deal with that the vehicle being financed is comprehensively insured. Worth thinking about shortfall cover as well on anything with a balloon, because a comprehensive policy pays market value and the loan does not care what market value is.
The Personal Property Securities Register is the national register of security interests in things that are not land. The lender records its interest against the vehicle's VIN or the machine's serial number, which is what protects it if you default and what a future buyer searches to check nothing is owing. It is removed when you finish paying.
Generally yes, and what it costs depends on the contract, because business credit is not covered by the consumer rules on early payout. Ask what the payout terms are before you sign, particularly if you upgrade equipment on a cycle, and we will read the schedule with you.
For the structure, yes, and we will say so on the first call. Whether a chattel mortgage, a lease or hire purchase suits your accounts is a tax question. Which lender will write it, on what term and at what price is ours. The two conversations belong in that order, and Yes Loans is not a tax agent.