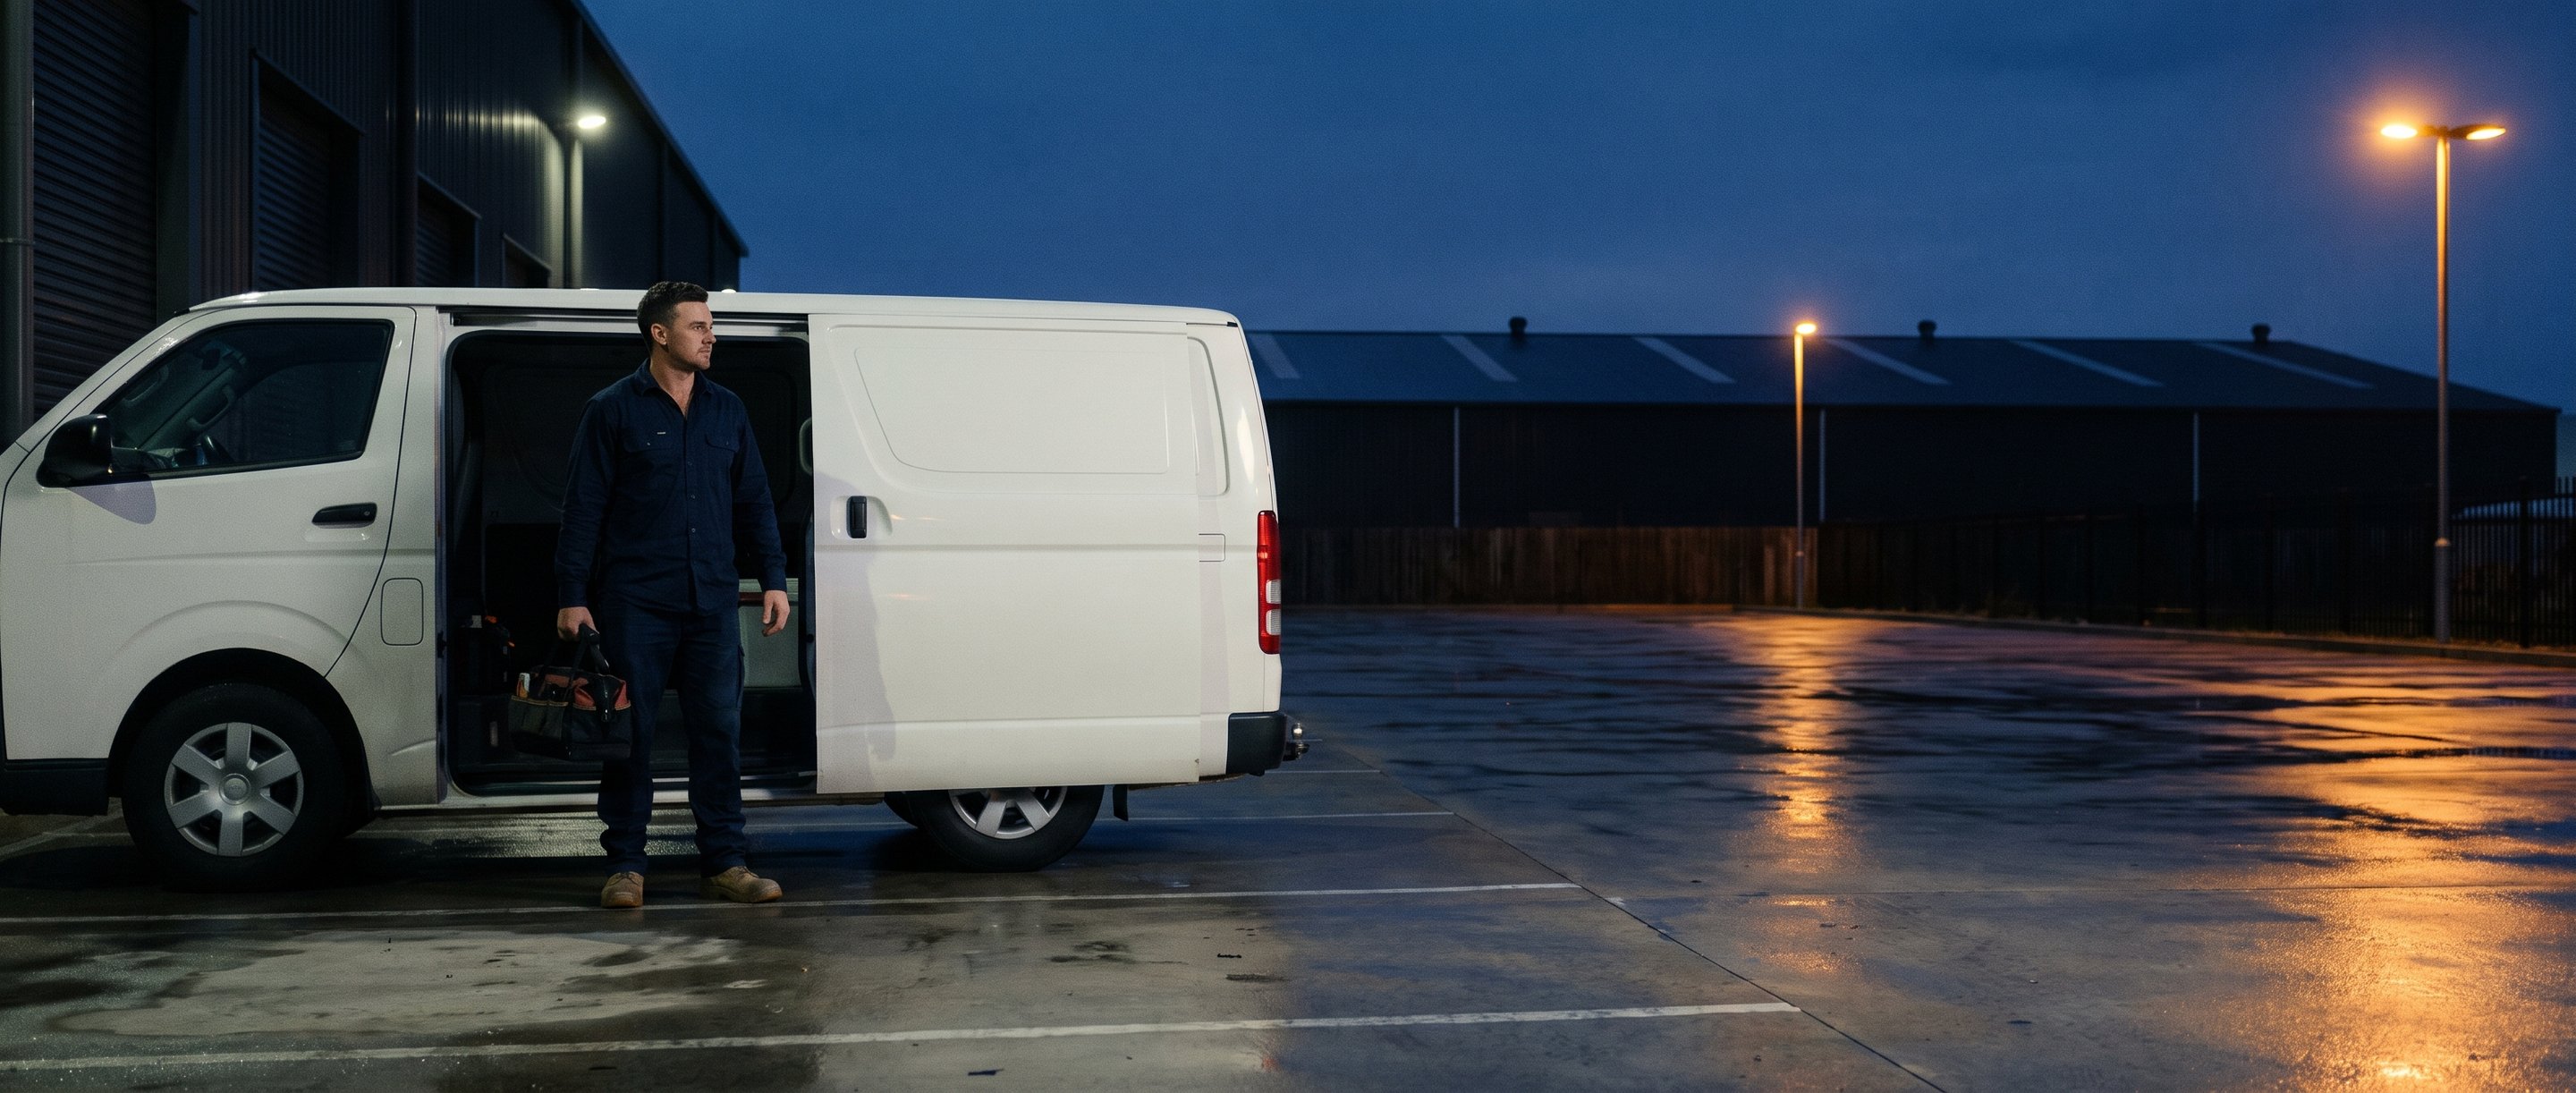
A tradesman standing at the open rear door of a work van on wet concrete outside a small light industrial unit at dusk
Business finance, Perth brokers, Australia wide

Commercial LoansThe company borrows. Somebody guarantees. Know which one you are before you sign.

Look no further than Yes Loans to help with all your business loan needs. We are based in Perth and service Australia-wide, and we made the choice to provide finance to all businesses including startups and business buyouts.

4.8 from 281 reviewsFrom $5,000, terms to seven yearsStartups and business buyouts included

Get your personalised rate

"*" indicates required fields
QuoteGetting your rate here will not affect your credit score

Yes Loans offers fast, flexible Commercial Loans that meet your every need

As the leaders in the field, Yes Loans is proud to offer small- and medium-sized business owners flexible, varied options for business loans that fit their needs and pockets.

A navy stack of banknotes with a red upward arrow in front of it

From $5,000,and up from there

Finding a good source of money is an ideal step in beginning a new business. Acquiring a commercial loan from a bank is one way to finance your venture and is especially great for startup owners. But as you most likely know by now, getting a commercial loan from a bank isn't usually easy for small businesses. Options can start as low as $5,000 and can scale upwards depending on your needs.

A navy hourglass with red sand falling through it

Terms ofup to seven years

We want our customers to have the choice in selecting the right repayment scheme for their situation. It is our interest to reduce pressure on your part so you can fund the business venture that you've always wanted. This is why we can extend the terms of a commercial loan up to seven years to accommodate your budget.

A navy circular gauge with a single red needle sweeping upward

Fast approval times,without delay

Many financial institutions nowadays perform numerous background checks and other verifications that can take up a lot of time for people in need. What makes us different than others is that we're willing to give you the opportunity to get funding for your business right away. You can even apply for a loan from the comfort of your home and get approved in just a few days!

And a brokerwho has read the policy

Our hands-on, experienced finance brokers are highly-trained in commercial and business loans and will be able to offer you a finance package especially for your unique needs. On business credit that matters more than it does anywhere else on this site, because there is no comparison rate to fall back on and far less of the paperwork is standardised. That's why you'll be talking to one of these eight.

Vehicles, equipment, cash flow, growth

What is the money actually for?

Commercial loan is four different products depending on the answer, and picking the wrong one is the most expensive mistake on this page. Three of the four have a page of their own that goes deeper than a hub can.

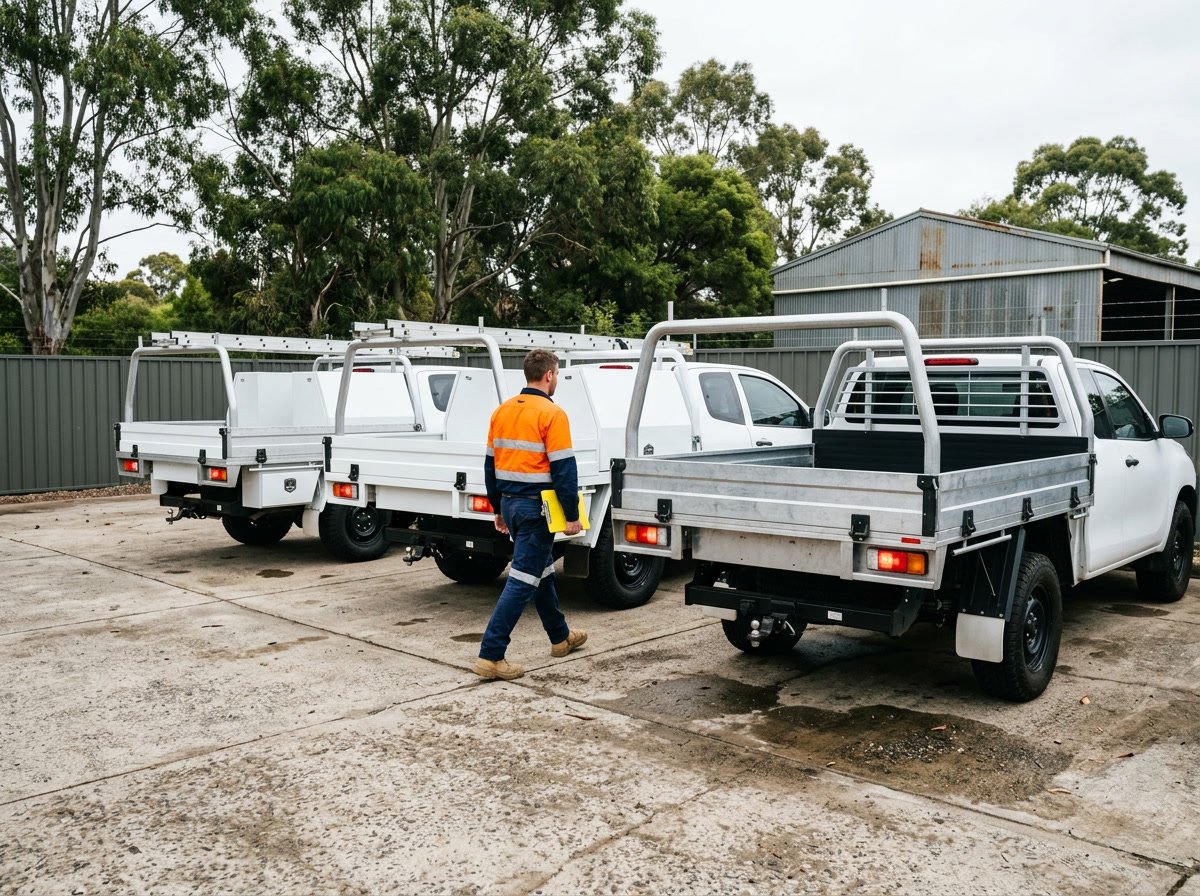
Three white work utes and a van parked on the concrete hardstand of a small business yard, ladder racks fitted

Company cars, utes, trucks and fleet

Are you looking to finance certain types of vehicles for your business? If you are, then you've come to the right place. At Yes Loans, we offer a variety of choices when it comes to funding company vehicles such as trucks, cars and the like.

How it is usually structuredUsually a chattel mortgage rather than a general business loan. The business owns the vehicle from day one and the lender registers its interest against it, which is what makes this the cheapest money on this page.
What sits behind itThe vehicle itself, which is the whole point. Because there is a real asset behind it, this is the one kind of commercial borrowing where a lender is least likely to need anything else from you.
Watch forBuying the vehicle on a general business loan when it could have been financed against the vehicle. It is the same purchase and it is not the same deal.
Business loan calculator

What would it cost, and what does it have to earn?

The amount and the term are the client's own published envelope: from $5,000, and terms of up to seven years. The rate is yours to set, because Yes Loans is a broker and does not price the file.

How much the business needs$60,000
$5,000$500,000

Options can start as low as $5,000 and can scale upwards depending on your needs. The floor is the client's own; the top of this slider is only as far as the tool goes, not a limit on what can be arranged.

Over how long4 years
1 year7 years

The right term is usually the working life of whatever the money bought, rather than the longest one available. Financing a three year asset over seven means paying for it long after it has stopped earning.

Interest rate to test11.00% p.a.
5%25%

We are a broker, so we do not set this and neither does any comparison table. Business credit carries no comparison rate obligation, so an advertised business rate tells you even less than a consumer one does. Move it to whatever you want to test and your broker will come back with what a lender will actually write.

Your gross margin35%
5%80%

The number this page has that a bank's calculator does not. A repayment is a cost; what matters to a business is the sales it has to write to cover it. Set your own margin and the readout converts one into the other.

Indicative monthly repayment$1,551
Weekly$357
Rate you are testing11.00% p.a.
Interest over 4 years$14,435
Total repaid$74,435
Get my real numbers

A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees, the term and any security or guarantee in writing, from the lender, before you commit to anything.

What it has to earn$4,431 a month

That is the sales this loan needs to generate at a 35% gross margin just to cover its own repayment. If the borrowed money cannot plausibly produce that, the answer is a different amount or a different term rather than a different lender.

The part nobody puts on the page

Secured, unsecured, and who is actually on the hook

Every business finance page will explain secured against unsecured. Far fewer will tell you that unsecured describes the asset rather than the person, and that in Australian small business lending the company borrows while the directors guarantee. Four rungs, in order of what is actually at risk.

The lightest

Secured against the thing you are buying

A chattel mortgage over a vehicle, or a lender's interest registered against a machine. The business owns the asset from the start and the lender's claim is limited to it. If it all goes wrong, the lender takes the asset.

What is at risk

The asset, and normally only the asset.

The common one

Unsecured, plus a director's guarantee

The word unsecured describes the loan, not the liability. No particular asset has been named, and in most cases the directors have still signed personally, which means the lender can pursue them for the balance if the company cannot pay it.

What is at risk

Everything you own personally, up to the amount you guaranteed.

Heavier again

A guarantee supported by a caveat over property

The step most people do not realise they have taken. A guarantee is a promise; a caveat lodged over your home turns that promise into something attached to a specific title, and it will be found the moment you try to sell or refinance.

What is at risk

The house, in practice, even where the paperwork calls the loan unsecured.

The heaviest

A registered mortgage over property

The lowest rate available to a small business, and the highest stake. It is the right structure for a long, large, genuinely productive borrowing, and it is a poor way to solve a temporary cash flow gap.

What is at risk

The house, explicitly, with the lender able to act on it directly.

Ask one question before you sign anything

Does this lender subscribe to the Banking Code of Practice? The Australian Banking Association says the Code gives safeguards and protections to small business customers and guarantors that are not set out in law, and that those provisions are legally enforceable. It binds the banks that sign up to it. It does not bind a lender that has not. Business credit already sits outside the consumer protections you are used to, so on a non-bank facility the answer to that question is most of what you have.

Four structures

Types of Commercial Loans

Businesses have access to several types of commercial loans, each designed to meet different financial needs.

Term loans

A lump sum loan repaid over a fixed period, ideal for major business investments or expansion.

The structure most people picture when they say business loan. It suits a one-off purchase with a long life, and it suits a temporary cash flow gap badly, because you are still repaying it long after the gap has closed.

Lines of credit

A flexible financing option that allows businesses to withdraw funds as needed to manage cash flow fluctuations.

You draw what you need and pay interest on what you have drawn rather than on the limit. The right shape for a problem that recurs, and easy to leave sitting at its limit permanently, at which point it has quietly become a term loan with none of the discipline.

Equipment loans

Specifically used to finance machinery, vehicles, or essential business equipment, often using the purchased asset as collateral.

The cheapest money on this list, because the lender has something to take. Whether a given item qualifies depends on what it is worth second hand, which is why a lender will finance the excavator and decline the shelving on the same invoice.

Invoice finance

Borrowing against invoices you have already issued but not yet been paid for, so the money arrives when the work is done rather than when the customer gets around to it.

Listed by business.gov.au alongside overdrafts and lines of credit, and the most under-used facility on this page. It suits a business whose customers are good for the money and slow to send it, which describes a great deal of construction, transport and wholesale.

Getting the structure right is worth more than getting the rate right, and it is the part a comparison table cannot help you with. Run the numbers or contact us today.

Six files a bank was not written for

Whose business gets a yes

These are the situations a mainstream lender's credit criteria were not designed around, and what actually happens to each of them on a broker's panel. Every answer has a condition attached, because the honest ones do.

Yes, if

The business is a startup with no trading history

We made the choice to provide finance to all businesses including startups and business buyouts. With no financials to read, a lender reads you instead: the directors' own credit files, the industry, and whatever the money is buying. Expect the guarantee question to arrive early on a startup file, because there is nothing else for a lender to look at yet.

Yes, if

You are buying an existing business rather than starting one

A buyout is assessed on the business you are buying rather than the one you have, so the seller's financials become your application. Get them early. The single most common delay on a buyout is not the lender, it is waiting on a set of accounts the seller has not had prepared.

Yes, if

The ABN is under two years old

Some lenders want two full years of returns and some will assess on BAS and bank statements from twelve months. The paperwork is different rather than heavier, and on business credit the gap between the lenders who will and the lenders who will not is much wider than it is on a car loan.

Yes, if

Your local bank has already said no

As you most likely know by now, getting a commercial loan from a bank isn't usually easy for small businesses. If you've been rejected by your local bank already, Yes Loans can back you up with great commercial loans for your small business. A bank's decline is one lender's policy, not a verdict, and the specialist end of a broker's panel exists precisely for the files a bank's credit criteria were not written around.

Yes, if

There are defaults or arrears against the company or the directors

Both get read on a business application, which surprises people: a director's personal credit file is part of a company's file in practice, because the director is usually the one guaranteeing it. It narrows the panel and moves the price rather than closing the door, and your broker will tell you what it costs before you apply.

Yes, if

You would rather not put the house up

Then say so at the start, because it changes which lenders should see the file rather than whether one will. Some will lend against the asset alone, some will want a guarantee, and some will want property behind the guarantee. Those are three different conversations and it is far cheaper to have the right one first.

Tell us about your business

Hear From Our Customers: We Offer the Best Finance Deals

Yes Loans

263 Albany Hwy, Victoria Park

4.8281 reviews

  • Katie BA big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
  • kirill broughtonThanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
  • Janet ErasmusI cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week

powered by

Perth based, every one of them

The brokers who will read your file

Our hands-on, experienced finance brokers are highly-trained in commercial and business loans. On business credit that counts for more than it does anywhere else on this site, because far less of the paperwork is standardised. Every rating below is that broker's own Google rating as published on the Yes Loans about page.

Goran Babac
Goran BabacGeneral Manager5.0 (22)
Trent Hilliam
Trent HilliamFinance Broker5.0 (18)
Ridge Kidd
Ridge KiddFinance Broker5.0 (18)
Cooper Boyd
Cooper BoydFinance Broker5.0 (4)
Stephen Pastorelli
Stephen PastorelliFinance Broker5.0 (2)
Aidan Daggett
Aidan DaggettFinance Broker5.0 (1)
Paddy Knight
Paddy KnightBusiness Development Manager5.0 (1)
Kim Marchant
Kim MarchantFinance Broker5.0 (1)

3 Steps for Fast Finance

Hands holding and tapping on a smartphone.

Apply online in minutes

Receipt with coins stacked beside it.

We match you to the right lender

Purple shield with a green checkmark.

Get your finance fast

Apply now
Before you apply

What a commercial lender will ask you for

Requirements vary by lender and by how much you are borrowing, but almost every business application starts here. Having it ready is the single biggest thing you control, and on business credit it matters more than on any consumer loan, because there is far more of it.

A small business owner at a desk in a workshop office going through a stack of printed paperwork and manila folders

An active ABN, and how long it has been active

The first thing checked and the thing that most often decides which half of the panel can see your file.

Business bank statements

Usually six to twelve months. A lender is reading the rhythm of the account rather than the balance on any one day, so a lumpy month is normal and an unexplained one is not.

BAS, or financials, or both

What is asked for depends on the lender and the amount. Where the business is young, BAS and bank statements often do the work that two years of tax returns would otherwise do.

Details of the directors

Identification, and consent to check personal credit files. This is the point at which it becomes obvious that a business loan is partly a personal application, which is what the ladder above is about.

What the money is for

A quote, an invoice, a contract or a plan. Lenders price a purchase they can see very differently from a number you have asked for, and the ones lending against a plan will want to read the plan.

And one thing nobody asks you for, which you should bring anyway

A clear answer to what you are prepared to guarantee. Deciding that in your own time, before a lender puts a document in front of you, is worth more than any rate you will be quoted. It is also the only part of a commercial application that is entirely yours to set.

Commercial loans, in the client's own words

Efficient, Affordable Commercial Loans

Do you operate a medium-sized business that needs capital to expand further? Are you a small start-up needing a boost to help get you firmly on your feet? Is your shop in need of a revamp or much-needed updating? Does the thought of going through the minefield that is commercial finance make you weak at the knees?

Look no further than Yes Loans to help with all your business loan needs. We will help you secure the commercial and business loan that will turn your 'want's' into 'have's'. As the leaders in financed loans, Yes Loans is committed to working with business owners across Australia to take their companies firmly forward. We are committed to working with you, every step of the way, in making sure you get the perfectly matched finance solution for your small- to medium-sized business.

Our hands-on, experienced finance brokers are highly-trained in commercial and business loans and will be able to offer you a finance package especially for your unique needs. Yes Loans also offers Car, Truck, and Equipment loans with a multitude of finance options, as well as other solutions such as loan refinancing, and debt repayment.

Go to Yes Loans' Commercial Loan Calculator for a quick and easy view of your potential business loan interest rate and repayment options, now (learn the benefits of using a business loan calculator).

Yes Loans is your one-stop Commercial Loan partner, we have been serving Australian business finance solutions for years. We are based in Perth and service Australia-wide. We made the choice to provide finance to all businesses including startups and business buyouts.
Flexible Repayment Options

Yes Loans offers a variety of flexible options when it comes to repayment of your commercial loan. We know that giving you flexibility in a repayment scheme can be very helpful for you when choosing the option that suits your needs. For tips on managing business debt effectively, explore our article on Debt Repayment Strategies.

If you're new to commercial loans, read our article Commercial Loans: Questions You Need to Ask to make informed decisions before committing. And to explore the benefits of financing near-new vehicles, check out our guide on The Benefits of Purchasing a Near-New Truck.

To find out more about our fast and flexible commercial loans, contact us today.

Read nextCommercial Loans - Questions You Need to askIn the guide What to establish before you commit
What is the total cost of the loan, not just the rateWhat security is the lender asking forHow long is the term, and can it be repaid earlyWhat happens if the business has a bad quarter
A Perth light industrial street at dusk, a work van moving through the last band of gold light on the horizon
Victoria Park, Western Australia

Based in Perth, servicing Australia-wide, and reading business files since 2009.

4.8
from 281 reviews on Google
8
brokers, every one of them in Perth
2009
trading from Victoria Park since
$5,000
the smallest commercial loan we will arrange
Two business partners standing in the doorway of their small business premises in warm late afternoon light

Say YES to taking your business to the next level.

Say YES to fast, efficient service. Say YES to Yes Loans today.

We are based in Perth and service Australia-wide, and we made the choice to provide finance to all businesses including startups and business buyouts. To find out more about our fast and flexible commercial loans, contact us today, or call the office on (08) 9472 3000 and talk it through with a broker who has read the policy.

From the Yes Loans blog

Latest insights

All news and guides

Commercial loan questions

Finance taken out by a business rather than by a person, for a business purpose. That distinction is not a formality: it changes which laws apply, what the lender has to tell you, and what protections you have if it goes wrong. Everything else - the amount, the term, whether it is secured - sits on top of that one fact.

No, and this is the most misread word in business finance. Unsecured means no particular asset has been named as security for the loan. It does not mean nobody has personally promised to repay it. In Australian small business lending the company borrows and the directors usually guarantee, so on most unsecured facilities the directors are personally liable for the balance if the company cannot pay.

A personal promise by a director that if the business does not repay the loan, they will. It sits alongside the loan rather than inside it, which is why it is easy to sign without registering what it does. It is not unusual and it is not a trap, but it is the single most consequential thing in most small business loan documents and it deserves to be read slowly.

It depends entirely on what you signed. A loan secured only against an asset is limited to that asset. A director's guarantee makes you personally liable, which can eventually reach personal assets. A caveat or a registered mortgage over property attaches the debt to that specific title. Those are four different levels of exposure and a business owner is entitled to know which one is in front of them before signing.

No. Credit taken out wholly or predominantly for business purposes sits outside the National Credit Code, which is why business finance has no comparison rate obligation and none of the responsible lending machinery a consumer loan carries. That is a real trade-off rather than a trick, and it is the reason comparing business finance on an advertised rate tells you very little.

It is the Australian Banking Association's code, and the ABA says it provides safeguards and protections that are not set out in law for individuals, small business customers and guarantors, and that its provisions are legally enforceable. The important part is who it binds: banks that subscribe to it. A non-bank lender has not signed it, so on that facility neither the Code nor the consumer credit law is behind you. Ask the question before you sign, not after.

Options can start as low as $5,000 and can scale upwards depending on your needs. What decides the ceiling is not a published limit, it is what the business can service out of its own trading, what the money is buying, and what security or guarantee sits behind it. A broker can give you a realistic figure quickly rather than an optimistic one slowly.

We can extend the terms of a commercial loan up to seven years to accommodate your budget. The right term is usually the working life of whatever the money bought, not the longest one available: financing a three year asset over seven years means paying for it long after it has stopped earning.

You can even apply for a loan from the comfort of your home and get approved in just a few days. What actually sets the pace is the file rather than the lender: business applications need more documents than consumer ones, and an assessor cannot start on an incomplete one. Have the ABN details, the bank statements and the BAS ready before you apply.

Yes. We made the choice to provide finance to all businesses including startups and business buyouts. With no financials to read, the assessment moves onto the directors and onto whatever the money is buying, so expect personal credit checks and expect the guarantee conversation early. Knowing that in advance is most of what makes a startup application go smoothly.
Yes, and it is assessed on the business you are buying rather than the one you already have. The seller's financials effectively become your application, so ask for them at the start. The most common delay on a buyout is not the lender, it is waiting for accounts the seller has not had prepared.

A term loan is a lump sum repaid over a fixed period, which suits a one-off purchase. A line of credit lets you draw what you need and pay interest only on what you have drawn, which suits a gap that comes back. Using the wrong one is expensive in both directions, and it is the most common structural mistake on this page's subject.

Almost always the chattel mortgage. The business owns the vehicle from the start, the lender registers its interest against it, and because there is a real asset behind the money it generally prices better than a general business loan for the same amount. There is also a set of tax consequences worth understanding before you sign anything.

Usually yes, but not the same way. Lenders secure against equipment that holds resale value and tend to put everything else onto an unsecured facility instead. That is why one invoice can come back as two approvals at two different prices, and why it is worth splitting the order rather than accepting one number for all of it.

Because on business credit the rate is genuinely the last thing decided rather than the first. There is no comparison rate obligation, the structures differ far more than consumer products do, and the price depends on the security and the guarantee as much as on the business. Yes Loans is a broker in any case: lenders set rates, per application, after they have read it.

For an asset purchase, rarely. For growth, a second site or a buyout, expect to be asked, because there the lender is lending against a plan rather than against a thing. business.gov.au makes preparing one a step of its own, and a lender reading a plan is really checking one thing: whether the borrowed money produces the income that repays it.

Export Design
Download files for your developer
General
WordPress Builders