We find the car,and we do the negotiating
Not too sure how to get the car you're looking for? We can save you money and time by looking for you. This service is free and can result in you getting a better car deal as we do the negotiating for you.
We have access to a range of car loans that can be tailored to suit your situation, depending on how much you want to borrow and what type of vehicle you are looking for. You won't be waiting for an appointment.
We have access to a range of car loans that can be tailored to suit your situation, depending on how much you want to borrow and what type of vehicle you are looking for. You won't be waiting for an appointment and you can Get Started Online.
Not too sure how to get the car you're looking for? We can save you money and time by looking for you. This service is free and can result in you getting a better car deal as we do the negotiating for you.
We don't like to keep you waiting, so we can usually provide you with an answer within 24 hours (on business days), depending on how quickly we receive all the required paperwork. That last clause is the whole of this page.
This is great if you wanted to start looking for a car, or purchase one at an auction. You know how much you'll be able to borrow and it sets your budget to negotiate before you have the money.
Speed is not a product feature, it is a person knowing which lender will look at your file today rather than on Thursday. That is the job, and it is the only part of this page that a website cannot do for you. That's why you need to meet our team.
It is the same car whichever way you buy it, so the thing that changes from one buyer to the next is not the vehicle. It is the deadline: who set it, how hard it is, and what happens if the money is not there when it falls due. Pick the way you are buying.
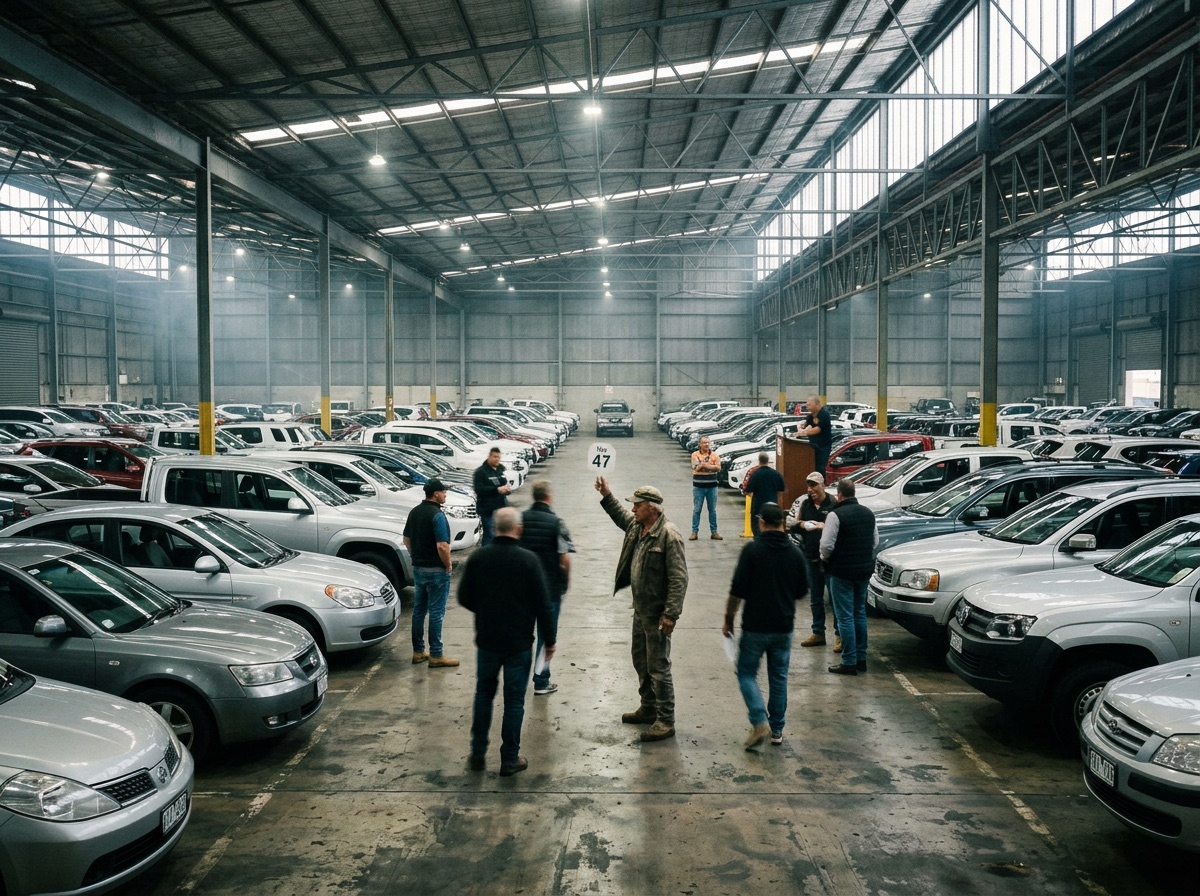
Pickles, Aberdeen Auto Auctions, Manheim Fowles and Grays sell cars in Perth every week, and they are the reason this page exists. An auction is the only purchase on this list where the hammer creates a binding contract on the spot, before anybody has looked at your finance.
Three of those four deadlines are somebody else's, and only one of them can be moved. That is the argument for knowing your number before you go looking, rather than finding out what you can borrow while a seller waits on the phone.
Put the whole purchase in, not just the sticker, and move the numbers around until the weekly figure looks like something you would happily pay in an ordinary month. Then send it to a broker to be turned into a real quote.
A longer term makes the weekly figure comfortable and makes the car cost more. The one thing worth checking is that the term is not longer than you intend to keep the car, because that is how you end up owing more than it is worth.
We are a broker, so we do not set this. Lenders do, per file, and a loan secured against the car normally sits lower on this slider than an unsecured one would. Move it to whatever you want to test and your broker will come back with the rate a lender will actually write.
You will be shown the sharpest end of whatever the panel is offering that week. Try the lower end of the rate slider.
Indicative costs of your own purchase, not ours, and transfer duty in particular scales with the car's value. These are the four lines that most often turn a drive-away price into a bigger number than expected.
A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees and the term in writing, from the lender, before you commit to anything.
Every lender on this search publishes a speed and measures it from a starting line of its own choosing. Here is the whole clock instead, including the stage that happens before anybody starts counting, and the one thing that stops it at each step.
Everything that decides how fast this goes happens here, which is why it is the stage nobody advertises.
Photo ID, your last two payslips, around ninety days of bank statements, and if you are self-employed your BAS. Gathering it takes an evening. Gathering it after you have applied takes a week, because each missing item goes back and forth one at a time rather than all at once.
Applying first and finding the documents later. It feels faster and it is measurably slower, because the file sits in the assessor's queue and loses its place every time it is returned to you incomplete.
The part every competitor on this page advertises, and the shortest stage of the four.
A few minutes online with your details, the amount and what you are buying. One application through a broker reaches the whole panel, which matters more than it sounds: applying to four lenders yourself puts four enquiries on your credit file, and lenders read the pattern.
Shopping by submitting applications. Every one leaves a mark, and a cluster of enquiries in a fortnight is itself a reason for the next lender to look harder at your file.
The stage the speed claims are measured over, and the only one where a document can stop everything.
An assessor reads the income, the commitments and the credit file, and matches them against a lender's policy. On a complete file this is quick, and it is genuinely quick. On an incomplete one it does not start at all, which is why two applications lodged the same morning can finish four days apart.
A bank statement that stops six weeks ago, a payslip from the wrong pay cycle, or a name on the ID that does not match the name on the account. None of them are serious. All of them stop the clock.
The money actually moving, which is a separate event with its own paperwork and its own delay.
After approval the lender needs the contract signed, the vehicle details confirmed, and the seller's account verified. On a dealer purchase this is routine. On a private sale or an auction it needs the seller to cooperate, and on an interstate car it needs a vehicle that is currently on a truck.
Telling a seller you are approved and treating that as the money being there. Approval is a lender's yes; settlement is the transfer. Give the gap between them a day or two of room, especially over a weekend.
Only one of those four stages is genuinely on the lender's side of the desk, and it is the shortest. The variable that decides whether this takes a day or a fortnight is whether the file was finished when it arrived, and that one is entirely yours.
Turnaround is not one number across a panel. It is a different number per lender, and it changes depending on what your file has in it. These are the six situations that most often decide which lender your application should go to, and therefore how long it takes. Every answer has a condition attached, because the honest ones do.
Paid or unpaid, a listed default does not end the conversation. It narrows the panel and it moves the rate. With our prompt efficient service, we may even be able to arrange loan products for people that have had credit problems - and putting a higher rate into the estimator above will show you what that actually costs a week before you decide anything.
There are lenders who will assess an ABN as young as twelve months on BAS and bank statements rather than on two full years of tax returns. The paperwork is different, not heavier, and knowing which lender wants which version of it is most of what stops a self-employed file taking three weeks.
Ordinary in Western Australia and handled badly by a lot of online lenders. A lender who understands rosters and shutdowns will assess the whole income rather than the base, which on a FIFO file is often the difference between a decline and an approval.
Some lenders count it and some will not, and any page telling you it is never a problem is not being straight with you. Where it counts, it counts as income like any other and the assessment is the same. Tell your broker what the income is made of before you apply and you will not waste an enquiry finding out.
Then say so at the start rather than at the end. A deadline changes which lender the file should go to, because turnaround varies across the panel and the fastest lender for your situation is not always the cheapest one. That is a trade-off worth making deliberately, and it is one you can only make if your broker knows the date.
Then you need a pre-approval, not a fast application. Nothing lodged on a Saturday settles before a Monday deadline, and an auction contract is binding from the hammer whether the finance is in place or not. Start the week before.
Every lender on this search publishes a speed, and they all measure it from a different starting line. Here is what the numbers leave out, and all four are easier to deal with before you are standing next to a car.
Approval is a lender saying yes to your file. Settlement is the transfer, and it happens afterwards with its own contract, its own vehicle verification and its own banking hours. A page advertising a one hour approval is telling you about the first event, not the second.
It is a conditional yes on an amount, given before you have chosen a car, and it is genuinely useful because it lets you commit on the spot. It is still conditional: the lender has not seen the vehicle yet, and a car that fails its checks can undo it. Both facts are worth holding at once.
It does not include the weekend, and it does not include the public holiday. It is also worth remembering which time zone the assessor is in: most lender credit teams are on the east coast, so a file lodged at four in the afternoon in Perth arrives at six or seven in Sydney and is read the next morning.
A PPSR check takes minutes and tells you whether there is money owing on the car. A vehicle inspection takes an afternoon. Neither of them is what is slowing your finance down, and both of them are cheaper than discovering the answer afterwards.
Arrive with the file finished. Photo ID, two recent payslips, ninety days of bank statements, and your BAS if you are self-employed. Every lender on this search is quick once they have that, and not one of them is quick without it. It is the only variable on this page that is entirely yours.
 Yes Loans
263 Albany Hwy, Victoria Park
 A big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
 Thanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
 I cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week
powered by
Turnaround varies across the panel, so which lender your file goes to is most of how fast this moves. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.
Then the order matters more than the speed. At an auction the hammer creates the contract, there is no cooling off period and finance is not a condition of sale. Everywhere else on this page a fast application is enough. Here it is not.
It is a lender's conditional yes on an amount, given before you have chosen a car. It costs nothing, it commits you to nothing, and it turns a room full of cars into a room full of cars you can actually buy. This is great if you wanted to start looking for a car, or purchase one at an auction.
The buyer's premium and the auction house's fees sit on top of the hammer price, and on some vehicles so does the transport. Work out what those come to before you register, then bid to the number that leaves them covered rather than to the number you were approved for.
You know how much you'll be able to borrow and it sets your budget to negotiate before you have the money. That is worth as much at a dealership as it is at an auction, because a price discussion where you already know your ceiling is a different conversation entirely.
Your broker is in Victoria Park, which means the person reading your file is in the same time zone as you and knows which lenders will still be answering on a Friday afternoon in Perth. Call (08) 9472 3000 or get your rate online.
We have access to a range of car loans that can be tailored to suit your situation, depending on how much you want to borrow and what type of vehicle you are looking for. You won't be waiting for an appointment and you can Get Started Online. We ensure that you get competitive interest rates for the new or used car you are looking for.
Fast is the promise on this page, so it is worth being exact about what it describes. It is not a lender working faster than another lender; most of the panel assesses a complete file inside a day. It is the time between you deciding and the money being available, and the largest single variable in that is whether the file was finished when it arrived.
We have access to a range of lenders for boats, caravans, motorcycles and trucks! With our prompt efficient service, we may even be able to arrange loan products for people that have had credit problems.
The one risk in moving quickly is that the finance stops being compared. A dealer's finance desk is one lender, offered at the end of a long afternoon by somebody who would like the car to leave today, and it is the single most common way a good price on a car turns into an ordinary deal overall. Settle the drive-away price first and compare the finance separately.
It is also worth using our online loan calculator before you talk to anybody, so the number you are working to is one you chose rather than one you were shown. Yes Loans is a finance broker: we do not set interest rates, lenders do, per application. What we can do is put the file in front of the lender whose policy already fits it.
We are committed to helping West Australians obtain the finance they need and get the vehicle they want. There's a reason why thousands of people from all over Australia and Western Australia choose Yes Loans every year for car finance. Let us help you and Apply Online Now.
We are committed to helping West Australians obtain the finance they need and get the vehicle they want.
There's a reason why thousands of people from all over Australia and Western Australia choose Yes Loans every year for car finance. Let us help you and Apply Online Now, or call us on +61 894 723 000 and a broker in Victoria Park will tell you what you can borrow before you go looking.
Filling out the form, preparing and submitting the required documents, and what happens while you await loan confirmation. The three stages, in order.
Round the clock availability, minimal documentation, no physical submission and quicker disbursal. Why the online application is faster, and where it is not.
Spreading the cost, managing cash flow, affording a better car and getting it sooner. Ten reasons a car loan is worth comparing properly rather than quickly.
We don't like to keep you waiting, so we can usually provide you with an answer within 24 hours (on business days), depending on how quickly we receive all the required paperwork. That last part is not a disclaimer, it is the whole answer: on a complete file the assessment is quick at every lender on our panel, and on an incomplete one it does not start.
Almost never the lender. It is a bank statement that stops six weeks ago, a payslip from the wrong pay cycle, an employer who is slow to confirm employment, or a name on the identification that does not match the name on the account. None of them are serious problems and all of them stop the clock, because an assessor cannot begin on a file that is missing something.
Photo identification, proof of income such as your two most recent payslips, and around ninety days of bank transaction history. Self-employed applicants may be asked for BAS statements instead of, or as well as, tax returns. It is a short list and having it ready before you apply is the single biggest thing you control.
Getting your rate here will not affect your credit score. One application through us reaches the whole panel, so you avoid the multiple enquiries that come from applying to lenders one by one - and a cluster of enquiries in a short period is itself something the next lender will look at.
No, and the difference matters if you are working to a deadline. Approval is the lender saying yes to your file. Settlement is the money moving, and it happens afterwards once the contract is signed, the vehicle details are confirmed and the seller's account is verified. Leave a day or two between the two, especially over a weekend.
Yes, and for anything with a deadline it is the better order to do it in. A pre-approval is a lender's conditional yes on an amount, given before you have chosen a vehicle. You know how much you'll be able to borrow and it sets your budget to negotiate before you have the money.
Yes, and it costs nothing. Not too sure how to get the car you're looking for? We can save you money and time by looking for you. This service is free and can result in you getting a better car deal as we do the negotiating for you. It is the part of what we do that most people do not know exists.
Yes, but you need the finance arranged before you bid rather than after. At an auction the hammer creates a binding contract, there is no cooling off period, and finance is not a condition of sale. Pickles, Aberdeen Auto Auctions, Manheim Fowles and Grays Online all sell in Perth, and all of them expect settlement inside a short window set in their own terms.
Yes. The lender will want the seller's details and the vehicle's, and it will want to know whether there is money owing on the car before it releases anything. That check protects you as much as it protects them: a car with a security interest on it can be repossessed from you even though you paid for it in good faith.
Often, yes. With our prompt efficient service, we may even be able to arrange loan products for people that have had credit problems. Paid or unpaid defaults, a discharged bankruptcy or a thin file narrow the panel and move the rate rather than closing the door. The honest position is that it costs more, and your broker will tell you what it costs before you apply rather than after.
Yes. Some lenders will assess an ABN as young as twelve months on BAS and bank statements rather than on two full years of tax returns. The paperwork is different rather than heavier, and knowing which lender wants which version of it is most of what stops a self-employed application taking three weeks.
Some lenders count Centrelink and pension income and some will not, and any page telling you it is never a problem is not being straight with you. Where a lender does count it, it is assessed like any other income. Tell your broker what the income is made up of at the start and you will not spend an enquiry finding out.
It comes down to your income, your existing commitments and your credit history rather than to the car. Most car loans we arrange fall between $5,000 and $150,000. Our loan calculator is the quickest way to sanity check a figure before you speak to anybody, and there is a longer answer on how much you could borrow if you want the reasoning behind it.
Usually secured against the car itself, which is why a car loan generally prices better than an unsecured personal loan for the same amount. The lender registers an interest in the vehicle and can sell it if the loan goes wrong. Unsecured car loans exist and are worth asking about where the vehicle is older or the purchase is unusual.
Not necessarily. Plenty of car loans settle with nothing down. A deposit or a trade-in lowers what you borrow, shortens the term you need and can widen the number of lenders willing to look at the file, which matters most on a thin credit file or a rebuild. Both versions are worth modelling on the estimator above.
Compare it rather than refusing it. A dealer's finance desk is a real option and it is one lender's option, offered at the end of a long afternoon by somebody whose interest is in the car leaving today. Settle the drive-away price first, then put their offer next to what a broker has already found for you. They are two separate deals and doing them in that order is worth real money.
Yes, and the finance is rarely the slow part. The lender needs to fund a specific vehicle, so the paperwork has to describe a car that may be on a truck between two states. Get the finance settled before you book the transport rather than after, and budget for the transport, the inspection and the Western Australian transfer as well as the car.
In most cases yes, and paying it out early reduces the interest you pay overall. Whether there is a cost for doing so depends on the lender and on the product, so it is a question worth asking before you sign rather than after, and one your broker will raise with you anyway.