Minutes,not an afternoon
With Yes Loans, the application process is easy and simple with our online application form which only takes minutes.
Are you ready to transform your home, but lack the funds to make your dream renovation a reality? Well, you've come to the right place - Yes Loans. Whether you're looking for some new furniture or a total kitchen renovation, a Yes Loans personal loan can help.
Our flexible loan options are designed to fit your specific needs, ensuring that you can achieve your renovation goals without any hassle.
With Yes Loans, the application process is easy and simple with our online application form which only takes minutes.
Enjoy peace of mind with transparent loans terms with no hidden fees, so you know what you have agreed to before you sign rather than after the first statement.
Fast response times so you can get the funds you need. Our flexible loan options are designed to fit your specific needs, ensuring that you can achieve your renovation goals without any hassle.
Whether you're looking for some new furniture or a total kitchen renovation, a Yes Loans personal loan can help. Want to learn more? Check out our FAQ's here.
Two things settle a home improvement application before your income is even looked at: whether the work needs a building permit, and whether it needs a registered builder. Pick the closest match and we will tell you how a lender reads it, and where Western Australia will get in the way.
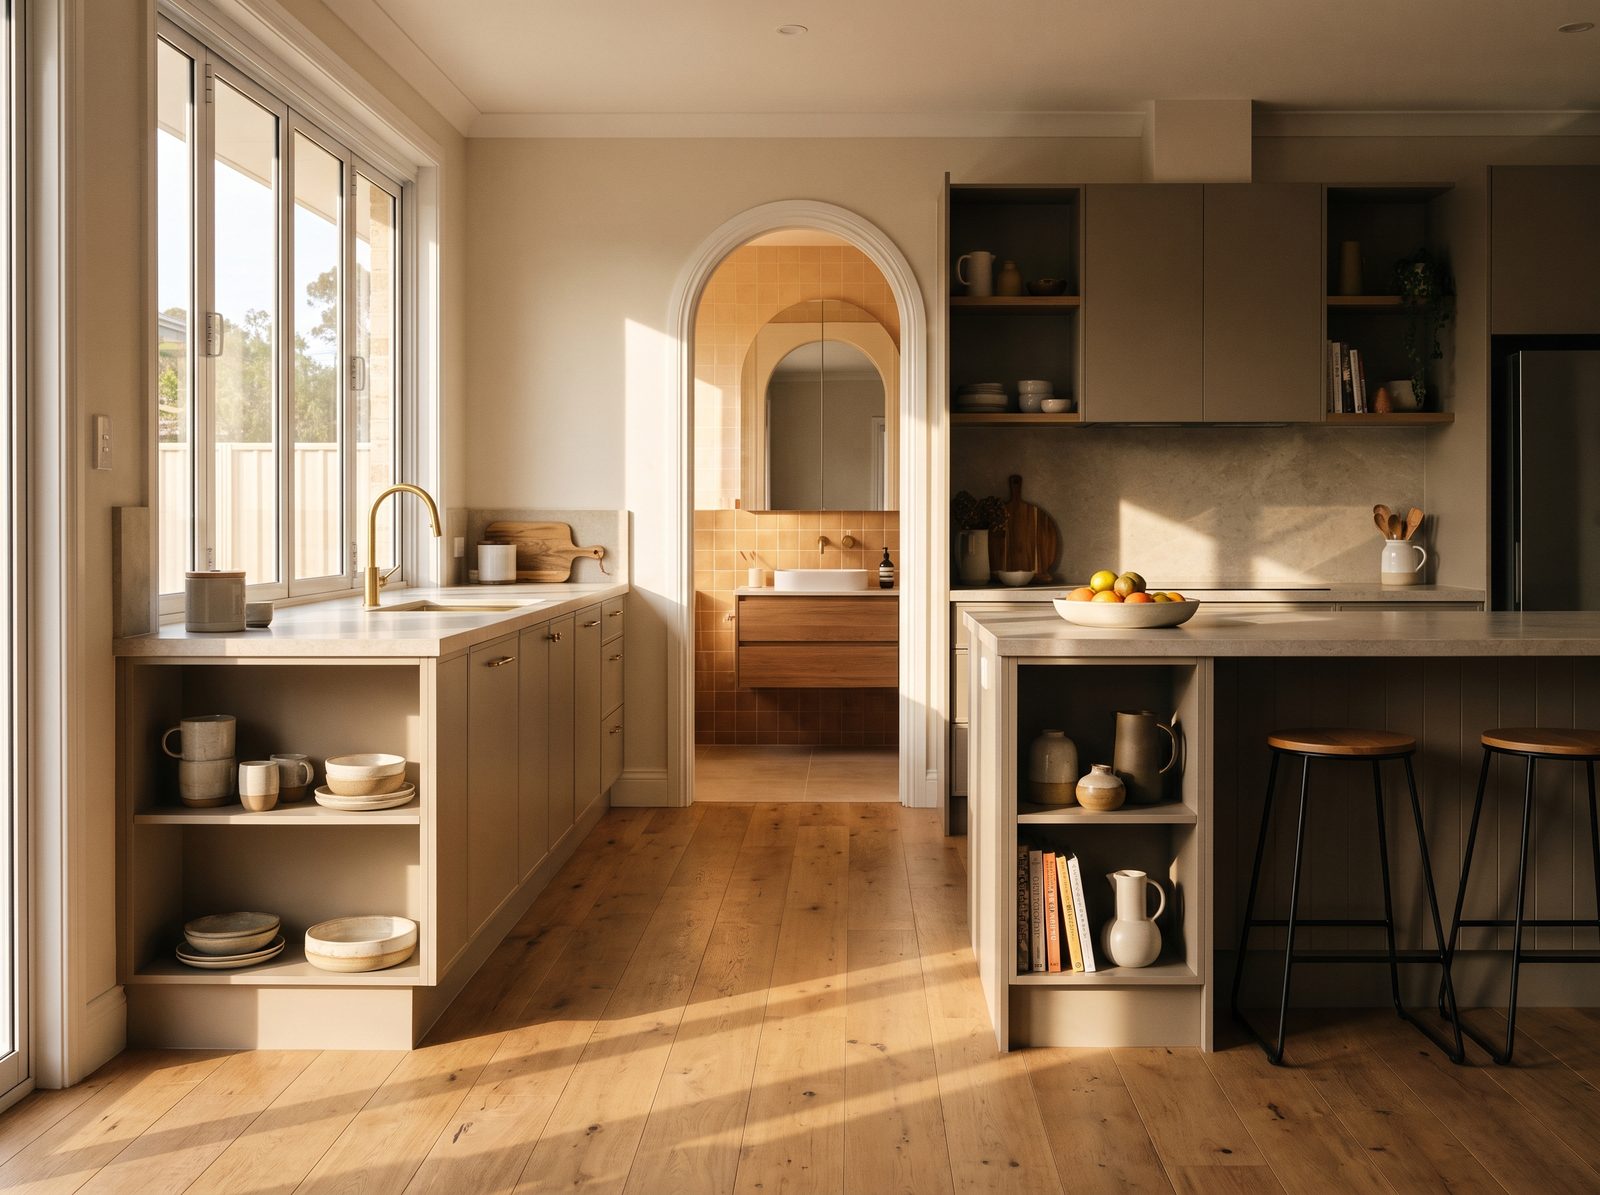
The two rooms people replace first and the two that most often come in over budget, because what is behind the wall is not on the quote. A refit that keeps the plumbing and the walls where they are is a straightforward job. Move a wall or a wet area and it becomes building work, with everything that follows from that.
Not sure which side of the $20,000 line your job falls on? In Western Australia that is the number where building work needing a permit has to go through a registered building contractor or an owner-builder approval, and it changes your timeline rather than your budget. Send us the scope and we will tell you before you commit to a start date.
Move the numbers around until the weekly figure looks like something you would happily pay, then send it to a broker to be turned into a real quote. The contingency slider is the one worth playing with: carrying a buffer costs less a week than most people assume.
The minimum loan amount is $5,000. The top of this slider is the top of the slider, not a limit: what you can borrow above it is set by the lender against your income and your commitments, not by us.
The buffer for what is behind the wall. A personal loan settles in one payment, so this has to be inside the amount you borrow rather than something you ask for later.
We are a broker, so we do not set this. Lenders do, per file, and an unsecured loan sits higher on this slider than a home loan would. Move it to whatever you want to test and your broker will come back with the rate a lender will actually write, fixed for the term.
You will be shown the sharpest end of whatever the panel is offering that week. Try the lower end of the rate slider.
A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees and the term in writing, from the lender, before you commit to anything.
Three ways to pay for a renovation in Western Australia. Only one of them is ours, and it is not the one with the lowest rate. Here is what actually separates them, which is not the rate at all.
The lowest rate of the three, and usually the highest total cost, because the debt outlives the kitchen by two decades.
Adding a five year kitchen to a twenty five year mortgage. Ask for the total interest on both, not the rate on both. On a lot of Perth files the lower rate over the longer term costs more than double the higher rate over five years, and no one shows you that unless you ask.
The right tool for structural work, and the wrong one for anything you could start on Monday.
Assuming your own bank is the best one for it. Lender policy on progress payments and interest-only periods varies enormously, and the difference between the best and the worst is measured in months of your builder's time, not basis points.
Costs more per year and less over the life of the job, because it is finished when the renovation is.
A broker who will not put both totals in front of you. The honest comparison is total cost against total cost, and if this loan is the wrong answer for your project we would rather tell you at the first phone call than at settlement.
It is how long you are going to owe the money. A renovation financed over your remaining mortgage term is a renovation you are still paying for when it needs doing again, and that is true no matter how good the rate looked on the day. Work out the total cost of each option over the life of the debt, then choose. Your broker will do both sums with you, including the one that sends you back to your own bank.
A bank runs one credit policy and yours either fits it or it does not. A broker runs a panel, which is a different job: finding the lender whose policy already has room for your situation. Every answer below has a condition attached, because the honest ones do.
An unsecured personal loan is not secured against the property, so you do not have to own it. Tenants finance air conditioning, appliances and furniture this way all the time. Get your landlord's written consent before anything gets fixed to the building, because the loan is yours either way.
Then the mortgage route is closed and this one is not. Equity is a home loan question. An unsecured personal loan is assessed on income and conduct, so a recent purchase with nothing built up behind it is not the obstacle here that it is at a bank.
Yes, we have low doc loans available to self-employed and contractors that have an ABN number. The paperwork is different rather than heavier, and BAS and bank statements do the work that two years of tax returns would otherwise have to.
Paid or unpaid, a listed default does not end the conversation. It moves the rate and sometimes the amount. Put a higher rate into the estimator above and you will see what that actually costs a week before anybody asks you to apply.
Ordinary in Western Australia and handled badly by a lot of online lenders. A lender who understands rosters and shutdowns will assess the whole income rather than the base, which on a FIFO file is frequently the difference between a yes and a no.
Yes, but the loan term can only be for the remaining term on your visa. If the visa is for 5 years and you have already been here for 24 months, then the maximum loan term is 3 years. Worth knowing before you plan the repayment around a seven year figure.
 Yes Loans
263 Albany Hwy, Victoria Park
 A big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
 Thanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
 I cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week
powered by Google
A Yes Loans broker will take you through the application process and expand on any part of the form you have questions about. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.
A trade worth waiting for in Perth is booked out months ahead, and the quote in your hand is usually good for thirty days. Turning up to that conversation with the finance already conditionally approved changes what you are negotiating: the start date, rather than whether you can commit to one at all.
A lender's conditional yes on an amount, given before you have signed anything with a builder. It commits you to nothing and you can still walk away from the whole idea.
Yes Loans quotes are valid for 30 days, and if you receive pre-approval on your loan it is valid for 30 days as well. That is deliberately the same window most builders give you on a quote.
Nothing. Getting your rate through us does not affect your credit score either, because one application reaches the whole panel instead of you applying to lenders one at a time and collecting an enquiry for each.
Our head office is at 263 Albany Highway, Victoria Park, so the person reading your file lives in the same market as your builder does. Call (08) 9472 3000 or get your rate online.
Curious about your potential loan repayments? Try our free online loan calculator to see how much your repayments could be, and how our flexible payment options can help you pay off your home improvement loan quicker.
With Yes Loans, the application process is easy and simple with our online application form which only takes minutes. Enjoy peace of mind with transparent loans terms with no hidden fees and fast response times so you can get the funds you need. What are you waiting for? Apply now and make your dream home a reality!
Say YES to home improvements. Say YES to Yes Loans today.
Are you ready to transform your home, but lack the funds to make your dream renovation a reality? Apply now and make your dream home a reality, or call us on +61 894 723 000 and we will tell you which loan actually suits the job before you fill anything in.
You've probably seen the ads. An app promises to unlock a slice of your wages before payday, no interest, just
Thinking about a personal loan for a renovation, a holiday, a medical procedure, or to bring a few debts together?
If you've been searching for short term loans in Australia, you've probably noticed the results are a mixed bag.
No. A home improvement loan through Yes Loans is an unsecured personal loan, so it is assessed on your income, your commitments and your credit conduct rather than on what your property is worth. Equity is a home loan question. If you bought recently, or values have moved against you, that closes the mortgage route and does not close this one.
Yes. The loan is not secured against the property, so you do not have to own it. Tenants finance air conditioning, appliances, furniture and window coverings this way regularly. Get your landlord's written consent before anything is fixed to the building, because the debt is yours whatever happens to the tenancy.
Sometimes, and it depends on the size of the job rather than on the rate. A home loan carries the lower rate and stretches the debt over your remaining mortgage term, so a five year kitchen can end up being paid for over twenty five years and cost considerably more in total. A personal loan costs more per year and ends when the project does. Ask for the total cost of both over the life of the debt, not the rate on both. We will do that comparison with you even when it sends you back to your own bank.
A construction loan is secured against your property and pays out in stages as the build progresses, with interest charged only on what has been drawn. It needs approved plans, a building permit and a fixed price contract with a registered builder before it is approved at all. A renovation loan in the sense most people mean it is an unsecured personal loan: one lump sum into your account on settlement, no plans, no valuation, and you pay whoever you like whenever the invoice arrives.
Not for the loan itself. An unsecured personal loan is assessed on you rather than on the works, so no permit is needed to get the money. You may well need one for the work, though. In Western Australia a building permit is required for most structural work, and that is a separate conversation with your local government that is worth starting before you commit to a start date.
For small jobs, yes. In Western Australia, once a building permit is required and the estimated value of the building work is over $20,000, the work has to be carried out by a registered building contractor or by you under an owner-builder approval from the Building Services Board. The threshold is $50,000 for sheds, carports and private garages. You cannot split one job into separate parts each under the threshold to get around it, and owner-builder approvals are currently taking around six weeks to process, so factor that into the timeline rather than the budget.
Yes. The money lands in your account as one payment and there is no restriction on how you spend it, so timber, tiles, paint, a skip bin and hire equipment are all fine. That flexibility is the main practical advantage an unsecured loan has over a construction loan, where the lender pays a builder against a schedule.
The minimum loan amount is $5,000. There is no published maximum, because what you can borrow above that is set by the lender against your income and your existing commitments rather than by us. Our loan calculator is the quickest way to sanity check a figure before you talk to anybody, and the estimator on this page will show you what a given amount costs a week. The same personal loans are used for weddings, travel and medical costs, so if the renovation is one of several things you are planning, tell your broker about all of them at once.
Loan terms run up to 7 years. A longer term lowers the weekly repayment and raises the total interest, and the sensible test is whether the term outlives the thing you are buying. Seven years is reasonable on a bathroom and is a long time to still be paying for a dishwasher.
The interest rate is fixed for the term of the loan, so no interest rate rises. That is one of the real differences between this and putting the work on a variable rate mortgage, where the repayment can move under you for the next two decades.
Often no. A deposit may be required depending on previous credit history or the value of the goods being financed. Putting some of your own money in lowers what you borrow and widens the number of lenders willing to look at the file, which matters most on a thin credit file or a rebuild, so it is worth modelling both on the estimator above.
Often, yes. Paid or unpaid defaults, a discharged bankruptcy or a thin file change the rate and sometimes the amount rather than closing the door. The honest position is that it costs more, and your broker will tell you what it costs before you apply rather than after.
Yes, we have low doc loans available to self-employed and contractors that have an ABN number. The assessment runs on BAS and bank statements rather than on two full years of tax returns, so the paperwork is different rather than heavier.
Yes, but the loan term can only be for the remaining term on your visa. If the visa is for 5 years and you have already been here for 24 months, then the maximum loan term is 3 years. It is worth knowing before you plan a budget around a seven year repayment.
Yes, and check what the state will give you first. The WA Residential Battery Scheme offers a rebate of up to $1,300 for Synergy customers and up to $3,800 for Horizon Power customers, plus a no interest loan of up to $10,000 for households with a combined income under $210,000. Eligibility conditions apply, including taking part in a Virtual Power Plant. No broker can beat no interest, so take that first and come to us for whatever it does not cover.
Yes. Get the fencing, the paving, the pump and the power quoted alongside the shell before you decide what to borrow, because those four are rarely in the pool builder's number and they are not optional. In Western Australia a pool needs its own permit and a compliant barrier, though pools and fencing are treated as incidental structures for the purposes of owner-builder licensing.
Getting your rate here will not affect your credit score. One application through us reaches the whole panel, so you avoid collecting a separate credit enquiry for every lender you would otherwise have approached one by one. The number of enquiries you make does affect your score, so that matters more than most people realise.
The online application takes minutes and a straightforward file is usually assessed the same day or the next. A Yes Loans quote is valid for 30 days, and pre-approval is valid for 30 days as well, which is deliberately about the same window a builder will give you on a quote.
Yes Loans does not set them. Fees are the lender's, they vary across the panel, and any figure we published here would be a promise we are not in a position to keep. What we will do is put the lender's own fee schedule in front of you in writing, alongside the rate and the term, before you commit to anything. If a fee makes a cheaper looking loan the more expensive one, that is exactly the kind of thing a broker is for.
Yes, and it is the step people skip. Most home and contents policies limit or exclude cover while structural work is going on, and an unoccupied house during a renovation is treated differently again. Call your insurer before the first trade turns up rather than after something goes wrong. We arrange insurance as well, so it does not have to be a separate errand.
Often, yes, and it is one of the more sensible reasons to borrow. Card interest on a half finished bathroom is usually the most expensive money in the house. Bringing it together with what you still need to spend gives you one fixed repayment and a date it ends, rather than a balance that moves every month.
In most cases yes, and whether it costs you anything depends on the lender. Ask about early repayment before you sign rather than afterwards, particularly if you expect a bonus, a tax return or a sale to let you clear it ahead of schedule. Your broker will check that clause as a matter of course.