Cheaperto run than a car
Many bikers opt to use a motorcycle to travel to and from work, for ease of access as well as being cheaper to run than a car.
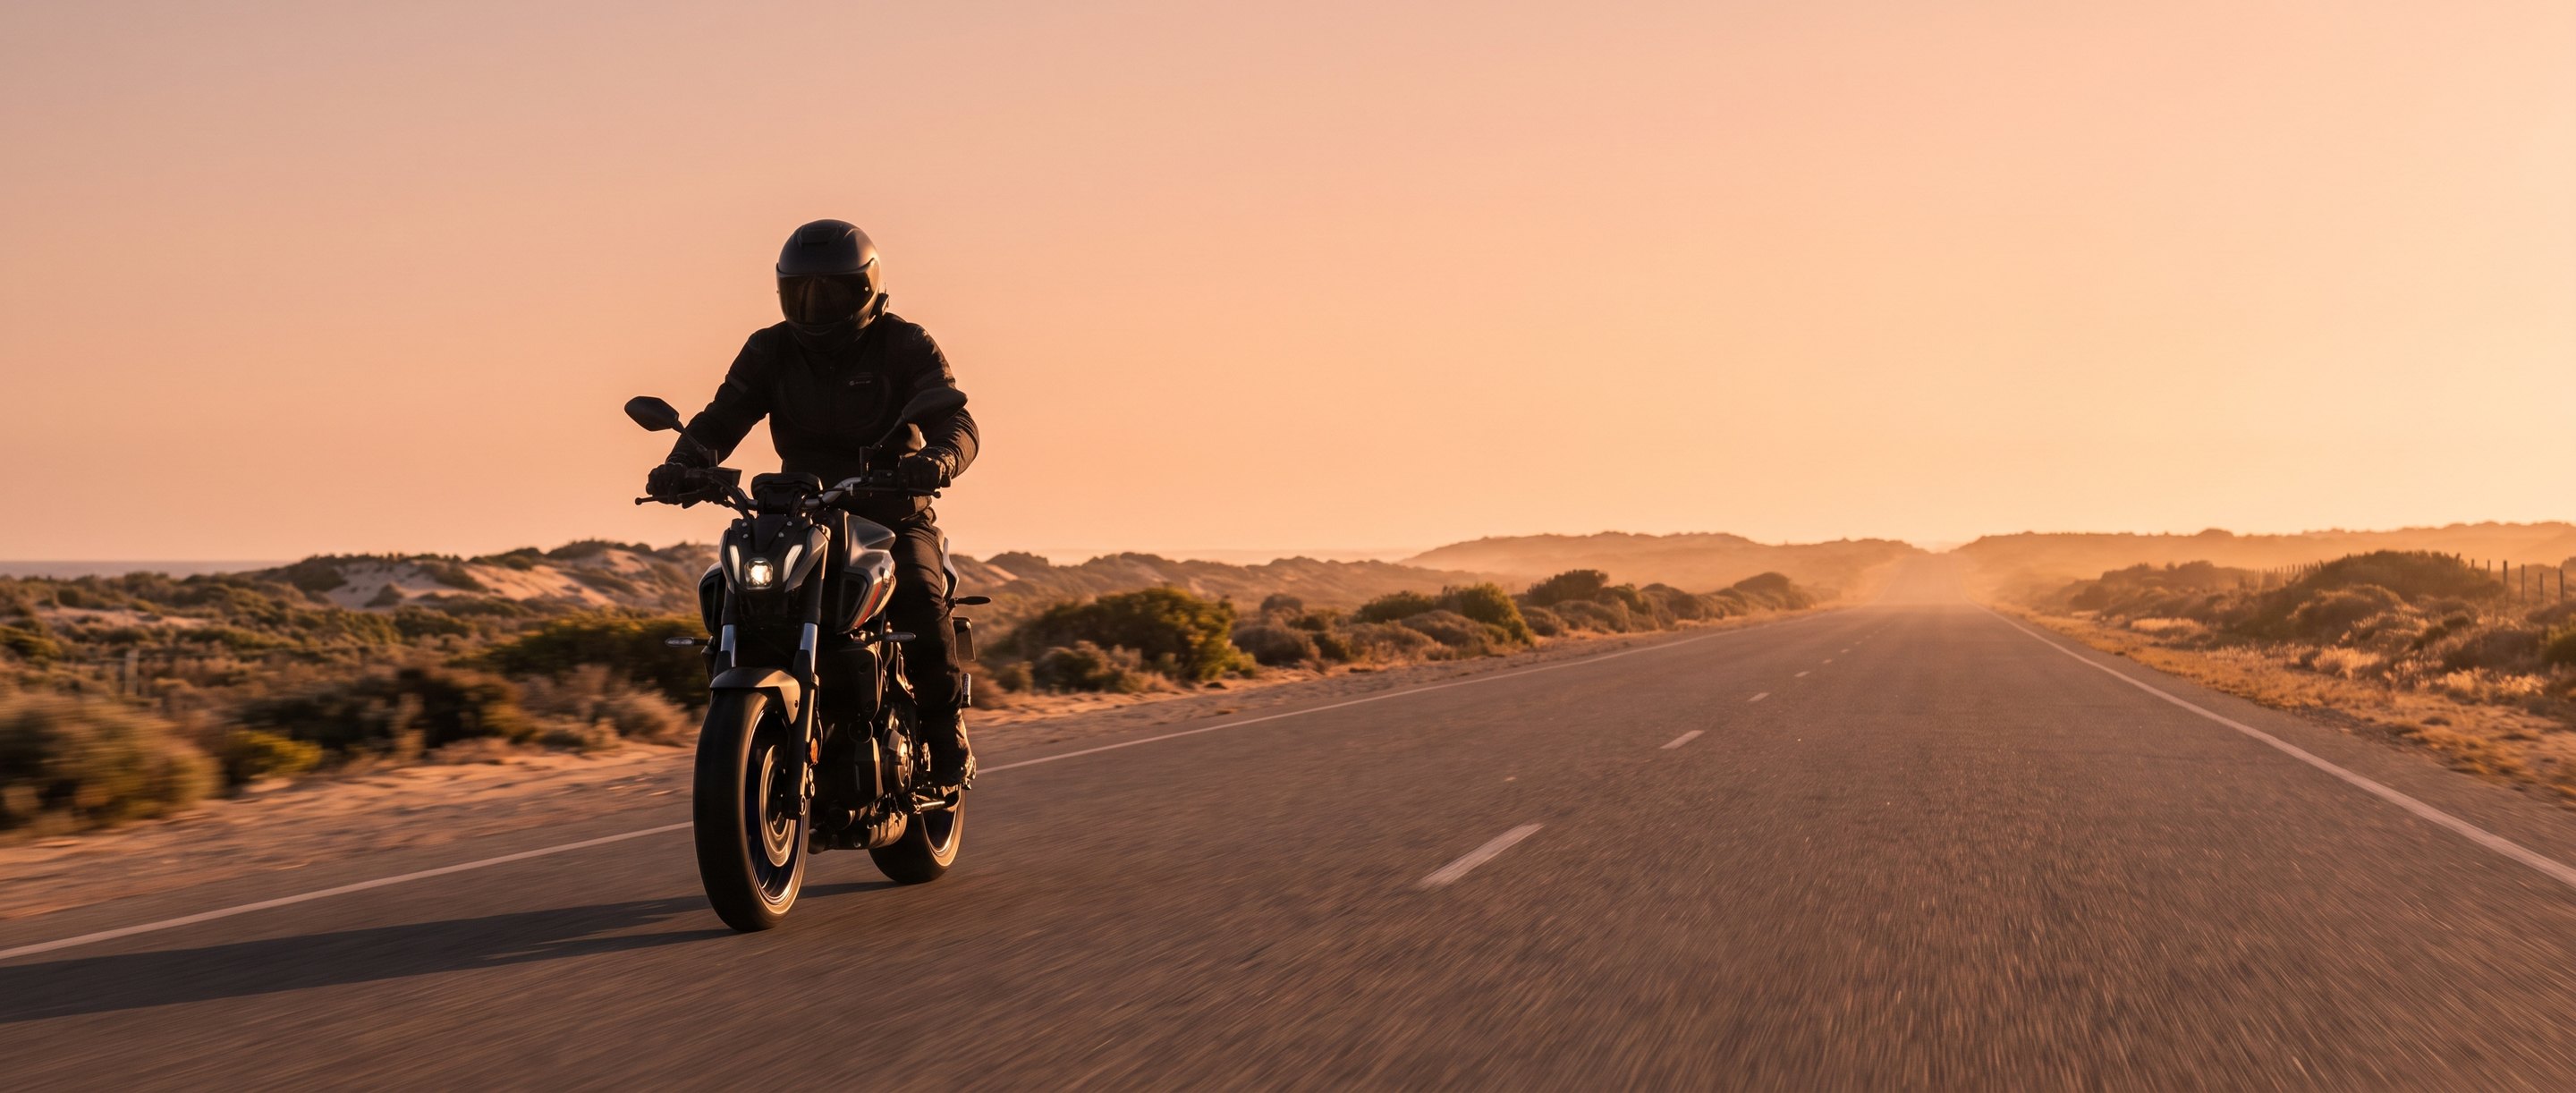
Motorcycle enthusiasts know that the feeling of having only your motorbike and the open road for company, is incomparable. No matter what your reason for needing or wanting a new or used motorbike is, Yes Loans can help make your need a reality today.
Yes Loans specialises in competitively-priced loans, that will have you on your bike and on the open road as quick as possible. A Yes Loans broker will take you through the motorbike loans application process.
Many bikers opt to use a motorcycle to travel to and from work, for ease of access as well as being cheaper to run than a car.
Riders get through congestion and into a parking bay in a fraction of the time, which is why so many Perth commuters end up on two wheels rather than four.
Motorcycle enthusiasts know that the feeling of having only your motorbike and the open road for company, is incomparable.
As always, our experienced (motorbike loving) brokers are on hand to get you the motorbike loans to make your bike ownership possible. That's why you need to meet our team.
Two things settle a motorbike application before your income is even looked at: what your licence lets you ride, and whether the bike can be registered. Pick the closest match and we will tell you how a lender reads it.
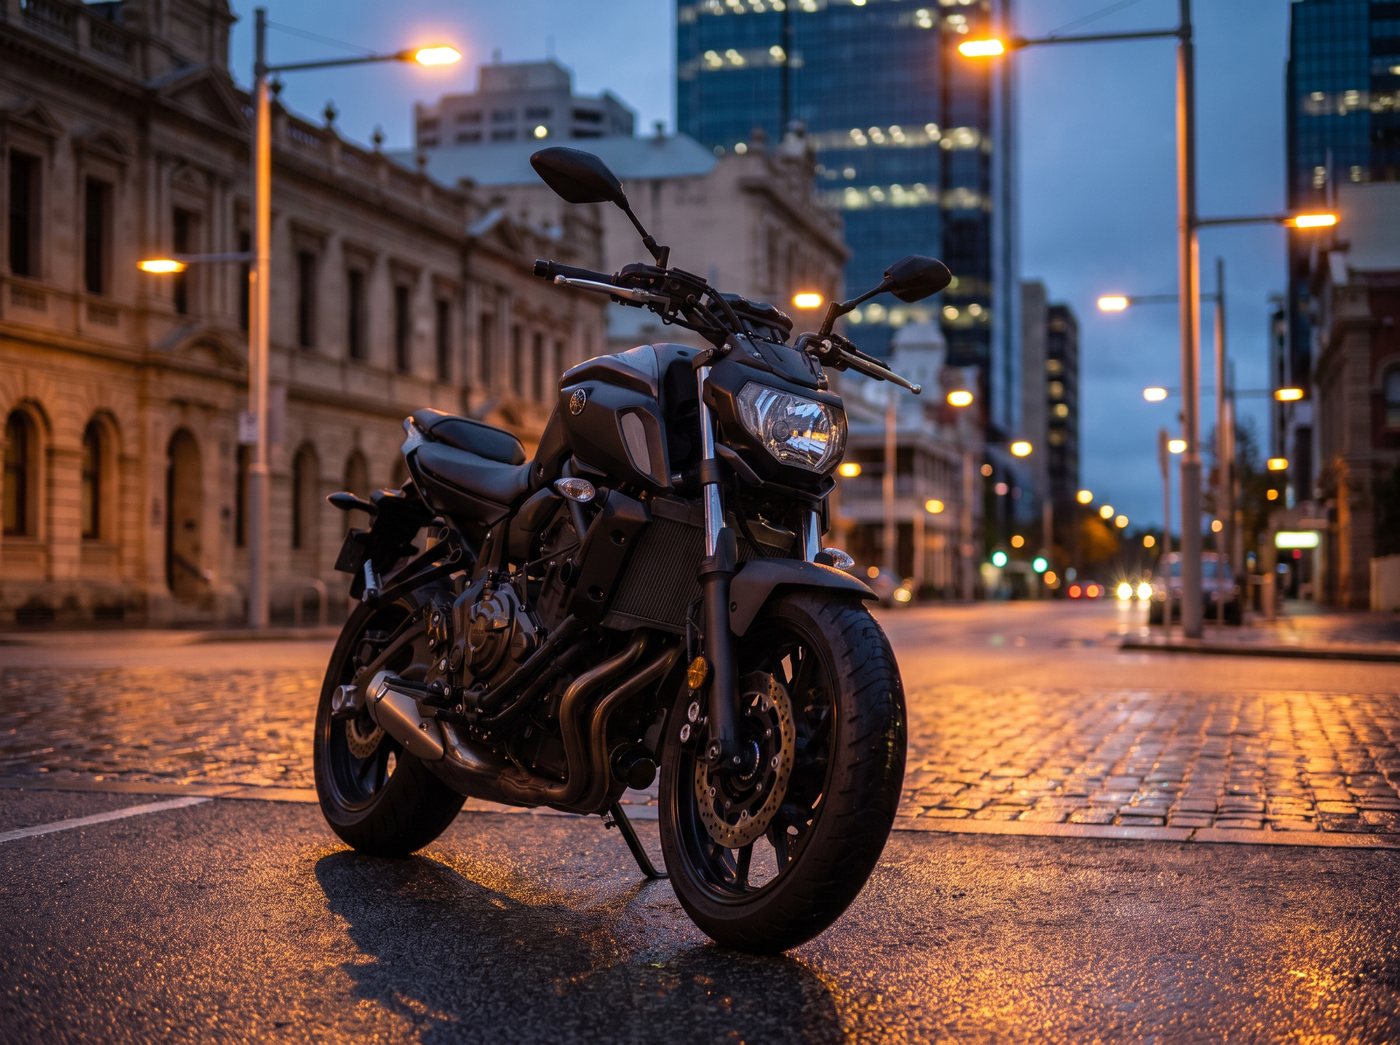
The most common motorbike loan we see once the restricted period is over. Bought to commute on through the week and to enjoy on the weekend, which is exactly the use the live page describes.
Not sure which side of the line your bike falls on? A registered bike can be held as security and an unregistered one cannot, and that single fact decides which loan you are offered. Send us the make, the model and the year and we will tell you before you go anywhere near a dealer.
Put the price and the deposit where yours actually sit, then push the rate around until the weekly number is one you would be happy to watch leave the account every Friday. A broker turns that into a real quote.
We are a broker, so we do not set this. Lenders do, per file, and an unsecured off-road bike will sit higher on this slider than a registered road bike. Move it to whatever you want to test and your broker will come back with the rate a lender will actually write.
The sharp end of the panel is open to you, and a registered road bike is the security lenders are most comfortable with. Try the lower end of the rate slider.
Indicative costs. Anything on the invoice on the day can ride in on the loan; anything bought later is a purchase you fund yourself.
A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees and the term in writing, from the lender, before you commit to anything.
The product does not change between the three. What changes is the evidence a lender asks for, and how many years of term the bike's age leaves on the table.
The easiest of the three files. A new bike's value is not a matter of opinion, so there is nothing for a lender to argue with.
Finance quoted at the counter as a weekly figure and nothing else. Ask which rate produces it, what fees are folded in, and whether a lump sum falls due at the end. A weekly number by itself cannot be compared to anything.
Close behind a new bike, and closer still on a late model with a stamped service book.
A bike that trips the lender's age limit partway through the term you asked for. Worth checking first, because it is knowable in advance.
Where most second hand bikes in Perth actually change hands, and where the value usually is. The same secured rates apply.
Paying a deposit before the PPSR search comes back clear. Photograph the compliance plate and the engine number too, because a re-birthed frame is a great deal more common on bikes than on cars.
The age that matters is the one the bike reaches on your final repayment, not the one on the compliance plate today. A well kept ten year old bike finances comfortably over three years and can fall outside policy over seven, on nothing but that arithmetic. It is the most common reason a used motorbike application is knocked back, and a broker can check it in about a minute.
A bank runs one credit policy, and a motorbike sits awkwardly inside it: a small loan, against an asset that depreciates quickly, assessed by a team who mostly see cars. A panel is a different proposition, because somewhere on it is a lender whose policy already has room for both you and the bike. Every answer below carries a condition, because the honest ones do.
The most common motorbike file we see. No history is not bad history, but it is unproven, so a lender reads income stability and savings conduct instead. A deposit does a great deal of work here.
Paid or unpaid, a listed default does not end a bike application. It moves the rate, and usually the deposit, and on a loan this size a deposit is a smaller ask than the same percentage would be on a car. Put a higher rate into the estimator above and you will see what that costs a week.
Twelve months of trading is enough for part of the panel, read off your BAS and your bank statements rather than two full years of returns. On a bike sized loan that is a shorter conversation than the same file would be against a mortgage.
Ordinary in Western Australia, and a bike is often the thing sitting under a cover for the three weeks you are away. A lender who reads rosters properly assesses the whole income rather than the base, and does not treat a quiet month of spending as a warning sign.
Couriers, trades and delivery riders finance bikes through the business all the time. If it genuinely earns its keep, a chattel mortgage may be the better structure. Speak to your accountant first, then bring us the answer.
If the rate was set at a dealer counter three years ago it is worth a second look, particularly if your credit position has improved since. Refinancing a bike loan works the same way as refinancing a car loan.
The purchase price is the part everyone budgets for. These four are the part that turns a comfortable repayment into an uncomfortable month, and every one of them can be financed with the bike if it goes on the invoice at the time of purchase.
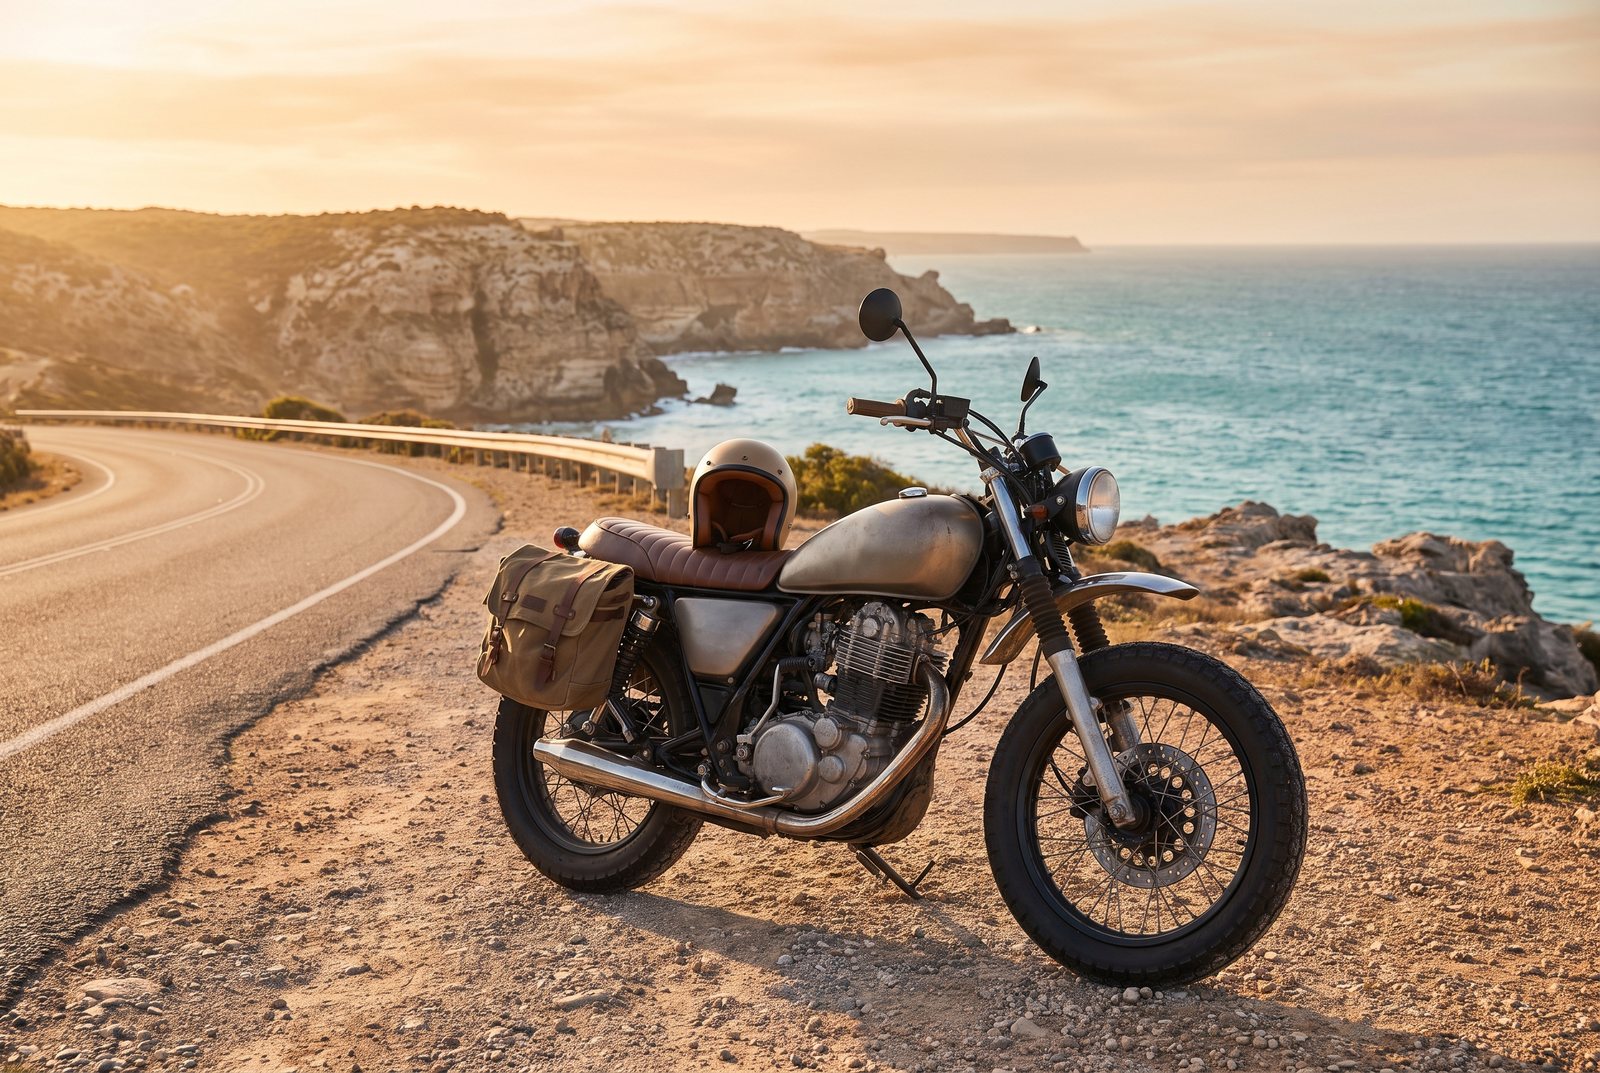
In Western Australia the vehicle licence fee and the compulsory third party cover are paid together, and they start the day the bike goes into your name rather than the day you first ride it.
Charged on the value of the bike when it is transferred to you. On a private sale it lands on the buyer, so budget for it before you agree a price rather than after.
Not optional on a secured loan. The lender holds the bike as security, so cover has to be in place from settlement. We arrange insurance as well, so it does not have to be a separate errand.
Helmet, jacket, gloves, boots, and an intercom if you tour. It is the cost riders leave out of the budget most often, and it is the one standing between you and the road surface.
Gear, luggage, the first year of cover and the on-road costs are all financeable at the time of purchase. Added after settlement they become a separate and more expensive conversation, so decide on them before the paperwork goes in.
 Yes Loans
263 Albany Hwy, Victoria Park
 A big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
 Thanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
 I cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week
powered by Google
A Yes Loans broker will take you through the motorbike loans application process and expand on any part of the form you have questions about. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.
Most second hand bikes in Perth sell privately, and a well priced one is gone in days. Turning up with a pre-approval already in hand changes what you are negotiating: the price of the bike, rather than whether you can move fast enough to buy it at all.
A lender's conditional yes on an amount, given before you have picked a bike. It ties you to nothing, and you can walk away from the whole idea without owing anybody an explanation.
Most stay live between 30 and 90 days depending on the lender, which is comfortably longer than the run of Saturday mornings it takes to find the right bike.
Nothing, and it leaves no mark on your credit file. One application reaches the whole panel, so you avoid the trail of separate enquiries that applying lender by lender leaves behind.
Your broker is in Victoria Park, ten minutes from the Albany Highway dealer strip, so the person reading your file knows the market you are buying in. Call (08) 9472 3000 or get your rate online.
Motorcycle enthusiasts know that the feeling of having only your motorbike and the open road for company, is incomparable. Other than rides on the weekend, or to quell your need for speed, many bikers opt to use a motorcycle to travel to and from work, for ease of access as well as being cheaper to run than a car. No matter what your reason for needing or wanting a new or used motorbike is, Yes Loans can help make your need a reality today.
As always, our experienced (motorbike loving) brokers are on hand to get you the motorbike loans to make your bike ownership possible. One that will meet your needs in terms of the make and model you need, and one that will meet your budget as well.
Finance your next motorbike quickly and easily. Yes Loans specialises in competitively-priced loans, that will have you on your bike and on the open road as quick as possible. A Yes Loans broker will take you through the motorbike loans application process. If you have your eye on a motorcycle that you just cant buy right now, we have some finance options that might help you in the shorterm.
Let Yes Loans help you get that dream motorbike from the showroom to your garage. Our affordable bike finance options can help you take it home today.
Whether you are looking to purchase, simply just browsing, or even a private purchase, one of our brokers will get you a competitive rate for your motorbike loan. Choose Yes Loans today and we'll help you get motorbike finance in a few easy steps.
Use our Motorbike Loans Calculator to work out what the repayments would look like before you talk to anybody.
As one of the largest finance brokers in Perth, Yes Loans says YES to more motorbike loans applications daily. It is our mission, to make sure your need for a new or used motorbike, for pleasure or the daily commute, is met when we can. We will help to make sure the motorbike finance meets your monthly budget.
Say YES to an easy commute. Say YES to Yes Loans today.
Get ready to feel the wind in your hair, and the roar of the motorcycle engine between your knees. Your new or used motorbike is just a click away, apply online now or call us on +61 894 723 000 to discuss your motorbike loans and finance options.
You've probably seen the ads. An app promises to unlock a slice of your wages before payday, no interest, just
Thinking about a personal loan for a renovation, a holiday, a medical procedure, or to bring a few debts together?
If you've been searching for short term loans in Australia, you've probably noticed the results are a mixed bag.
Western Australia uses the Learner Approved Motorcycle Scheme, so on an R-E licence the bike has to be LAMS approved: a power to weight ratio up to 150 kilowatts per tonne and an engine capacity up to 660cc, or an electric motor with a power output up to 25kW. A bike cannot be modified or restricted to make it qualify. Transport WA publishes the approved list, and it is worth checking a specific model against it before you put a deposit down.
Yes, and it works differently. A lender cannot take security over a bike that is not registered, so an off-road bike is financed as an unsecured personal loan rather than a secured bike loan. That costs more than a road registered bike of the same price. It is a normal thing to finance, not a problem, and anyone quoting you road bike pricing on an off-road bike has not read the lender's policy.
A secured loan puts the bike itself up as the lender's security, registered against its VIN. That protection is what buys you the sharper end of the panel and the longer terms. An unsecured loan has nothing standing behind it, which is why it is the only way to finance a bike that cannot be registered, and why it costs more.
Yes. Private sales are where most second hand bikes in Perth change hands and often where the better prices are. We verify the seller owns the bike outright and that there is no finance owing against it, then the lender pays the seller directly on settlement.
A PPSR search against the VIN will tell you, and it takes minutes. Do it before you pay a deposit rather than after. Your broker runs one as part of a private sale purchase anyway, so ask before you hand anything over.
Yes, on the same terms as any other road registered bike. If it is registered and insurable in your name it can be financed as a secured loan, and the smaller purchase price usually means a shorter term makes more sense than the longest one available.
Yes. Whether it is secured comes down to the same question as a dirt bike: if it is registered for the road it can be secured, and if it is not it is financed unsecured. Farm and business use may suit a different structure again, so tell your broker how it will actually be used.
Usually, provided they are written on the invoice on the day. Helmet, jacket, boots, panniers, a screen and the first year of cover all ride in on the loan that way. Walk back into the shop a fortnight later and the same gear is a purchase you fund out of your own pocket, so it pays to decide before the paperwork goes in.
No. Asking us what a bike will cost you leaves your credit file exactly as it was. The reason to come through a broker at all is that a single application is read by the whole panel, instead of you knocking on four lenders doors and collecting an enquiry from each one.
More often than riders expect. Defaults, a discharged bankruptcy or no credit history at all narrow which lenders will look at the file and lift what they want up front, but a bike is a small enough loan that a deposit can do most of the repair work. It costs more, and your broker will put that number in front of you before anything is lodged.
You need it before the bike can be registered and insured in your name, which is what a secured loan depends on. You do not need it to start a conversation or to get a pre-approval, and plenty of riders arrange the finance while they are still working through the licence.
Yes, and for a private sale it is the only sensible order. Most second hand bikes in Perth are sold privately, and the buyer who can settle on the spot is the one who gets the bike. A pre-approval is a conditional yes on an amount, free, non binding, and live for 30 to 90 days with most lenders.
Indicatively between $5,000 and $75,000, which covers everything from a first LAMS commuter to a new tourer. Our loan calculator will sanity check a figure in a minute. Where you land inside that range depends on your income and commitments, and on the bike, because a registered road bike is security a lender can price and an unregistered one is not.
No, and plenty of bikes settle with nothing down. What a deposit buys you on a motorcycle is reach: it shrinks the loan against a fast depreciating asset, which is the thing that makes a cautious lender cautious. On a first bike or a rebuilt credit file it is often what moves the file. Model it both ways on the estimator above.
On a registered road bike, usually. A balloon parks part of the debt at the end of the term to bring the weekly figure down, and you then settle it, refinance it, or sell the bike to clear it. Bikes depreciate quickly, so the risk worth understanding is a balloon that outlasts what the bike is worth. Ask to see it both ways.
The insurer pays out the bike's value, which is not always the same as what is still owing on the loan. That gap is what shortfall cover exists for, and it is a more live risk on a motorcycle than on a car. Your broker will raise it with you rather than leaving you to find out afterwards.
Yes, and dealer counter finance from a few years ago is the version most worth a second look, especially if your credit has improved since you signed it. The process runs the same way as refinancing a car loan.
Over 18, an Australian citizen or permanent resident, and earning an income you can evidence. After that a lender is weighing your income against what you already owe, and weighing the bike against its own age and condition policy. On a motorcycle that second half decides the term more often than the first half decides the answer.