A long candlelit banquet table dressed with white linen, glassware and native flowers, set under festoon lights in the Western Australian bush at dusk before the guests arrive
Wedding loans, Perth brokers, Australia wide

Wedding Loans
Perth BrokerYou are not buying a wedding. You are holding a date, and the deposits fall due long before the day.

The average Australian wedding costs around $35,000 to $38,000, and most couples end up spending more than they originally planned. Venue deposits, catering, photography, florals, the dress, the rings, it adds up faster than anyone expects. A wedding loan lets you cover those costs upfront so you can lock in the suppliers you want, without clearing out your savings or compromising on what matters.

4.8 from 300+ reviewsBrokers in Victoria Park since 2009One application, the whole lender panel

Get your personalised rate

"*" indicates required fields
QuoteGetting your rate here will not affect your credit score

Why use Yes Loans to finance your wedding?

Going directly to one bank or lender means you're limited to whatever they offer. As a broker, Yes Loans shops your application across a panel of lenders, so you get a better picture of what's available and a better chance of finding a rate and term that suits your situation.

A navy fan of lender cards with the front card picked out in red

We compare lenders.You get the better deal.

Our panel includes lenders like Angle Finance, Latitude Financial, Sovereign Credit, Pepper Money, Money3, and Allied Credit. That diversity matters, because each lender has a different appetite for different types of borrowers. We match your application to the right fit, not just the most convenient one.

A navy calendar page with one date circled in red

One to seven years,chosen against your budget

A shorter term means less interest paid overall. A longer term means lower monthly repayments. We help you weigh up what works for your budget both now and after the wedding, which is the half of the decision most people skip.

A navy shield with a red check mark

Imperfect creditis not a closed door

Not every applicant has a clean credit history, and that's fine. Different lenders have different credit appetites. If you've been knocked back elsewhere, that doesn't automatically close the door. Our brokers look across the panel to find the right lender for your situation.

One application,read against the whole panel

A wedding loan is assessed on you rather than on anything you are buying, so which lender reads the file decides the answer. Applying to six of them yourself leaves six marks on your credit report and six chances to be told no. Sending it once, to the lender whose policy already fits, is the entire job, and it is why you should meet our team before you apply anywhere.

The deposit board

A wedding is not one purchase. It is a date, held with deposits.

You are not buying a thing, you are holding a day against every other couple who wants it, and the way you hold it is a deposit. Which is why the question that decides whether you need finance is not how much you can borrow. It is what falls due, and when. Walk the calendar.

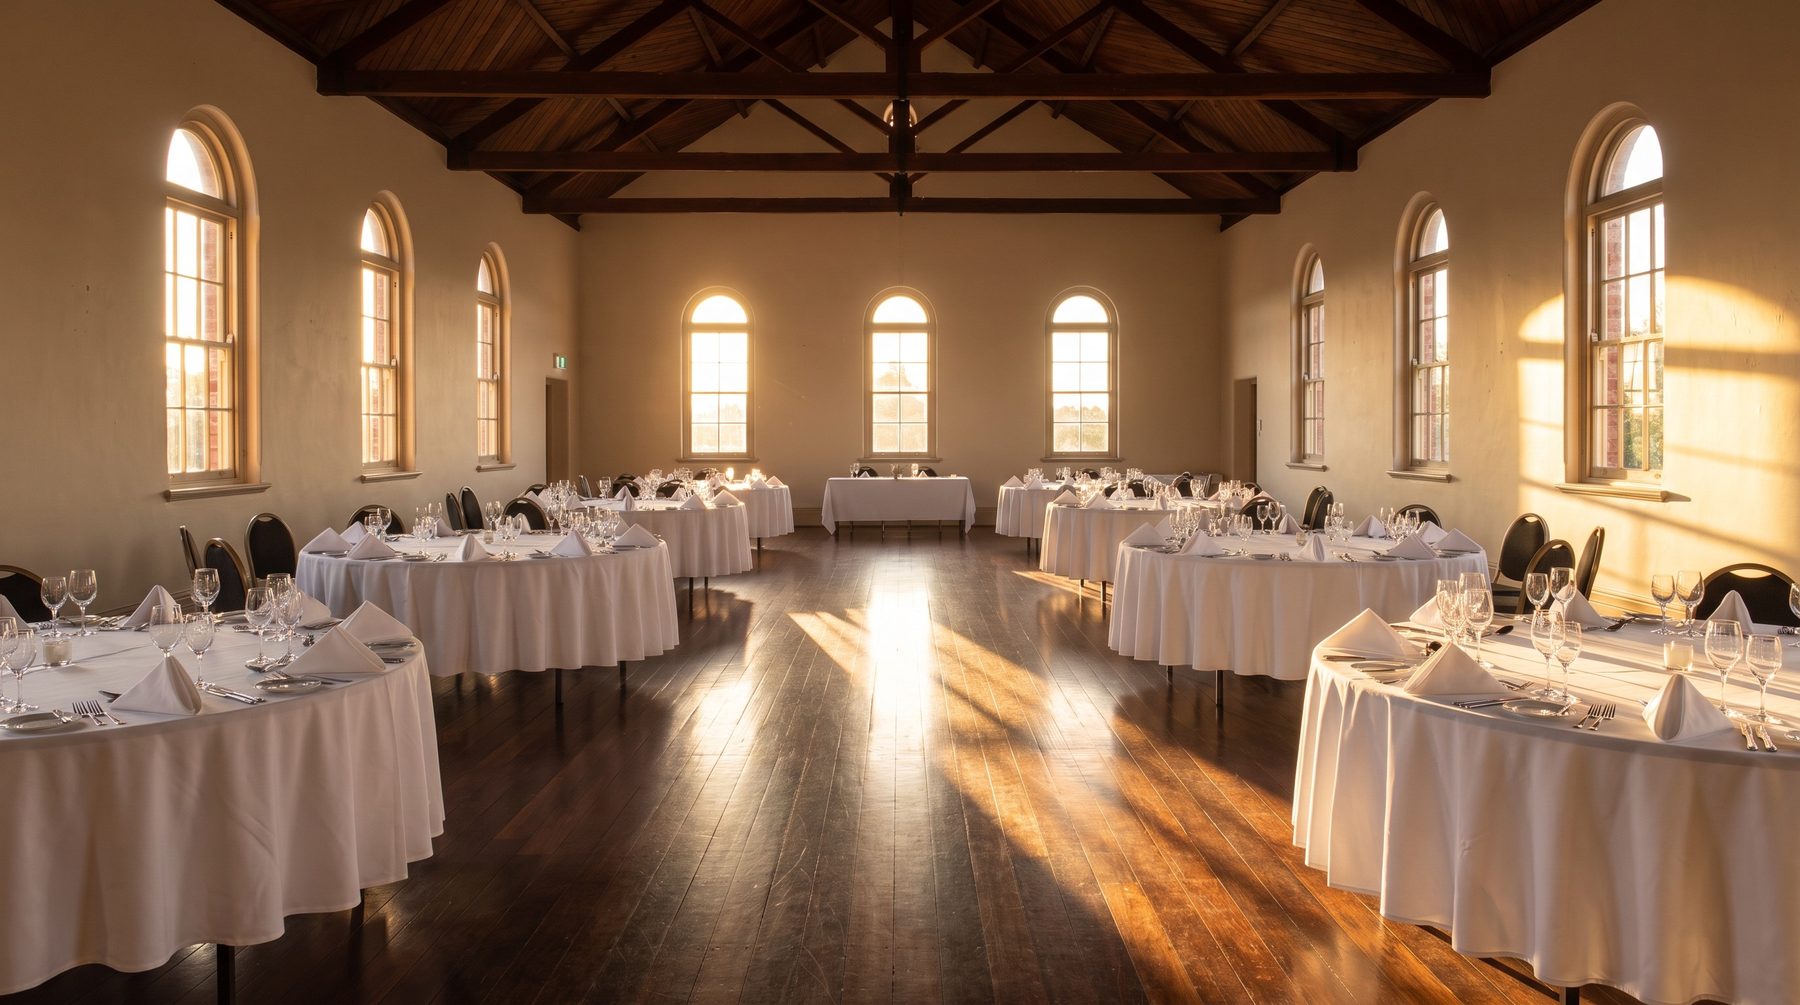
An empty Perth reception venue dressed for a wedding, late afternoon light falling in bands across a polished timber floor
Twelve to eighteen months out

The venue, and the day itself

The first money out is the money that holds the date, and it is the only payment on this page with a queue behind it. A Saturday in a good Perth venue between October and April is sold to whoever signs first, so this deposit is not really buying catering. It is buying priority over the other couples who wanted that day.

What falls dueA booking deposit on signing, then the venue's own payment schedule attached to the contract.
Can you get it backAlmost always non-refundable, and often non-transferable to another date as well. Read the cancellation clause before you sign, not after.
What it means for the financeThis is the payment that decides whether you need finance at all. If the date you want is inside twelve months and the deposit is more than you have sitting in an account, the decision has already been made for you.
Watch forSigning at a venue open day because the incentive expires that afternoon. The incentive is real and so is the deposit, and one of them is refundable.
Talk to a broker about this

Every supplier writes its own terms and the contract is the only source of truth, so treat the stages above as the shape of a normal Perth wedding rather than as anybody's schedule. The useful part is the direction of travel: almost all of it is paid before the day, and almost none of it comes back.

Wedding loan estimator

What will the day actually cost a month?

Put the whole wedding in, not just the venue, and move the numbers around until the monthly figure looks like something you would happily pay in the year after the wedding. There is no rate printed on this page because we are a broker and the lender prices your file, so the rate below is yours to nominate. Try a pessimistic one.

What the wedding costs$20,000
$2,000$60,000
Savings you are putting in10% ($2,000)
Nothing downHalf of it
Loan term3 years
1 year7 years

The one slider on this page worth thinking hard about. A longer term makes the monthly figure comfortable and makes the wedding cost more, and unlike a car there is nothing depreciating alongside the debt to make a long term sensible. Many couples are saving for a house in these same years.

Interest rate to test13.00% p.a.
6%25%

We are a broker, so we do not set this. Lenders do, per file, and a wedding loan sits higher on this slider than a secured car or caravan loan would because a wedding cannot be repossessed. Move it wherever you want to test and your broker will come back with the rate a lender will actually write.

Your credit history

You will be shown the sharpest end of whatever the panel is offering that week. Try the lower end of the rate slider.

Rolled into the loan

Indicative costs of your own wedding, not ours. These are the four lines most often left out of the loan and then paid on a card in the fortnight before the day, which is the most expensive way to buy any of them.

Indicative weekly repayment$170
Fortnightly$341
Monthly$741
Amount financed$22,000
Extras rolled in$4,000
Rate you are testing13.00% p.a.
Interest over 3 years$4,686
Get my real numbers

A guide only, worked out from the rate you chose above. Yes Loans is a finance broker and does not set interest rates. Your broker will confirm the rate, the fees and the term in writing, from the lender, before you commit to anything, and well before the first supplier deposit falls due.

Venue, vendors, rings, honeymoon

What can you use a wedding loan for?

A personal loan for wedding expenses gives you a lump sum upfront. That means you can pay deposits, settle vendor balances, and move forward with your plans without waiting to accumulate the full amount in savings. Wedding loans can cover practically any wedding-related expense, including:

A navy marquee with a red trim

Venue hire and catering

Usually the largest single line, and the one with the earliest deposit and the latest final balance.

A navy camera with a red shutter button

Photography and videography

Booked early because the good ones take one wedding a day, and commonly held with a retainer.

A navy gown on a red hanger

Wedding dress, suits, and formal wear

Made or altered to fit, so the lead time sets the payment date rather than the wedding does.

A navy band interlocked with a red band

Engagement and wedding rings

Often bought a long way apart, and the only part of the day you keep afterwards.

A small bouquet with red flower heads on navy stems

Flowers and decorations

Priced on the season as much as on the arrangement, which is why the quote moves if the date does.

A navy car with a red stripe

Wedding transport and car hire

Charged by the hour on the day, and commonly booked as a package with a minimum.

A navy loudspeaker with a red driver

Entertainment (DJ, band, photo booth)

One booking per date again, and the balance generally falls due with everything else.

A navy aeroplane with a red tail fin

Honeymoon flights and accommodation

Financed on the same loan by most couples, though a separate structure sometimes suits better.

One loan, one repayment, and a clear timeline for paying it off. That simplicity is one reason so many couples choose to finance part or all of their wedding this way.

How the loan is structured

Secured vs Unsecured Wedding Loans: Which Is Right for You?

Most wedding loans are unsecured, meaning you don't need to put up an asset (like a car or property) as security. That suits most couples, because the loan funds everyday wedding costs rather than a physical item.

Unsecured

What most couples take

No asset is pledged, so nothing can be repossessed if the loan goes wrong. The lender is reading your income and your credit conduct and nothing else, which is why the file matters more here than it does on a car loan.

What backs itNothing. You, and your conduct on the file.
What the lender assessesIncome, expenses and credit history.
Who it suitsA day made of services rather than of things.

There is nothing to repossess at a wedding, which is exactly why this is the usual structure.

Secured

Worth a conversation if you have the asset

Secured personal loans tend to come with lower interest rates because the lender holds an asset as a safety net. If you have a suitable asset and want to reduce your rate, it's worth discussing with your broker whether a secured structure makes sense for your situation.

What backs itAn asset you already own, commonly a vehicle.
What the lender assessesThe same file, plus the asset.
Who it suitsCouples with an asset and a preference for a lower rate.

Putting an asset behind a wedding is a real decision, not a discount. Ask what happens to it if the loan goes wrong before you agree to it.

Either way, we'll help you understand what you're signing up for before you commit.

Eligibility

Am I eligible for a wedding loan?

Eligibility for a personal loan for wedding expenses is straightforward for most applicants, and the answer is rarely a flat yes or no. A bank runs one credit policy and yours either fits it or it does not. A broker runs a panel, which is a different job. Every answer below has a condition attached, because the honest ones do.

Yes, if

You are 18 or over, and here to stay

Lenders want an Australian citizen, a permanent resident, or the holder of an eligible visa, and they want you to be at least eighteen. Where a visa is involved the question is usually how long is left on it against the term you are asking for, so bring the visa details to the first conversation rather than the third.

Yes, if

There is a regular income behind it

PAYG, self-employed or otherwise. Regular is doing more work in that sentence than large is: a modest income that arrives on the same day every fortnight is read more kindly than a bigger one that arrives unpredictably.

Yes, if

Defaults or arrears on the file

Paid or unpaid, a listed default does not end the conversation. It narrows the panel and it moves the rate, which on a wedding matters most for timing: a narrower panel takes longer to place, and you are working to a date that will not move. Raise the rate slider on the estimator above, look at the monthly figure, and bring the default up at the first conversation rather than letting the credit check find it.

Yes, if

The repayments have to be genuinely affordable

Every lender tests whether you can service the loan, and they test it against the life you will have after the wedding rather than the one you have now. If you are also saving for a house deposit in those same years, say so, because the assessment will find it anyway.

Yes, if

One of you runs a business

There are lenders who will assess an ABN as young as twelve months on BAS and bank statements rather than on two full years of returns, and there are lenders who will not look at it at all. Knowing which is which is most of the value here. Start earlier than a PAYG couple would, because the document list is longer and the venue will not hold the date while you assemble it.

Yes, if

FIFO, casual, contract or shift income

Ordinary in Western Australia and handled badly by a lot of online lenders. A lender who understands rosters and shutdowns reads the whole income rather than the base rate, which on a FIFO file is routinely the difference between a decline and an approval. It matters twice here, because the same roster decides which Saturdays you can actually get married on.

Yes, if

Only one of you has the income

A joint application puts both incomes in front of the lender, and both credit files with them, so it helps where the second file is clean and quietly hurts where it is not. This is the one question worth asking each other honestly before the application goes in, because the assessment surfaces it either way and the wedding is a poor moment to find out.

Yes, if

There is card debt already, from the engagement or the ring

Then that is the conversation to have first, and it is a common one: the ring is frequently bought on a card a year before anybody starts costing a venue. Rolling the balance into the wedding loan is sometimes the better structure and sometimes not, and the answer turns on what you are already paying rather than on the wedding.

If you're unsure about your eligibility, the best move is to chat to a broker before applying anywhere. Applying directly to multiple lenders without guidance can leave unnecessary marks on your credit file. We assess your situation first, then direct your application to the lender most likely to say yes.

Tell us your situation
The honest part

You are borrowing against a date you cannot move

Which changes what the money has to do, and it is worth understanding before the first deposit goes out rather than after the last one. Four things follow, and three of them are reasons to borrow less than the slider will let you.

An unsigned supplier agreement open on a desk beside a fountain pen and a torn calendar leaf showing a date

The deposits are not refundable. The loan is not either.

Almost every payment on the board above is gone the moment it is made. If the wedding is postponed, the money already committed does not come back and the repayments carry on exactly as written. That is not a catch, it is what an unsecured loan is: money lent to you, not to the day.

If a supplier folds, you still owe the loan

A venue or a caterer going under between the deposit and the date is rare and it does happen, and the loan takes no notice of it. It is the strongest argument for paying deposits in a way that leaves a trail and for reading what each contract says about insolvency, neither of which anyone enjoys doing while planning a wedding.

Gift money is not a repayment plan

Plenty of couples intend to clear the loan with what arrives on the day. Some of it does arrive, rarely all of it, and never on a date you can put into a budget. Size the repayment as though none of it is coming and treat whatever turns up as a way to finish early.

You probably should not finance the whole wedding

An Australian wedding runs around $35,000 to $38,000, and the average wedding loan written in this country is about half of that. The gap is not couples being underserved. It is couples borrowing for the part that holds the date and paying for the rest as they go, which is usually the right shape. Borrow for the deposits and the balances that have a deadline attached, and pay for the rest the way you would pay for anything else.

Broker vs Direct Lender: What's the Difference?

Search for a wedding loan and what comes back is a row of banks and online lenders, each answering with its own money, and comparison sites sending you to one of them. Yes Loans is neither. One application here is read against a panel that includes Angle Finance, Latitude Financial, Sovereign Credit, Pepper Money, Money3 and Allied Credit, which means one enquiry on your credit file instead of six and one conversation instead of six.

Hear From Our Customers: We Offer the Best Finance Deals

Yes Loans

263 Albany Hwy, Victoria Park

4.8300+ reviews

  • Katie BA big thank you to Cooper from Yes Loans for helping me secure my loan for my new car! He was easy to communicate with, always kept me updated, and made ... Morein the last week
  • kirill broughtonThanks to Stephen, for assisting with my loan and making it possible, he dealt with it professionally and was very quick to reply with any questions and ... Morein the last week
  • Janet ErasmusI cannot recommend Trent highly enough. From the very beginning, he was professional, efficient and incredibly committed to helping me secure the right ... Morein the last week

powered by Google

Perth based, every one of them

Meet the broker who will pick up your file

On an unsecured loan there is nothing for a lender to look at except you, so which lender the file goes to is most of the outcome. Every rating below is that broker's own Google rating, as published on the Yes Loans about page.

Goran Babac
Goran BabacGeneral Manager5.0 (22)
Trent Cray
Trent CraySales Manager5.0 (17)
Ridge Kidd
Ridge KiddFinance Broker5.0 (22)
Trent Hilliam
Trent HilliamFinance Broker5.0 (17)
Cooper Boyd
Cooper BoydFinance Broker5.0 (4)
Stephen Pastorelli
Stephen PastorelliFinance Broker5.0 (2)
Aidan Daggett
Aidan DaggettFinance Broker5.0 (1)
Vojin Jancic
Vojin JancicFinance Broker5.0 (1)
Paddy Knight
Paddy KnightBusiness Development Manager5.0 (1)

3 Steps for Fast Finance

Hands holding and tapping on a smartphone.

Apply online in minutes

Receipt with coins stacked beside it.

We match you to the right lender

Purple shield with a green checkmark.

Get your finance fast

Apply now
Pre-approval, Perth

Three to six months out is the window

Earlier is better, and there is a point past which earlier stops helping. A pre-approval is a lender's conditional yes on an amount, given before you have committed to anything, and it is the instrument this whole calendar is asking for.

A venue holds a date for days. An approval lasts months.

When a Saturday comes free or an open day incentive lands, the couple who can sign takes it. A pre-approval costs nothing, commits you to nothing, and most hold for somewhere between 30 and 90 days, which is long enough to cover the decision and short enough to be worth timing.

One application, not six

Applying directly to several lenders to see who says yes leaves a mark on your credit file each time, and the marks are visible to every lender who looks afterwards. A broker submits once, to the lender whose policy already fits. On a thin or imperfect file that difference is worth more than a rate.

Settlement has to beat the final balance

Conditional approval commonly comes back within a day or two of a complete application, and settlement follows within a few business days after that. Work backwards from the week the final balances fall due rather than from the wedding itself, because that week is a fortnight to a month earlier than people expect.

Your broker is in Victoria Park, which means the person reading your file is in the same time zone as you and knows what a Perth venue charges to hold a Saturday in March. Call (08) 9472 3000 or get your rate online.

Wedding loans in Perth

It's not a separate loan product, it's a personal loan with a purpose

A wedding loan is a personal loan used to finance wedding-related expenses. You receive a lump sum, then repay it with interest over an agreed term. Most wedding loans are unsecured, so you don't need to put up an asset to qualify. They're suited to couples who want to lock in vendors, pay deposits, or cover costs that arrive before savings are ready.

There's no formal product called a marriage loan, it's a term used to describe a personal loan taken out for wedding expenses. The loan itself works exactly the same way as any other unsecured personal loan: a fixed amount, a fixed or variable rate, and regular repayments over an agreed term. Anybody selling you a dedicated wedding product is selling you a personal loan with a different word on the brochure.

What does a wedding loan cost?

The interest rate on a wedding loan depends on a few things: your credit history, whether the loan is secured or unsecured, the loan amount, and the term you choose. Rates will vary based on your credit profile, employment type, loan structure, and the lender selected. Your broker will walk you through the actual comparison rate before you commit to anything.

That is the whole reason there is no rate printed anywhere on this page. Yes Loans is a broker rather than a lender, which means we do not set the price of the money and cannot promise you a number before a lender has read your file. What we can do is show you what any given rate does to the repayments, which is what the estimator above is for. Put a pessimistic number in it, look at what the repayments do to an ordinary month, and you will have the only figure that matters before you speak to anybody.

Wedding loans are typically available over terms of 1 to 7 years. A shorter term means less interest paid overall. A longer term means lower monthly repayments. The right balance depends on what you can comfortably repay each month, and on what else those years already have in them.
Read nextHow Much Could I Lend? Your Guide to Personal Loan Borrowing Capacity in AustraliaIn the guide Personal loan borrowing capacity
How Much Can You Actually Borrow with a Personal Loan?What Do Lenders Look at When Deciding How Much You Can Borrow?How Does Secured vs Unsecured Affect Your Borrowing Limit?What Can You Do to Increase Your Borrowing Capacity?
Rows of empty timber ceremony chairs facing a native floral arch on a coastal clifftop in late afternoon light
Victoria Park, Western Australia

Every wedding loan on this page is arranged by the same 9 people in one Perth office.

4.8
from 300+ reviews on Google
9
brokers, every one of them in Perth
2009
trading from Victoria Park since
$0
to get your rate, and no mark on your credit score
Two gold wedding bands lying beside an unsigned supplier contract on dark stone in low evening light

Ready to finance your wedding? Let's talk.

Planning a wedding is one of the bigger financial commitments most couples take on, and getting the finance right from the start makes everything easier. At Yes Loans, we work harder to say yes more often, comparing lenders, matching your application to the right fit, and walking you through the process so there are no surprises on the day.

Whether you're getting a loan for a wedding in Perth or planning from anywhere in Australia, our brokers are ready to help. Call us on (08) 9472 3000 or apply online today and we'll take a look at your options across our panel of lenders.

From the Yes Loans blog

Latest insights

All news and guides

Wedding loan questions

A wedding loan is a personal loan used to finance wedding-related expenses. It's not a separate loan product, it's a personal loan with a purpose. You receive a lump sum, then repay it with interest over an agreed term. Most wedding loans are unsecured, so you don't need to put up an asset to qualify. They're suited to couples who want to lock in vendors, pay deposits, or cover costs that arrive before savings are ready.

Possibly, yes. Credit history is part of the assessment, but it's not the only factor. Some lenders on our panel are set up specifically for applicants with non-perfect credit. What we typically see is that the rate offered reflects the level of risk the lender takes on, so an imperfect credit history can mean a higher rate but it doesn't always mean a flat no. Chat to our brokers and we'll give you an honest picture of where you stand.

Yes. Most personal loans don't restrict how you use the funds, so you can include honeymoon costs, flights, accommodation, travel money, in your loan amount. If you're planning a honeymoon, it may also be worth looking at our travel loans page for options tailored to holiday finance.

There's no formal product called a marriage loan, it's a term used to describe a personal loan taken out for wedding expenses. The loan itself works exactly the same way as any other unsecured personal loan: a fixed amount, a fixed or variable rate, and regular repayments over an agreed term.

Borrowing amounts vary by lender, but through our panel you can generally access wedding loans from $5,000 up to $50,000 or more, depending on your income, credit profile, and the lender selected. For smaller amounts under $5,000, our referral partner MoneyBuddy may be able to help. What you can borrow comes down to your income, your existing commitments and your credit history rather than to what the wedding costs.

Approval times vary by lender. In many cases, conditional approval can come back within 24 to 48 hours of submitting a complete application. Settlement and funds transfer typically follow within a few business days. If you have a deposit deadline or a vendor payment coming up, mention that to your broker so we can prioritise accordingly.

Earlier is better. Many venues and vendors require deposits months in advance, and having pre-approval in place means you can move quickly when you find what you want. As a rule of thumb, applying 3 to 6 months before your wedding date gives you enough room to compare options and settle the loan without rushing.

Before the final balances, which is earlier than the wedding. Most suppliers want everything still owing two to four weeks before the day, so that is the date to work backwards from rather than the wedding itself. Tell your broker the date of the wedding at the first conversation and the schedule follows from it.

Nothing. The repayments continue exactly as written, because the money was lent to you rather than to the day, and the deposits already paid are generally not refundable either. It is an uncomfortable question and it is the reason not to borrow for the parts of the wedding that do not have a deadline attached to them.
Very rarely. A card has no fixed term and no date the debt ends, which is how the same wedding is still being paid off years later without anybody having decided that it should be. A personal loan fixes the amount, the repayment and the finish date before you start. If there is already a card balance from the engagement or the ring, consolidating it is worth pricing at the same time.

Yes, and it is the most common self-inflicted problem we see. Each direct application leaves an enquiry on your credit file and every lender who looks afterwards can see them, so a week of shopping around reads as a person being knocked back repeatedly. A broker submits once, to the lender whose policy already fits.

Yes, and it is often the better structure. Both incomes are assessed and so are both credit files, which helps where the second person's file is clean and hurts where it is not. Worth knowing which before the application goes in rather than after.

Depends on the lender, and it is worth asking before you sign rather than afterwards. Some lenders charge an early repayment fee and some do not, and where there is no fee, paying a lump sum in after the wedding is the cheapest thing you can do with it. Your broker will tell you which lenders on the panel allow it.

Yes, lenders ask for the purpose, and a wedding is an ordinary answer that no lender finds unusual. It does not restrict what you spend the money on afterwards, though it does help your broker pick the lender whose policy fits the shape of the spend.

Talk to a broker about your wedding loan options and you will be told exactly what applies to your situation before anything is submitted. Fees depend on the lender and the structure, and our credit guide sets out how we are paid.

Export Design
Download files for your developer
General
WordPress Builders