primary
#131516
secondary
#F4F4F4
accent
#EE1401
background
#FFFFFF
text
#131516
Golos Text for headings, Inter for body
Campaigns
27 pages
HVAC Contractor Insurance
/hvac-contractor-insurance
Plumbing Insurance
/plumbing-insurance
Electrician Insurance
/electrician-insurance
Landscaping Insurance
/landscaping-insurance
Handyman Insurance
/handyman-insurance
Auto Repair Shop Insurance
/auto-repair-shop-insurance
Remodeler Insurance
/remodeler-insurance
Cyber Liability Insurance
/cyber-liability-insurance
Certificate of Insurance
/certificate-of-insurance
Workers Compensation Insurance
/workers-compensation-insurance
Trucking Insurance
/trucking-insurance
General Liability Insurance
/general-liability-insurance
Professional Liability Insurance
/professional-liability-insurance
Product Liability Insurance
/product-liability-insurance
Commercial Umbrella Insurance
/commercial-umbrella-insurance
Commercial Property Insurance
/commercial-property-insurance
Business Interruption Insurance
/business-interruption-insurance
Tools and Equipment Insurance
/tools-equipment-insurance
Business Owners Policy
/business-owners-policy
Restaurant and Hospitality Insurance
/restaurant-hospitality-insurance
Bar Insurance
/bar-insurance
Construction Insurance
/construction-insurance
Professional Services Insurance
/professional-services-insurance
Directors and Officers Insurance
/directors-officers-insurance
Liquor Liability Insurance
/liquor-liability-insurance
Business Insurance
/business-insurance
Industries We Serve (hub)
/industries
Rebuild tracker
20 of 20 rebuilt on the approved design - open ours and theirs side by side
certificate of insurance
RebuiltA certificate proves a policy and never extends one, so the additional-insured endorsement is what the contract actually wants
cyber liability insurance
RebuiltThe loss splits in two, your own recovery costs and what you owe everyone else, and the sub-limit sits on the half people forget
trucking insurance
RebuiltThe federal minimum is a filing obligation, not a coverage decision, and new authority prices differently from an established carrier
workers compensation insurance
RebuiltPayroll over 100, times a class code rate, times your own claims record: the one policy you partly price yourself
commercial umbrella insurance
RebuiltIt does not widen cover, it raises the ceiling, and the underlying limit it attaches to decides whether it ever responds
general liability insurance
RebuiltEvery contract asks for it by name, so the question is not what it covers but which exposure it silently leaves to another policy
product liability insurance
RebuiltDesign, manufacturing, warning: three defects, and liability follows the product down the supply chain to whoever is still solvent
professional liability insurance
RebuiltClaims-made, not occurrence: the retroactive date decides whether work you did three years ago is covered at all
business interruption insurance
RebuiltThe clock, not the loss: a waiting period before it starts and a restoration period that ends it whether or not you are trading
business owners policy
RebuiltA pre-packaged form with eligibility rules, so the real question is the day the business grows out of it
commercial property insurance
RebuiltTwo valuation choices made at binding, actual cash value against replacement cost, decide what a claim pays years later
tools equipment insurance
RebuiltCommercial property stops at the premises, so tools in a van or on a site are an inland marine problem, not a property one
bar insurance
RebuiltThe premises and the crowd: assault and battery, and the hours when the room is fullest, are what the underwriter prices
construction insurance
RebuiltA hub that routes by trade and by contract tier, and must not argue any single trade's case
professional services insurance
RebuiltAdvice is the product, so the exposure is the engagement letter and the scope of work, not the premises
restaurant hospitality insurance
RebuiltThe kitchen and the food: cooking equipment, spoilage and foodborne illness are the three a standard package handles worst
business insurance
RebuiltNot a policy but a stack, so the page's job is to say which two or three a given business actually starts with
directors officers insurance
RebuiltSide A, B and C decide who is protected when the company cannot or will not indemnify, which is the moment the cover matters
liquor liability insurance
RebuiltDram shop law makes the server liable for what the drinker does next, and it varies by state more than any other liability line
industries
RebuiltEvery industry's gap takes one of three shapes: excluded outright, arriving years late, or needing a policy of its own
No design system yet
Duplicate the master Figma starter, retheme it with figma-client-starter, then run figma-page-build to generate tokens.json. The full brand system appears here once it exists.
Assets
15 files in /clients/rosellabrokerage-com/assets
a2l-plant.jpg
384 KB
claim-brazing.jpg
213 KB
cta-facade.jpg
215 KB
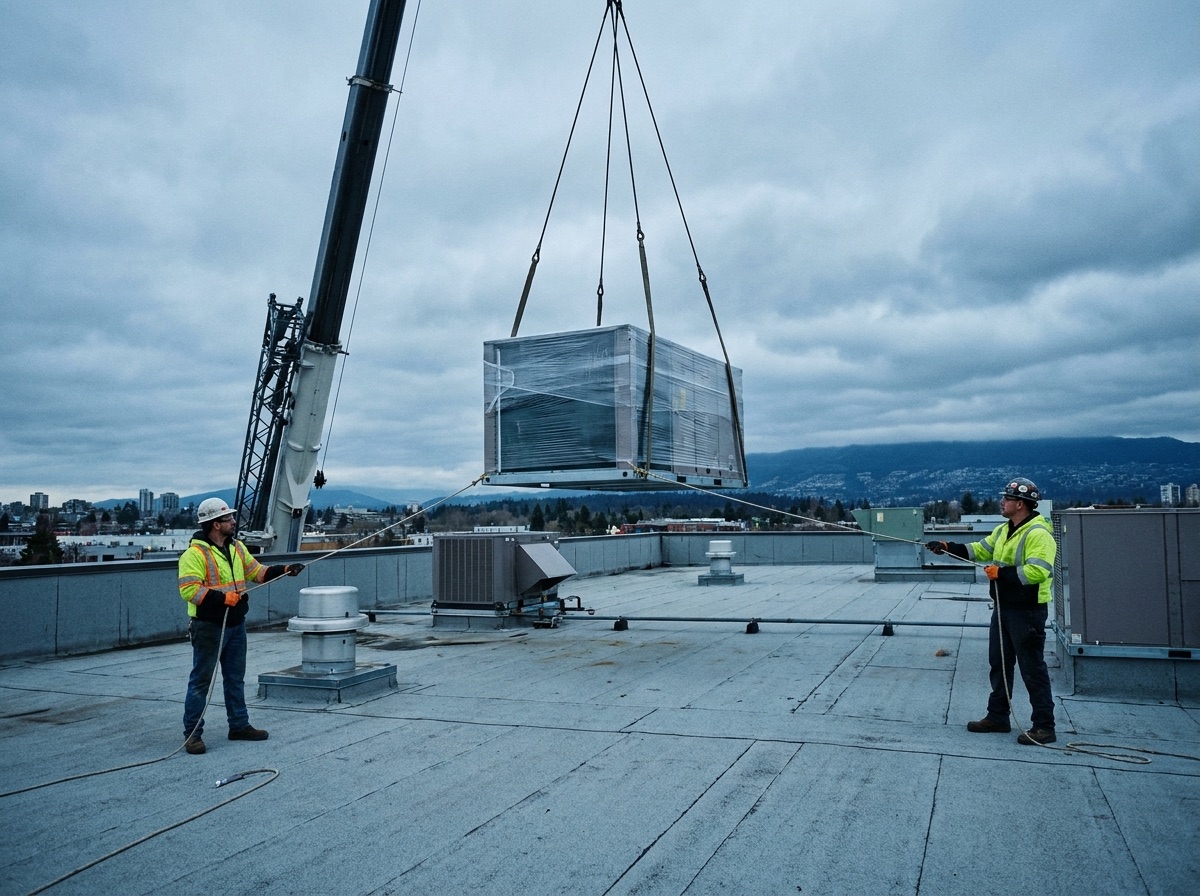
hero-rooftop.jpg
164 KB

logo-mark.svg
1 KB
logo-reverse.svg
4 KB
logo.png
8 KB
logo.svg
4 KB
op-commercial.jpg
329 KB
op-newbuild.jpg
479 KB
op-residential.jpg
209 KB
op-service.jpg
221 KB
step-certificate.jpg
242 KB
step-classify.jpg
201 KB
step-submit.jpg
162 KB